
Continuation coverage refers to the ability of employees to maintain their health insurance benefits after leaving employment or experiencing a reduction in hours.
Key Takeaways
Federal COBRA applies only to employers with 20 or more employees, and Michigan has no state law that extends COBRA-style continuation to smaller employers.
Compliance with health insurance regulations is critical for small employers in Michigan.
Understanding these options can help employers make informed decisions that best suit their workforce.
By CFH Insurance Consultants
Navigating the landscape of employee benefits can be particularly challenging for small employers in Michigan, especially those with fewer than 50 employees. Understanding the various health insurance options and compliance requirements is crucial for these businesses to ensure they provide adequate support for their employees while adhering to state and federal regulations. This article will explore the benefits continuation laws specific to small employers in Michigan, the types of health insurance options available, and strategies to enhance employee benefits. By addressing these key areas, small business owners can make informed decisions that not only comply with legal requirements but also foster a supportive work environment.
See also: Improving Health. Controlling Costs. Delivering Results., our approach for employers who want cost to move between renewals.
8 min read
Continuation Coverage
Federal COBRA applies only to employers with 20 or more employees, and Michigan has no state law that extends COBRA-style continuation to smaller employers. Understanding the eligibility criteria for continuation coverage and the duration of such coverage is essential for compliance and employee support. COBRA administration covers the election notices, deadlines and premium collection that come with every departure.
Overview of COBRA and Mini-COBRA
COBRA (Consolidated Omnibus Budget Reconciliation Act) allows employees to continue their health insurance coverage for a limited time after leaving their job. However, for small employers in Michigan, the state does not have a Mini-COBRA law that extends similar benefits to those with fewer than 20 employees. Federal COBRA does not apply to them either, so continuation coverage is not required by law unless the employer’s plan or insurance contract provides it.
Eligibility Under Federal COBRA
Michigan has no Mini-COBRA law, and federal COBRA covers only employers with 20 or more employees. For those larger employers, employees who lose a job or have hours reduced are typically eligible for continuation coverage, and the employer must send the required notices within set deadlines. An employer under the 20-employee threshold has no COBRA notice duty. See our COBRA guide for the full rules.
Duration of Coverage
Where COBRA applies, employees can maintain their health insurance coverage for up to 18 months after leaving their job or experiencing a reduction in hours. However, this duration may vary based on specific circumstances, such as disability or other qualifying events. Employers close to 20 employees should know these timelines in case they cross the threshold.
Compliance Requirements
Compliance with health insurance regulations is critical for small employers in Michigan. Understanding the various mandates and reporting requirements can help businesses avoid penalties and ensure they are providing the necessary benefits to their employees.
Overview of ACA Mandates
The Affordable Care Act (ACA) imposes several mandates on employers regarding health insurance coverage. Small employers must be aware of these requirements, including the obligation to provide coverage that meets minimum essential coverage standards if they have 50 or more full-time equivalent employees. Failure to comply with ACA mandates can result in significant penalties, making it essential for small businesses to stay informed.
IRS Reporting Requirements
In addition to ACA mandates, small employers must also adhere to IRS reporting requirements. This includes filing forms that demonstrate compliance with health insurance coverage mandates. Employers should ensure they are familiar with these requirements to avoid potential fines and maintain compliance.
State-Specific Mandates
Michigan has specific mandates that small employers must follow, including regulations related to the provision of mental health and substance use disorder benefits. Understanding these state-specific requirements is crucial for small employers to ensure they are providing comprehensive coverage to their employees.
Research highlights the significant impact these state-level mandates can have on small businesses’ decisions to offer health benefits.
Health Insurance Options
Small employers in Michigan have several health insurance options available to them, each with its own benefits and considerations. Understanding these options can help employers make informed decisions that best suit their workforce.
Types of Group Health Insurance Plans
Group health insurance plans are a popular option for small employers, allowing them to provide coverage to their employees at a lower cost than individual plans. These plans can include various coverage options, such as HMO, PPO, and EPO plans, each offering different levels of flexibility and cost-sharing.
Benefits of Offering Health Insurance
Providing health insurance benefits can enhance employee satisfaction and retention. Employers who offer health insurance are often viewed as more attractive to potential employees, which can help small businesses compete in a tight labor market. Additionally, offering health insurance can lead to healthier employees, reducing absenteeism and increasing productivity.
Considerations for Selecting Plans
When selecting health insurance plans, small employers should consider factors such as cost, coverage options, and employee needs. Consulting with insurance experts can help employers navigate the complexities of health insurance and choose the best options for their workforce.
Strategies for Small Businesses
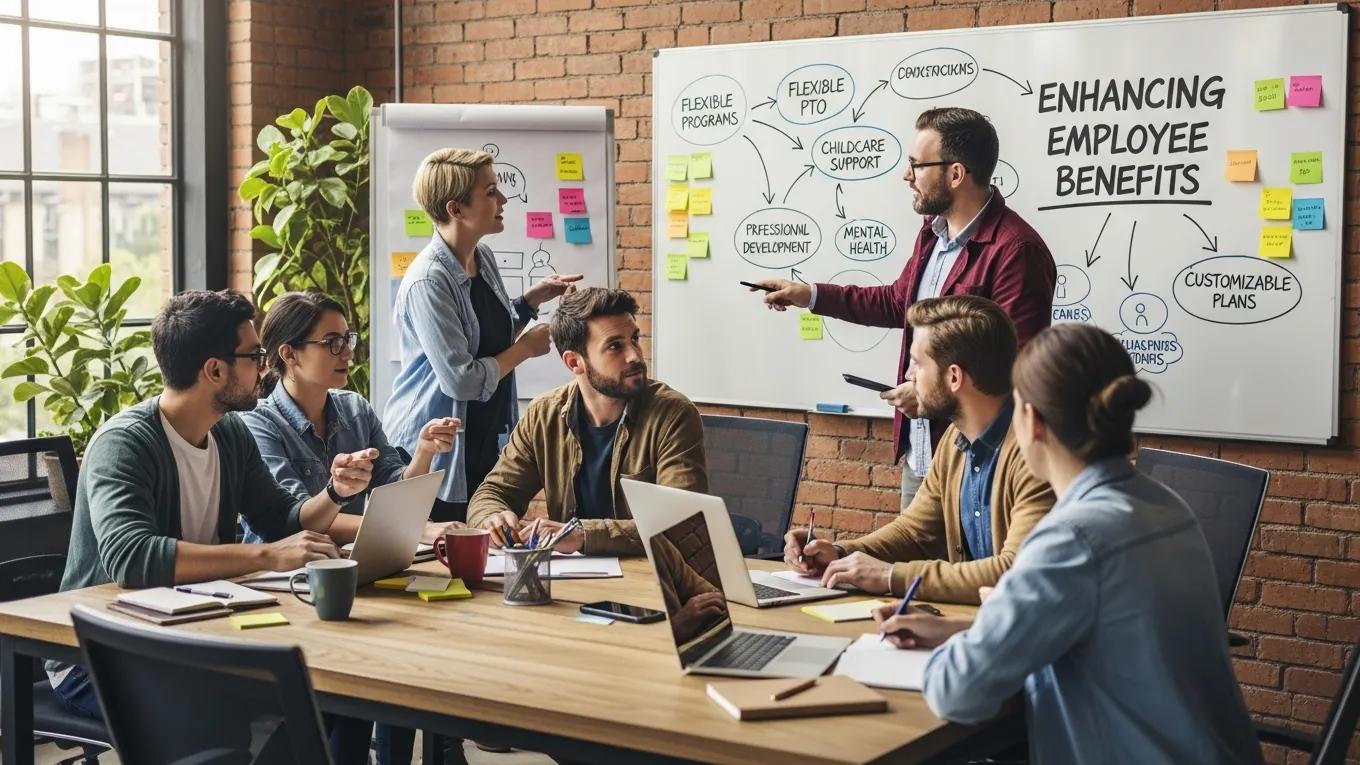
To enhance employee benefits, small businesses can implement several strategies that align with their goals and workforce needs.
Have a Renewal Coming Up?
Send us your renewal and we will tell you whether the increase is competitive. We review it at no cost, and you only need four documents.
Send Us Your RenewalTailoring Benefits Packages
Customizing benefits packages to meet the specific needs of employees can significantly improve job satisfaction. Employers should consider conducting surveys to understand what benefits are most valued by their employees, allowing them to tailor their offerings accordingly.
Consulting with Insurance Experts
Engaging with insurance consultants can provide small employers with valuable insights into the best health insurance options available. These experts can help businesses navigate the complexities of health insurance regulations and find plans that meet both compliance requirements and employee needs.
Understanding COBRA Exemptions & Small Employer Options in Michigan
In Michigan, small employers with fewer than 20 employees are not subject to federal COBRA, and the state has no law that replaces it. Their employees have no legal right to stay on the group plan after leaving. A group conversion right may exist for some coverage, such as plans issued by a nonprofit health care corporation, and the carrier can explain the options.
Eligibility Under Federal COBRA
As noted above, Michigan has no state-level Mini-COBRA law, and employers with fewer than 20 employees are outside federal COBRA. Employers with 20 or more employees use federal COBRA to decide eligibility, and employees who lose a job or have hours reduced are typically eligible.
Coverage Requirements
Employers with fewer than 20 employees are not required to offer continuation coverage under state or federal law. An employer that reaches 20 employees must then provide the required COBRA notices, including eligibility and the duration of coverage. Some small employers let departing employees stay on the plan voluntarily, if the carrier allows it.
Does Michigan Have a Mini-COBRA Law?
Michigan does not have a state-level Mini-COBRA law that extends continuation coverage to small employers with fewer than 20 employees. Federal COBRA does not apply to them either, so there is no legal right to continuation unless the plan or contract provides one.
Comparison of Mini-COBRA and Federal COBRA
The primary difference between Mini-COBRA and federal COBRA is the size of the employer. Federal COBRA applies to employers with 20 or more employees, while Mini-COBRA laws typically apply to smaller employers. In Michigan, employers under 20 employees fall outside both, which leaves employees with fewer options.
Implications for Small Employers
The absence of a state-level Mini-COBRA law means employers under 20 employees have no continuation duty, and employees leaving those employers have no legal right to stay on the group plan. This can create confusion for employees about what their options are.
Michigan Has No State Mini-COBRA Law: What Small Employers Should Know
Small employers in Michigan must understand the implications of not having a state-level Mini-COBRA law. This lack of additional protections can limit the options available to employees who lose their health insurance coverage.
Limited Continuation Options for Employees
Without a state-level Mini-COBRA law, employees of small employers may have fewer options for maintaining their health insurance coverage after leaving their job. This can create challenges for employees who rely on these benefits for their health and well-being.
Compliance Requirements for Small Employers
Employers with 20 or more employees must comply with federal COBRA, including sending the required notices, and failure to comply can result in significant penalties. Employers under 20 employees should recheck their headcount each year, because the test looks at the prior calendar year.
Potential Employee Impact
The absence of a state-level Mini-COBRA law can have a significant impact on employees, particularly those who may struggle to afford health insurance coverage after losing their job. Small employers should be aware of these challenges and consider how they can support their employees during these transitions.
To further support your employees, consider offering comprehensive employee benefits packages.
For small businesses looking to navigate the complexities of health insurance, consulting with insurance experts can provide invaluable guidance.
One option to explore is group health insurance, which can provide coverage to employees at a lower cost than individual plans.
Small businesses might also consider dental and vision plans to enhance their benefits offerings.
Another avenue to explore is QSEHRA and ICHRA, which can provide tax advantages for both employers and employees.
Additionally, offering disability life insurance can provide financial security for employees and their families.
Questions We Get
The questions employers ask us most are answered in full on our resources page.
Unhappy with your current broker? Switch to CFH. Your employees won’t notice. You will.
Related Guides
Small Group Health Insurance Guide for Michigan Employers (2 to 50 Employees)
How small group health insurance works in Michigan and how to compare your options.
Fully Insured, Level-Funded and Self-Funded Plans Compared
The trade-offs between fully insured, level-funded and self-funded health plans.
Employer Benefits Guides: Eligibility, Plan Design, Life Events and Rules
Our library of plain-English guides on eligibility, plan design and compliance.
Where the Rules Come From
The laws named in this article link to the statute or regulation they come from. This is general information, not legal or tax advice, and rules change, so check the current text.
COBRA Continuation Coverage (29 U.S.C. 1161)
Requires many group health plans to offer temporary continuation coverage after a qualifying event.
Affordable Care Act (Pub. L. 111-148)
Sets many of the coverage rules, employer reporting duties and market protections that apply to employer plans.
CFH Insurance Consultants is an independent employee benefits consulting firm. We help employers manage cost, compliance and renewals, and we work in teams for proper coverage of every account.
