
For a shorter primer on the most common self-funded arrangement, see what an ASO (administrative services only) plan is.
Key Takeaways
By CFH Insurance Consultants, CFH Insurance Consultants
Self-funded health plans are arrangements where employers assume the financial risk of providing healthcare benefits directly, instead of paying fixed premiums to an insurance company.
CFH Insurance Consultants emphasizes, “Strategic implementation, including the right partnerships and clear communication, ensures employers capitalize on self-funded benefits while mitigating administrative complexity.”
6 min read
The Complete Employer Guide to Self-Funded Health Plans: Strategy, Stop-Loss Insurance Benefits, Cost Containment, and Compliance
By CFH Insurance Consultants, CFH Insurance Consultants
Some self-funded employers also use reference-based pricing, which pays hospitals a set multiple of Medicare rates instead of relying on network discounts.
For a longer view of cost, see how a year-round health and cost strategy works between renewals.
Self-funded health plans have emerged as an increasingly popular option for employers looking to manage healthcare costs while maintaining control over employee benefits. This authoritative pillar guide answers critical questions about self-funded health plans, including their strategic implementation, the benefits and types of stop-loss insurance for employers, effective cost containment methods, and essential self-funded health plan compliance requirements. Employers face rising healthcare costs and complex regulations; understanding how a self-funded approach can reduce financial burdens while ensuring quality coverage is paramount. This comprehensive resource combines expert commentary, detailed scenarios, comparative tables, and compliance insights to help employers make well-informed decisions regarding their health benefits programs.
What Is a Self-Funded Health Plan?
Self-funded health plans are arrangements where employers assume the financial risk of providing healthcare benefits directly, instead of paying fixed premiums to an insurance company. This model often leads to greater cost control, flexible plan design, and potential savings on premiums. Typically, larger employers benefit most from self-funding, as they can better manage fluctuating healthcare costs and use data analytics for effective claims management. The trade is transparency and flexibility in exchange for carrying claims risk: the employer sees where the money actually goes and can shape the plan around it, but absorbs the variability that a premium would otherwise smooth out.
How Does a Financial Scenario Compare for a 150-Life Employer?
This scenario illustrates how self-funded plans, factoring in TPA fees and stop-loss insurance, can present more predictable costs and reduced financial exposure compared to fully insured arrangements, especially with proper claim and reserve management.
What Are the Best Strategies for Implementing Self-Funded Plans?
To successfully transition to a self-funded health plan, employers should consider the following strategies:
- Conducting Regular Claims Audits: Detailed analysis of claims identifies cost drivers and trends, crucial for accurate forecasting and budgeting.
- Partnering with Reliable Third-Party Administrators (TPAs): TPAs manage claims processing, network access, and member services efficiently, a key factor in plan success.
- Employee Education & Communication: Equipping employees with knowledge about benefits usage improves engagement, health outcomes, and lowers unnecessary claims.
CFH Insurance Consultants emphasizes, “Strategic implementation, including the right partnerships and clear communication, ensures employers capitalize on self-funded benefits while mitigating administrative complexity.”
How Does Stop-Loss Insurance Protect Employers?
Stop-loss insurance is essential for employers self-funding health plans as it caps financial losses from high-cost claims. There are two main types of stop-loss insurance coverage:
According to experts, stop-loss insurance increases budget predictability and lowers financial risk, making self-funded plans attractive to employers hesitant about unpredictable healthcare costs.
Have a Renewal Coming Up?
Send us your renewal and we will tell you whether the increase is competitive. We review it at no cost, and you only need four documents.
Send Us Your RenewalWhat Are Effective Cost Containment Strategies?
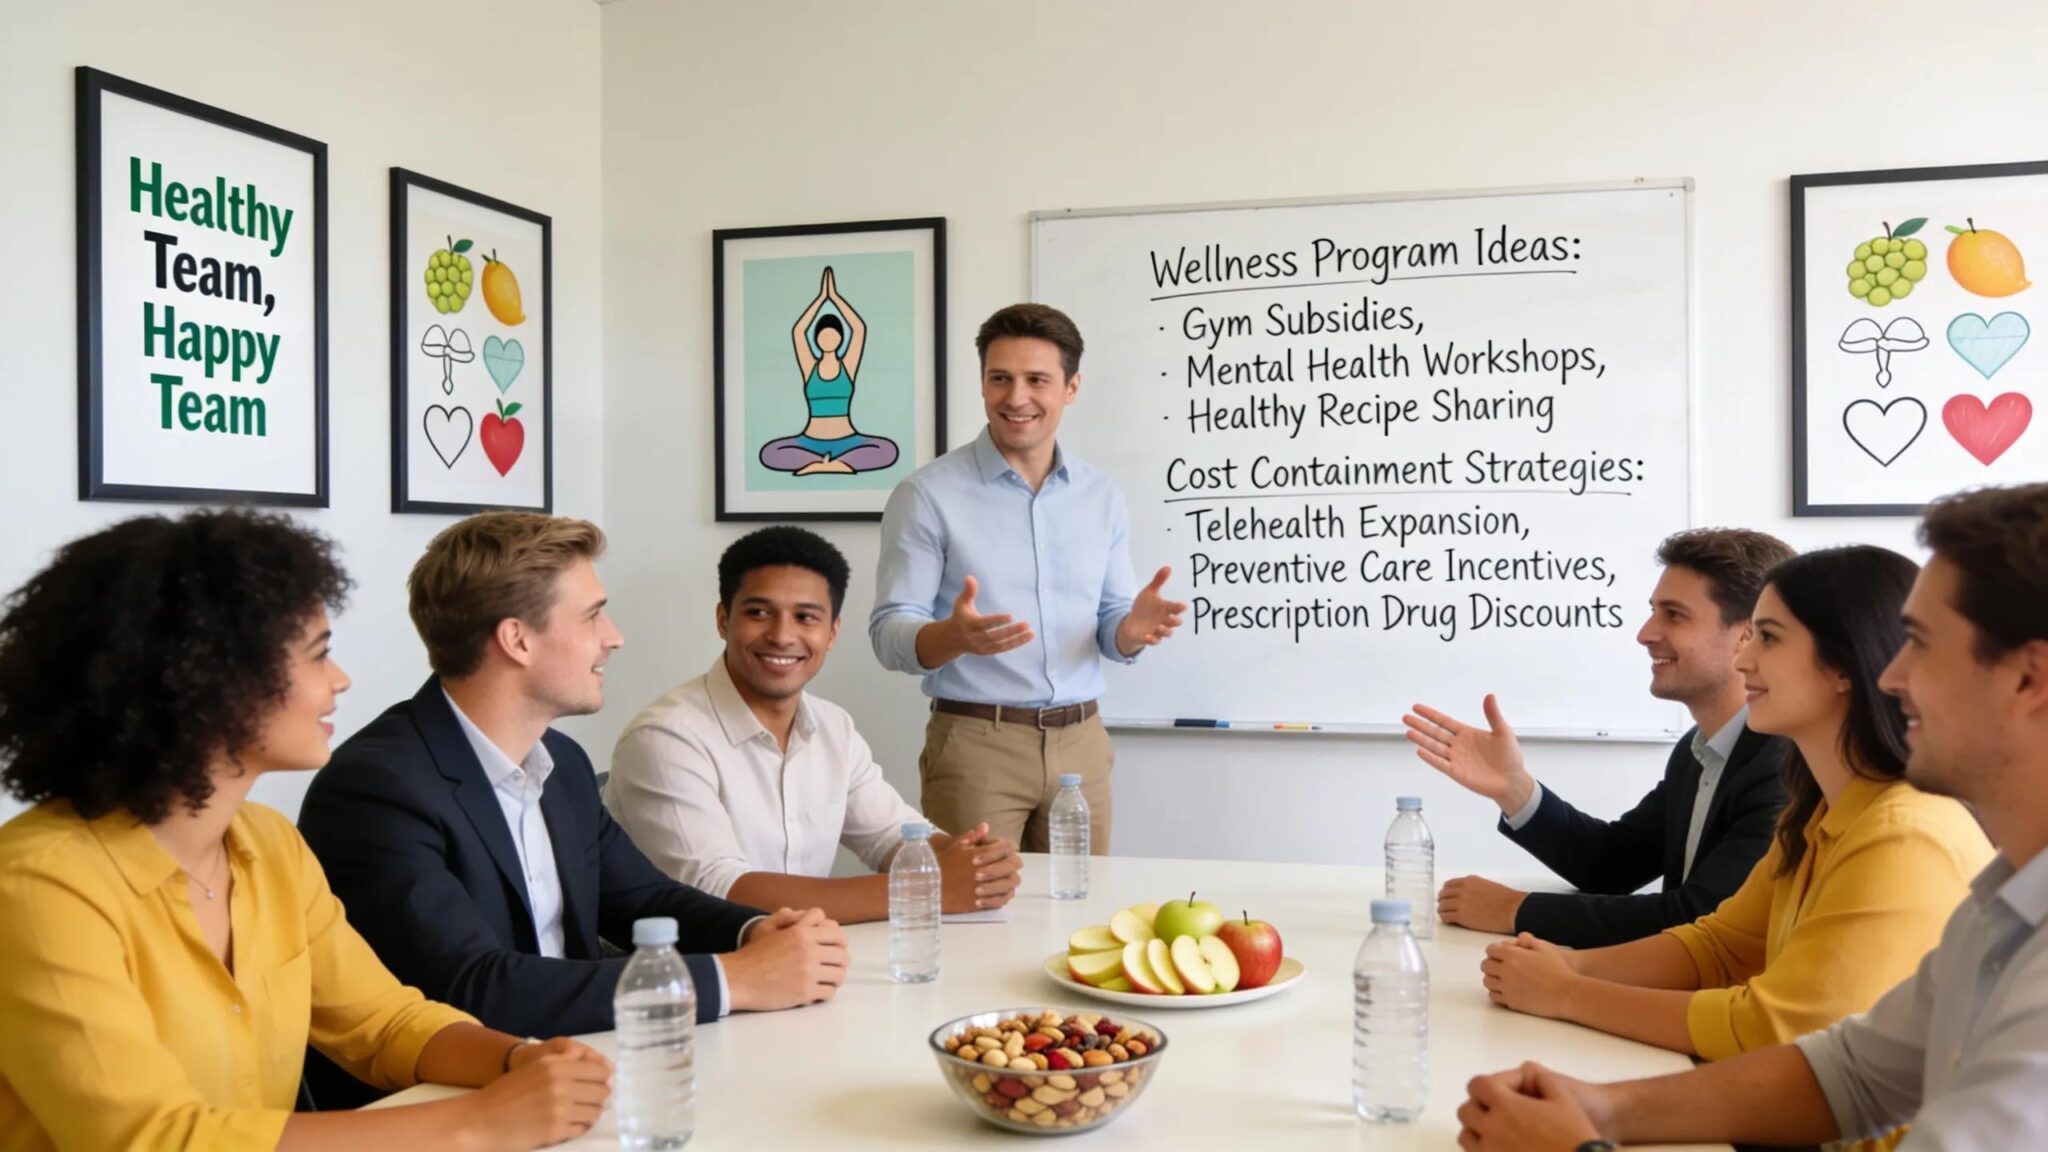
Employers can adopt various cost containment methods to enhance plan sustainability and employee health:
What Are Key Compliance Mandates Under ERISA & CAA?
Employers sponsoring self-funded health plans must ensure compliance with a range of federal and state regulations. Key mandates include:
- ERISA Title I & Section 502: Sets standards for fiduciary responsibility, plan administration, and provides enforcement provisions via claims and appeals processes. Plans must file detailed reports annually, including Form 5500 Schedules A & C.
- Compliance With CAA 2021 Gag Clause Prohibitions: The Consolidated Appropriations Act (CAA) prohibits clauses in contracts and agreements that restrict price transparency and patient access to cost or quality information, enhancing self-funded plan transparency.
- ACA Section 4980H Penalties: Requires large employers to provide affordable minimum essential coverage or face penalties, impacting self-funded plan design and cost decisions.
- State-Specific Regulations: Although ERISA generally preempts state laws for self-funded plans, exceptions exist around certain reporting and consumer protections; employers must verify local compliance requirements.
How Does Self-Funded Health Plan Compliance Enhance Employer Benefits?
Ensuring self-funded health plan compliance protects employers from costly penalties and litigation, builds employee trust, and contributes to smoother operational processes. Careful documentation, robust claims handling procedures, and transparency with participants fulfill both legal and practical needs. CFH Insurance Consultants underscores, “Compliance is not just a regulatory requirement — it reinforces the integrity and sustainability of self-funded programs, fostering long-term employer-employee confidence.”
How Do Self-Funded, Level-Funded, and Fully Insured Plans Compare?
Need Expert Guidance on Self-Funded Health Plan Compliance and Strategy?
Questions We Get
The questions employers ask us most are answered in full on our resources page.
What is a self-funded health plan?
The employer pays employees’ claims directly instead of paying a fixed premium to an insurer. Most employers hire a third-party administrator to process claims and buy stop-loss insurance to limit their risk.
What does stop-loss insurance do?
It reimburses the employer when claims pass a set level, either for one person (specific) or for the whole group (aggregate). It does not pay the plan’s ordinary claims.
Which employers are good candidates?
It depends on the group’s size, claims history, cash flow and tolerance for variation from month to month. We can model both a self-funded and a fully insured option so you can compare.
Do state insurance mandates apply to self-funded plans?
Generally not, because self-funded plans are governed by federal law, though federal rules such as ERISA, HIPAA and the ACA still apply. Your attorney can confirm how this applies to your plan.
What compliance duties come with self-funding?
Typical duties include maintaining a plan document and summary plan description, annual reporting, and nondiscrimination testing. See our other guides for details on each.
Is this legal advice?
No. This page is general information, not legal advice. Rules change and facts differ, so confirm your situation with your attorney or tax advisor.
Our team at CFH Insurance Consultants is ready to help you navigate plan design, stop-loss insurance options, and compliance mandates with confidence.
Related services: self-funded health plans in Bloomfield Hills and level-funded health plans.
Unhappy with your current broker? Switch to CFH. Your employees won’t notice. You will.
Also from CFH: Employee Benefits Consulting Services for Employers · What Is Employee Benefits Consulting and Why Employers Need It · How a Group Health Insurance Broker Can Help Your Michigan Business
Related Guides
Stop-Loss and Claims Risk Before Projected Savings
How stop-loss coverage protects self-funded plans from large claims.
Fully Insured, Level-Funded and Self-Funded Plans Compared
The trade-offs between fully insured, level-funded and self-funded health plans.
Employer Benefits Guides: Eligibility, Plan Design, Life Events and Rules
Our library of plain-English guides on eligibility, plan design and compliance.
Where the Rules Come From
The laws named in this article link to the statute or regulation they come from. This is general information, not legal or tax advice, and rules change, so check the current text.
ERISA (29 U.S.C. Chapter 18)
The federal law that sets reporting, disclosure and fiduciary rules for employer-sponsored benefit plans.
Affordable Care Act (Pub. L. 111-148)
Sets many of the coverage rules, employer reporting duties and market protections that apply to employer plans.
Plan Reporting and Form 5500 (29 U.S.C. 1021-1031)
The annual Form 5500 filing and the plan documents participants must receive.
HIPAA Privacy Rule (45 CFR Part 164)
Limits how employer health plans use and disclose protected health information.
Consolidated Appropriations Act, 2021 (Pub. L. 116-260, Div. BB)
Added the gag clause attestation, broker pay disclosure, parity analysis and drug reporting duties for group health plans.
CFH Insurance Consultants is an independent employee benefits consulting firm. We help employers manage cost, compliance and renewals, and we work in teams for proper coverage of every account.
Related reading
- Incurred vs Paid Basis in Stop-Loss Insurance — The contract basis in a stop-loss policy decides which claims count toward your deductible and when they are paid. An…
- Diagnose — Review the plan, claims, participation and renewal history to find what is actually driving cost. Cost increases have…
- Implement — Handle carrier, vendor and administration changes so HR is not left with the workload. Implementation covers carrier…
- Measure — Track results through the year and adjust before the next renewal. Measurement means checking cost, participation,…
- Benefits cost containment for private equity-backed companie — Portfolio companies are measured on cash flow, and benefits are one of the largest controllable costs. The goal is…
- What Is Lasering in Stop-Loss Insurance? — Lasering is when a stop-loss carrier gives one named person on your plan a higher deductible than the rest of the…
- Do you work outside the renewal window? — Yes. Compliance deadlines, employee questions and plan reviews come up all year, and our team handles them as they do.…
