
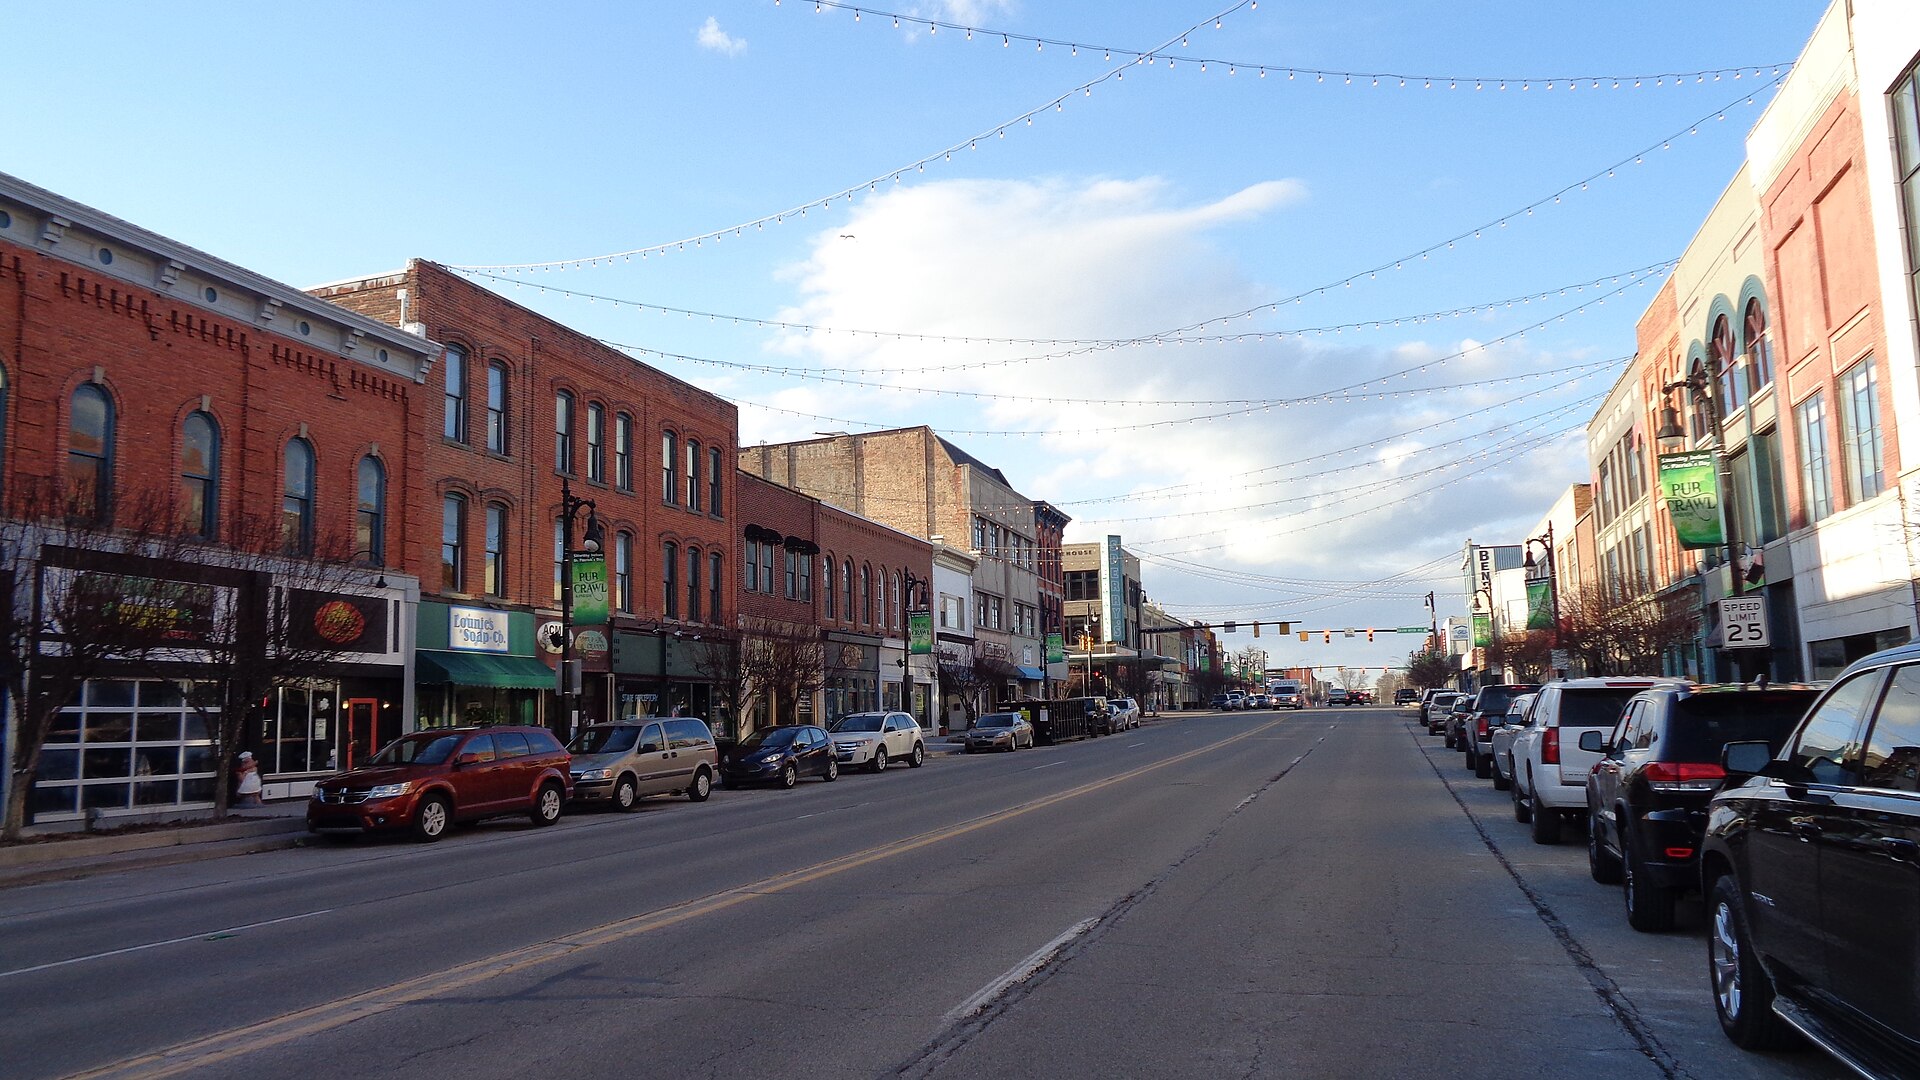
A Border City Has Border Complications
Employers here routinely have Canadian citizens working in Michigan, Michigan residents working across the bridge, and logistics staff whose work is defined by a customs queue. Each of those raises a different benefits question, and none of them is answered by a standard small-group quote.
The one that matters most is coverage for people who live on the other side of a border. A United States group health plan does not follow an employee into Ontario in any useful way, and a cross-border payroll needs that settled deliberately rather than discovered at a claim.
Two Hospitals in a City of Twenty-Nine Thousand
McLaren Port Huron and Lake Huron Medical Center both operate here, which is unusual density for a city this size and genuinely useful leverage. Where two systems compete, a tiered network can move real money without cutting anyone off from care.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
It only works if you look at the claims first. Both hospitals have loyal patient populations in this county, and tiering the one your employees actually use into the expensive tier turns a cost saving into an employee-relations problem.
Four Ways to Fund a Plan Next to Two Competing Hospitals
Fully Insured, for Thin Claims Histories
Fixed rate, no claims exposure. For a smaller employer or one with a thin claims history this is often the right answer and we will say so.
Level-Funded for a Healthy Port Huron Group
If your people are healthier than the pool, level funding stops you paying for everyone else, at a fixed monthly cost with a chance of money back. Expect underwriting.
Self-Funding With a Stop-Loss Backstop
Realistic from roughly a hundred lives with stable experience. Attachment points and the handling of a known large claimant matter more than the administration fee.
Tiering McLaren and Lake Huron Medical
With two competing hospitals in the city, a tiered design can save meaningfully. Map your claims to facilities before you price it, not after.
Compliance That Trips Up Border Employers
Who Counts Toward the 50-Employee Line
Full-time equivalents across commonly owned entities decide the employer mandate. Operations on both sides of the county count together if commonly owned.
Affordability for the Lowest-Paid Full-Timer
The lowest-cost self-only option must stay under the annual percentage of the lowest-paid full-time employee’s wage.
Cross-Border Employees
Where an employee lives outside the United States, network access has to be addressed directly. Assuming a domestic plan travels is the common and expensive error.
When the 5500 Filing Kicks In
Once the plan reaches a hundred participants, a Form 5500 with Schedule A has to be filed, and that assumes the wrap document and summary plan description are already in place.
Border-City Questions We Answer Often
We have employees living in Sarnia. What covers them?
Not a standard domestic group plan, at least not usefully. That situation needs to be designed for rather than assumed away, and it is much cheaper to solve before a claim than after one.
Can we tier the two hospitals?
Often yes, and the saving can be real. The prerequisite is knowing which of the two your employees actually use, which your claims data will tell you.
A County Seat, Two Hospitals and a Returning Paper Mill
Port Huron had 28,983 residents at the 2020 census and is the seat of St. Clair County. McLaren Port Huron, a 186-bed acute-care hospital and Level III trauma center on Pine Grove Avenue, is the largest employer in the city with around thirteen hundred people. Port Huron Area School District employs roughly nine hundred and fifty, St. Clair County government around nine hundred and twenty, and St. Clair County Community Mental Health close to four hundred and eighty. Lake Huron Medical Center, now part of Prime Healthcare, adds about a hundred and forty acute-care beds. The Legacy Port Huron Paper Company is reviving the former Domtar mill with a $24.5 million investment and more than eighty new jobs. Several large automotive suppliers often listed as Port Huron employers — Motherson, ZF Axle Drives — are actually in neighboring Marysville.
Check Which City an Employer Is In
County-level employer lists routinely place Marysville plants in Port Huron. If you are benchmarking against a local competitor, confirm where they actually sit.
The Bridge Is an Employment Fact
One of the busiest commercial crossings on the border runs through this city. Logistics and customs-adjacent work brings variable hours and cross-border residency with it.
Papermaking Is Coming Back
Eighty-plus jobs at $27 an hour at the former Domtar site is a meaningful addition in a city this size, and a new payroll standing up needs plan documents before it needs a quote.
More Port Huron Questions, Answered
Does CFH take on Port Huron and St. Clair County clients?
We do. We advise Port Huron employers on plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers and, for proper coverage of an account, we work in teams of five. Most relationships begin with a look at your current plan and renewal.
Which hospitals do Port Huron employees use?
Two acute-care hospitals operate in the city: McLaren Port Huron, with 186 licensed beds and a Level III trauma center, and Lake Huron Medical Center, with roughly 140 beds, now part of Prime Healthcare. Having two competing systems in a city this size gives employers more network and tiering options than most small markets offer.
We already have a broker. Is a second look worth it?
Usually, yes. A second opinion on the renewal costs nothing and changes nothing unless you decide it should. We will tell you what the increase is made of and whether the market can beat it; if your plan is priced correctly, we will say so.
Cross-border staff and a broker who has never raised it? See how moving to CFH works.
Send the Renewal, We Will Unpack It
Send us the renewal letter, your current plan summary, the employer contribution by tier and enrollment by tier, plus two more documents once you pass fifty, and we will break the number into its parts. Reach us at 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
