
You Cannot Simply Give the Owners a Better Plan
On a self-funded or level-funded medical plan, non-discrimination testing applies. If the arrangement favors highly compensated participants in eligibility or in benefits, the consequence falls on those individuals as a taxable event rather than on the plan as a filing problem. That is a materially worse outcome than most people assume, and it lands on precisely the people the arrangement was meant to benefit.
Insured medical plans sit differently, which is one reason a closely held firm sometimes stays insured longer than the arithmetic alone would suggest. It is worth knowing which regime you are in before designing anything.
What Can Legitimately Be Differentiated
Classes Built on Genuine
consistently applied grounds — salaried against hourly, or by location — rather than by name
Contribution Levels That Vary by Class
provided the classes themselves stand up
Supplemental Disability Cover for Higher Earners
whose group income protection often replaces a much smaller share of actual pay than they expect
Life Cover Above the Group Maximum
arranged individually where the group schedule stops short
The Disability Gap Is the One Owners Miss
A standard group income protection schedule replaces a percentage of salary up to a monthly cap. For a partner or senior professional, that cap can mean the effective replacement rate is a fraction of what the schedule appears to promise. Nobody discovers this at the point of purchase; they discover it at the point of claim. It is straightforwardly fixable in advance and almost never looked at.
Rules That Apply Across the Firm
Continuation Coverage Starting at Twenty Employees
with no Michigan provision beneath that threshold
Medical non-discrimination testing on any self-funded or level-funded arrangement
including designs that feel insured
The offer-of-coverage duty at fifty full-time equivalents averaged across the prior year
aggregated across related entities
Medicare-Eligible Partners and Staff Need The
Medicare-eligible partners and staff need the creditable-coverage notice before mid-October
Questions From Macomb County Firms
Can we pay the full premium for partners and half for staff?
Sometimes, depending on how the classes are constructed and whether the plan is insured or self-funded. It is a design question with a real answer, not a matter of preference.
Is our income protection actually adequate for the principals?
Check the monthly maximum against their actual pay. In our experience this is the most common and most consequential gap in a professional firm’s program.
County Seat, Trauma Center and Defense Corridor
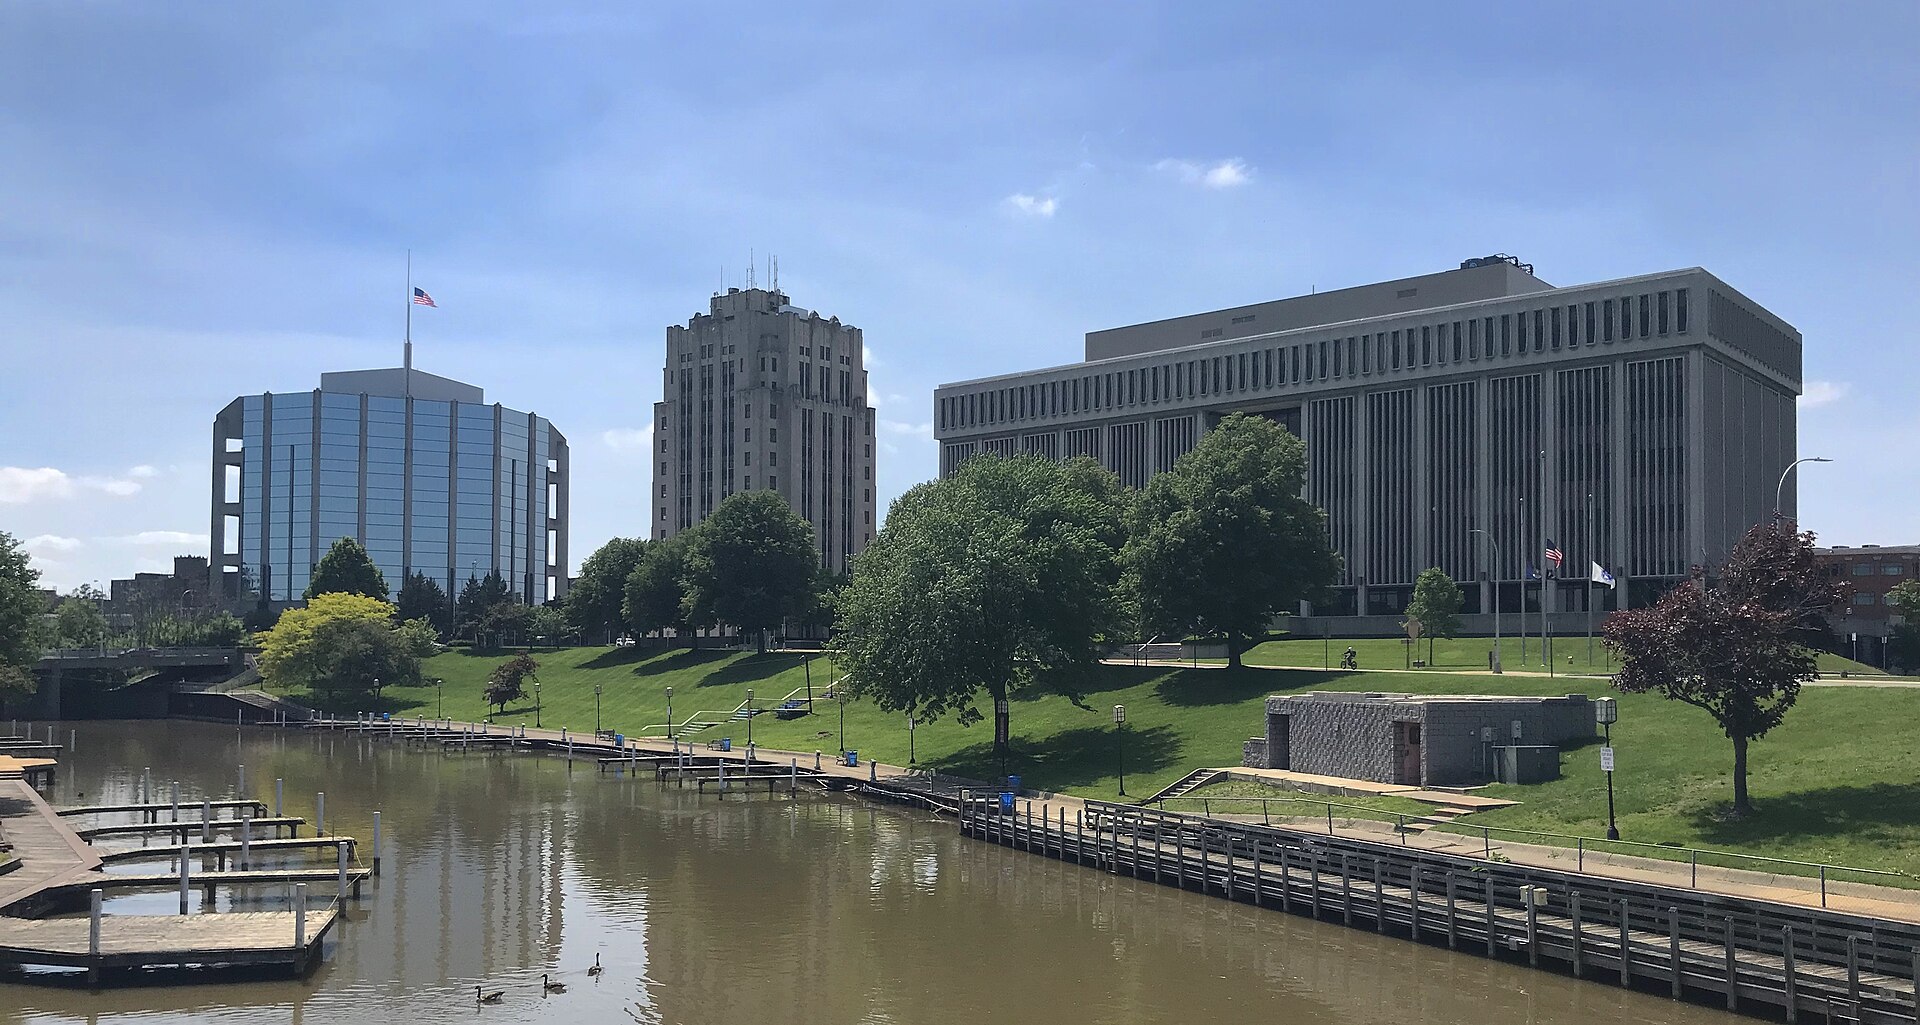
Mount Clemens is the county seat of Macomb County, a city of 15,697 people (2020 census) on the Clinton River about 20 miles northeast of downtown Detroit. Macomb County government runs its administration from downtown, and McLaren Macomb, a 288-bed hospital with nearly 2,000 employees and a Level II trauma center, is one of the city’s largest employers. Selfridge Air National Guard Base sits just to the north. Countywide, the biggest employers include General Motors, Stellantis, Ford, the federal government, Henry Ford Health and McLaren, with a strong aerospace and defense cluster. That mix of public, health care and manufacturing jobs means local employers compete with large, benefits-rich organizations for workers.
Benchmark Against Big Employers
Your applicants can compare your offer with packages from automakers, hospitals and county government. We benchmark deductibles, employee contributions and dental and vision coverage against what similar Macomb County employers provide, so you know where your plan stands before you set next year’s budget. We also point out which gaps cost the most to close.
Check Hospital Access Closely
Mount Clemens sits beside McLaren Macomb, with other major systems nearby across the county. Networks can include one system and not another. We check which hospitals, trauma services and specialists each plan covers, and we explain the tradeoff between a narrower network price and your employees’ current doctors.
Plan for Shift and Hourly Staff
Health care, retail and manufacturing jobs around Mount Clemens often run on shifts with varied hours. We explain how ACA measurement periods and eligibility rules apply to variable-hour staff, and we help you set waiting periods and classes you can administer consistently. We also explain what the penalties look like if an eligible employee is missed.
Compare Funding Beyond Fully Insured
Small and midsize employers in the county seat often accept renewals without seeing alternatives. We compare fully insured quotes with level-funded plans for healthier groups and ICHRA for employers that want a fixed budget, and we explain the compliance steps that come with each option. You see the numbers before deciding.
Let Us Read the Schedules
Send the renewal letter, plan summary, contribution split and enrollment by tier, plus two more documents at fifty and above and your disability and life schedules, and we will show what the number is made of. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Partners underinsured for disability and nobody checked? See what moving to CFH involves.
Related: how we help employers improve workforce health and control healthcare costs all year, not just at renewal.
