
Leave, Disability and Continuation Are Three Different Systems
An employee off for an extended period may be exercising a job-protected leave right, drawing on short-term income protection, and approaching a point where their coverage status changes. Those three run on different rules, different clocks and different definitions, and they are administered by different parties who do not talk to each other.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
The employer is the only participant with a view of all three. When something goes wrong it is almost never because one system failed; it is because nobody was holding the sequence.
The Sequence Worth Writing Down
Establish whether the absence is job-protected and for how long
since that determines whether coverage must continue on the same terms
Confirm How the Employee’s Share Of
Confirm how the employee’s share of premium is collected while they are not drawing a full wage, which is the most commonly neglected step
Track the Point at Which Protected Leave Ends
because that is frequently the event that changes coverage status
Coordinate the Income Protection Claim
which has its own elimination period and its own definition of disability
Only then consider whether a continuation right has been triggered
and start those clocks properly
Premium Collection Is Where It Usually Breaks
An employee on unpaid leave still owes their share. If nobody arranges how that is paid, arrears accumulate quietly and the employer is left choosing between absorbing the cost and terminating coverage for non-payment on someone who is unwell. Agreeing the method in writing at the start of the leave takes ten minutes and prevents the whole situation.
Points That Apply Alongside
Reduced Hours Can Start Continuation Rights
in the same way a termination does
Continuation Coverage at Twenty Employees
Michigan adds no rule below the federal threshold.
Long-term income protection replaces a percentage of pay up to a monthly maximum
which higher earners frequently exceed
The Creditable-Coverage Notice for Older Employees
Medicare-eligible employees need the creditable-coverage notice each year before the middle of October
Questions From Grosse Pointe Employers
Must we keep someone on the plan while they are on leave?
During job-protected leave, generally yes, on the same terms as if they were working. After it ends the answer depends on your plan document and on whether hours fell below the eligibility threshold.
What if they stop paying their share?
There is a process, and it involves notice rather than a silent termination. Handle it deliberately; this is an area where informality creates liability.
Schools, Shops and Healthcare on the East Side
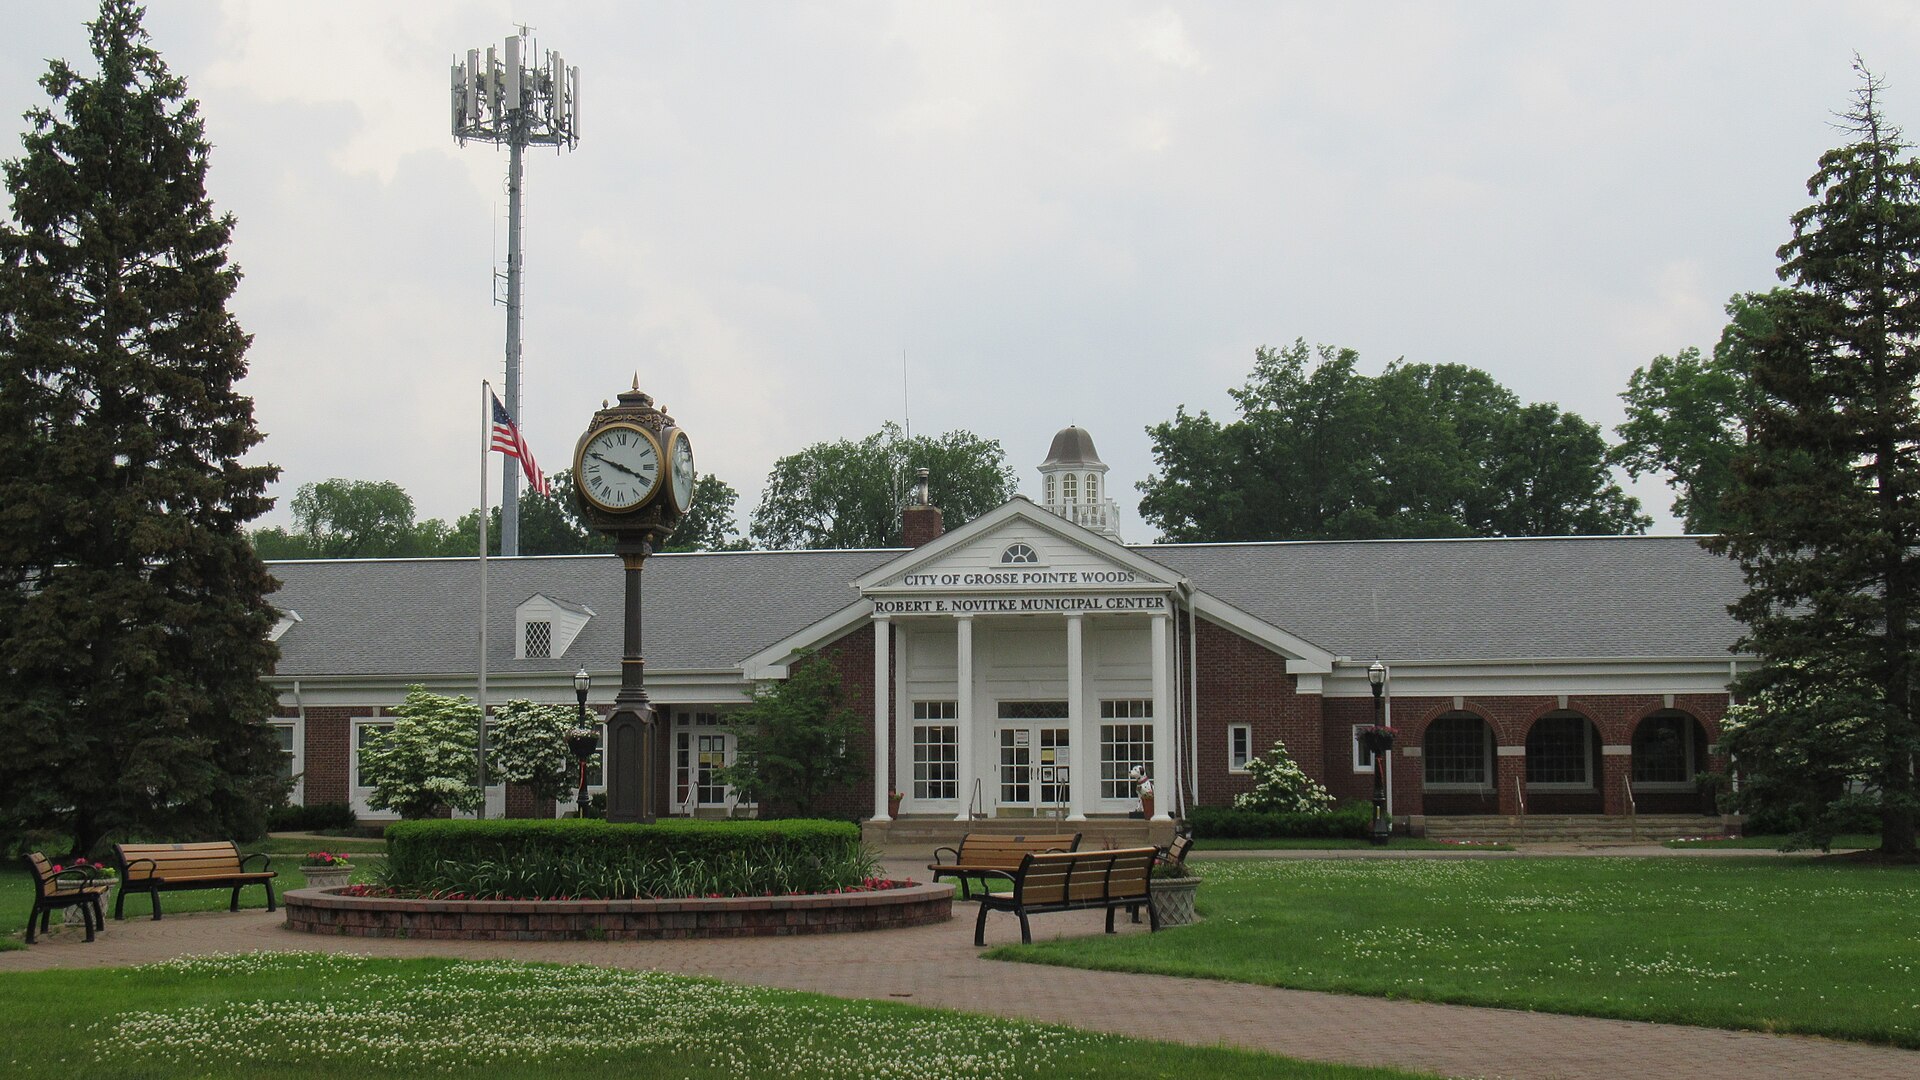
Grosse Pointe Woods is a Wayne County city of 16,487 residents (2020 census) and the only one of the five Grosse Pointes without Lake St. Clair shoreline, though it owns a lakefront park in neighboring St. Clair Shores. The Grosse Pointe Public School System is headquartered here and operates Grosse Pointe North High School, Parcells Middle School and several elementary schools; the district reported about 872 full-time-equivalent staff across its schools in 2023-24. Henry Ford St. John Hospital, a 641-bed Level I trauma center, is nearby on Moross Road in Detroit. Beyond schools and healthcare, local employers are mostly small retailers, restaurants and professional offices, which makes small-group pricing and network fit the main benefits questions here.
Confirm East Side Hospital Access
Many Grosse Pointe Woods families rely on Henry Ford St. John Hospital and Corewell Health Beaumont Grosse Pointe Hospital. We check that both systems and the primary care doctors your employees already see are in network, so a plan change does not force people to switch physicians.
Manage Small-Group Renewal Swings
A dental practice or boutique with eight employees can see its renewal jump after one serious claim. We review renewals line by line, compare carriers, and explain plan design changes and funding options before you accept an increase or pass higher costs to staff. We also show how employee contributions would change.
Offer ICHRA to Very Small Teams
Small offices may struggle to meet group participation rules when employees are covered through a spouse. We compare traditional small group coverage with an individual coverage HRA, which gives each employee a set monthly allowance toward an individual plan of their choice. We explain the setup and compliance steps as well.
Build Out Dental, Vision and Life
Professional and retail staff often weigh the whole package, not just medical. We compare employer-paid and voluntary dental, vision, group life and disability coverage so a small employer can round out benefits and stay competitive with larger East Side employers for good hires. Voluntary options add value at low cost.
Grosse Pointe Woods Business Owners Ask Us
Does CFH work with employers based in Grosse Pointe Woods?
Yes. We work with Grosse Pointe Woods employers on plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers who review cost, plan performance, risk and administration together, and we normally start with your current plan and renewal.
An employee on leave and no one sure who is collecting the premium? See how a switch to CFH works.
Bring Us the Plan Document and the Renewal
Send the renewal letter, plan summary, contribution split and enrollment by tier, plus two more documents at fifty or above and your plan document, and we will map how leave and coverage fit. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
