
The Schedule Promises a Percentage. The Cap Decides the Reality.
Group income protection typically replaces around sixty percent of salary, up to a stated monthly maximum. Most employees read the percentage and stop. For anyone whose earnings put them above the cap, the effective replacement rate is lower — sometimes far lower — and they will not discover that until the month they need it.
It is worth doing the arithmetic for your own highest earners rather than assuming the schedule is adequate because it was adequate when it was written. Pay has moved; monthly maximums frequently have not.
Short Term and Long Term Are Different Products
Short-Term Cover Starts After a Brief
Short-term cover starts after a brief elimination period and runs for a defined number of weeks
Long-term cover begins where the short-term ends and can continue for years
which makes the definition of disability in the contract the most important sentence in it
That definition varies: some contracts pay if you cannot do your own occupation
others only if you cannot do any occupation you are reasonably suited to, and the difference is enormous for a skilled trade
A Gap Between the End Of
A gap between the end of one and the start of the other leaves the employee with nothing during it, and gaps do occur
Who pays the premium decides whether the benefit is taxable when it is received
which changes the real replacement rate again
That Last Point Is Worth Slowing Down On
If the employer pays the premium and takes the deduction, the benefit is generally taxable to the employee when paid. If the employee pays with after-tax dollars, it generally is not. Sixty percent taxable and sixty percent tax-free are materially different outcomes, and the choice is available at the design stage rather than at the claim.
Rules That Sit Beside Income Protection
An employee on income protection may also be on job
protected leave and approaching a change in coverage status — three systems, three clocks
Continuation Coverage From Twenty Employees
Michigan has no requirement below it.
Life Cover Above a Certain Employer
paid amount creates a taxable benefit as well
A reduction in hours can itself trigger continuation rights
independently of any disability claim
Income Protection Questions From Wayne Employers
Is our long-term cover adequate?
Check the monthly maximum against your actual highest salaries, then check the definition of disability. Those two answers tell you nearly everything.
Should employees pay the premium themselves?
Often worth structuring that way for the tax treatment at claim. It should be a deliberate choice rather than whatever was set up originally.
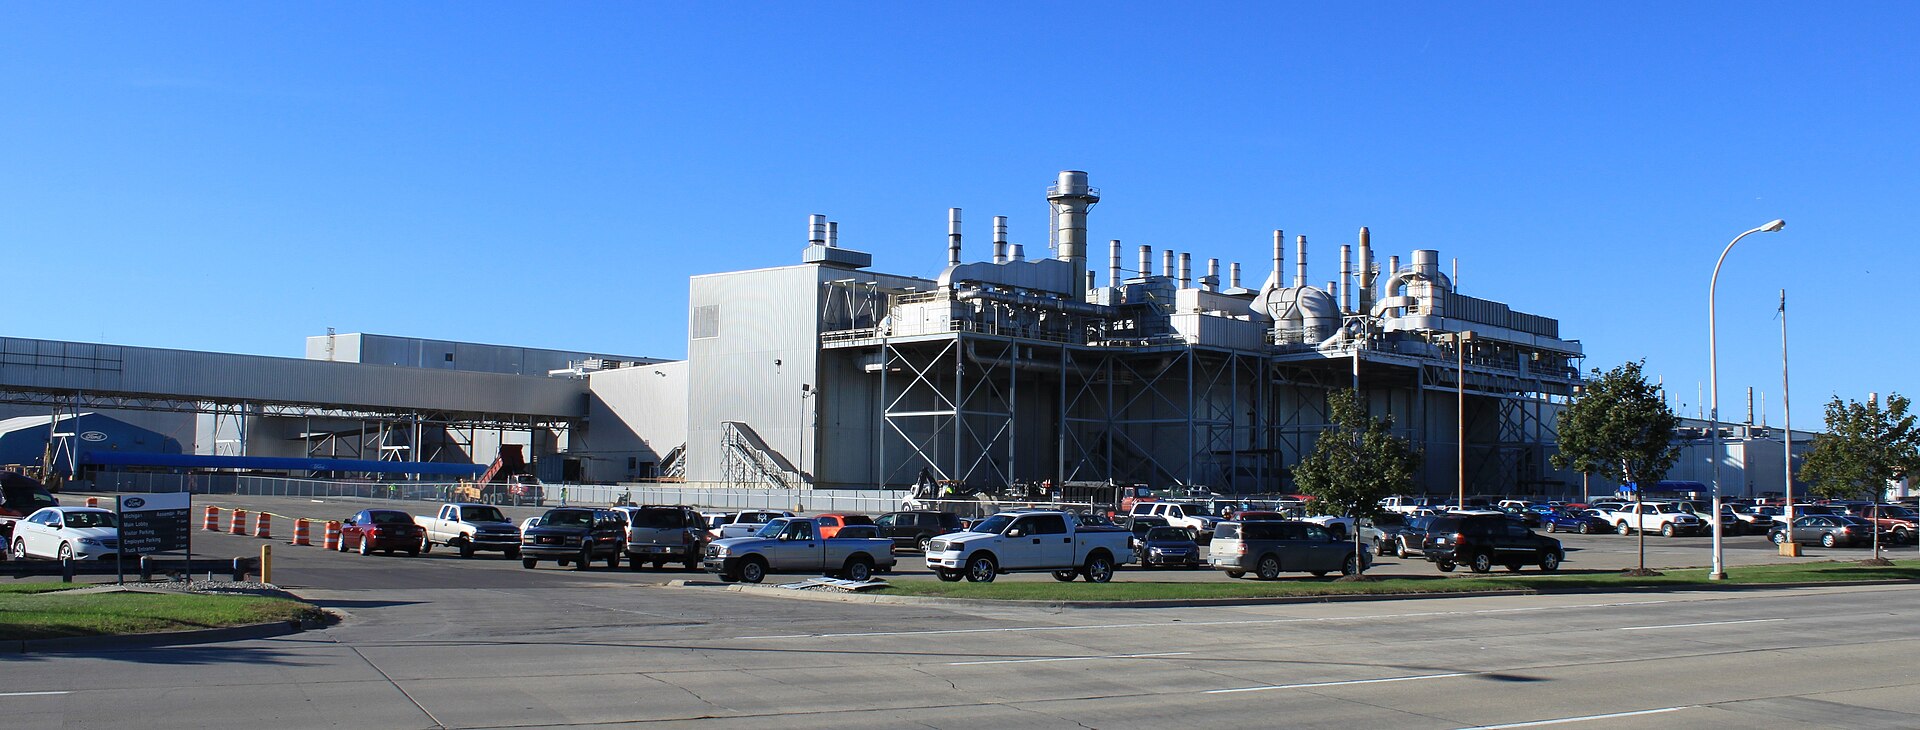
Where Ford Builds Broncos and Rangers
Wayne is a western Wayne County suburb of 17,713 residents (2020 census), about 18 miles southwest of downtown Detroit along Michigan Avenue. Ford Motor Company runs the Michigan Assembly Plant and Wayne Stamping & Assembly here; CBS News reported roughly 3,300 workers at the plant, which builds the Bronco and Ranger. Corewell Health Wayne Hospital, formerly Beaumont Wayne, also operates in the city. The area’s manufacturing history runs deep, from carriages and sleighs to aircraft and trucks. Around that anchor sit suppliers, logistics firms, contractors and service businesses whose workers often live across Downriver and western Wayne County. For those employers, benefits need to fit shift work, physical jobs and a workforce that compares offers against union-scale auto benefits.
Match Plans to Shift Schedules
Suppliers and service firms near the Ford plants often run multiple shifts and variable hours. We explain how ACA measurement and waiting periods apply to variable-hour staff, and help set eligibility rules that are simple to administer and easy for supervisors to explain on the floor.
Add Disability and Life Coverage
Stamping, assembly, logistics and trades work is physical, and an injury off the job can stop a paycheck. We compare group short-term and long-term disability and basic life options, including employer-paid and voluntary versions, so workers have income protection at a cost the business can sustain.
Check Local Hospital Access
Corewell Health Wayne Hospital sits in the city, and employees also use other Metro Detroit systems. We check that the hospitals and doctors your people rely on are in-network, and compare broad and narrow network options so savings do not come at the expense of nearby access.
Compete for Skilled Hourly Workers
Local employers recruit against auto jobs with strong benefits. We benchmark contributions and deductibles for your industry, then model cost-sharing tiers that keep take-home pay reasonable for hourly workers while holding the employer’s total spend within budget. We also review how dental, vision and voluntary benefits can round out the package for workers and their families.
Send Us the Schedules
Send the renewal letter, plan summary, contribution split and enrollment by tier, plus two more documents at fifty or above and your disability schedules, and we will show what the number is made of. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Disability caps nobody has checked since the schedule was written? See how switching to CFH works.
See also: Improving Health. Controlling Costs. Delivering Results., our approach for employers who want cost to move between renewals.
