
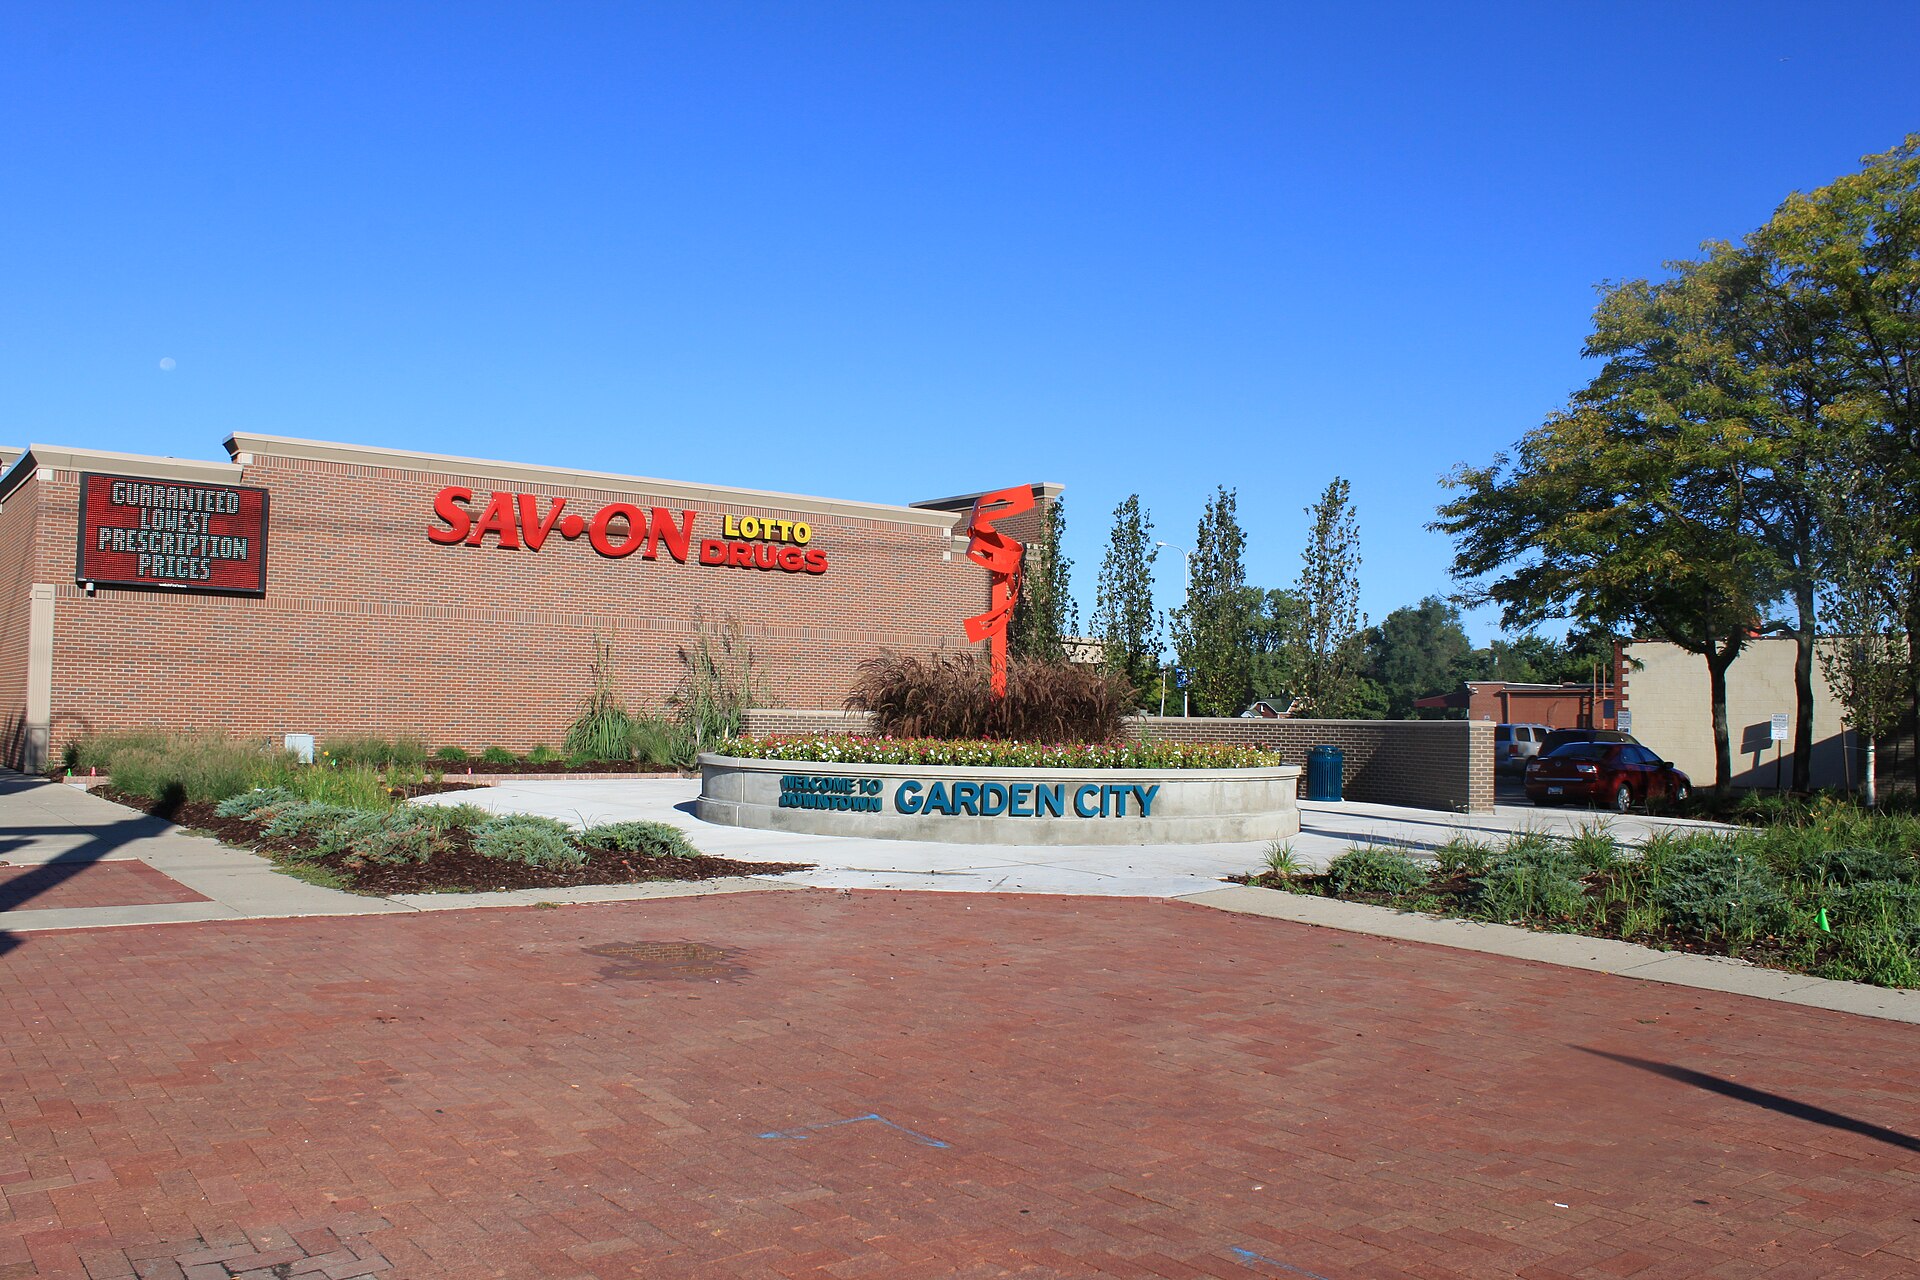
A City That Finished High School and Went to Work
Two Garden City figures sit oddly together until you see what they mean. More than ninety-one percent of adults here hold a high school diploma, which is above the state average. Around fifteen percent hold a bachelor’s degree, which is well below it. Almost everybody finished school and comparatively few went on to college.
See also: Improving Health. Controlling Costs. Delivering Results., our approach for employers who want cost to move between renewals.
The rest of the profile follows from that. Nearly eighty percent of households own their home, the average household holds fewer than two and a half people, the median household income is a little over sixty-seven thousand dollars, and the typical commute runs close to twenty-seven minutes. Six percent of residents under sixty-five are uninsured. This is a settled town of skilled trades, service work and manufacturing, where people own houses, drive to jobs in neighboring communities, and earn their living with their hands.
That has a specific consequence for benefits planning, and it is one most employers here have never had put to them directly. In a workforce that earns its income physically, the risk that actually bankrupts a household is not a medical bill. It is the loss of a paycheck.
The Benefit Most Employers Here Do Not Offer
Ask an employer in Garden City what happens if a machinist, a plumber or a delivery driver cannot work for four months, and the usual answer is workers’ compensation. That answer is right only if the injury happened at work.
Workers’ compensation covers occupational injury and illness. It does nothing for the herniated disc from lifting something at home, the knee that needs reconstructing after a weekend, the cancer diagnosis, the pregnancy complication, the heart attack. Those are the majority of events that keep a working adult out of work for months, and a great many employers have no coverage for any of them.
What fills that gap is disability insurance, and it is the most commonly missing line in a small-group package in this part of Wayne County. It is also, relative to what it does, inexpensive. A short-term disability plan for a small employer typically costs a fraction of what the same employer spends on dental, and dental is rarely the thing that decides whether a family keeps its house.
Short Term, Long Term, and the Gap Between Them
Disability coverage comes in two pieces that are meant to hand off to one another, and the handoff is where badly assembled packages fail.
A short-term policy begins after an elimination period, commonly a week or two for illness and sometimes immediately for accident, and pays for a limited stretch, often thirteen or twenty-six weeks. A long-term policy begins after its own elimination period, commonly ninety or a hundred and eighty days, and can run for years. Both typically replace around sixty percent of income, and both usually cap the monthly benefit at a figure that matters more to higher earners than the percentage does.
The failure mode is simple arithmetic. If the short-term plan pays for thirteen weeks and the long-term plan does not start until day one hundred and eighty, there is a gap of roughly two months in which a disabled employee receives nothing at all, at exactly the point when savings have already been spent. Nobody designs that deliberately. It happens when the two policies are bought in different years from different carriers and never laid side by side. We check the two elimination periods against each other before anything is signed, because it is a five-minute check that prevents the worst phone call an HR manager ever takes.
The Tax Question Almost Nobody Asks
Here is a detail that changes the value of a disability benefit by roughly a third and is almost never explained at enrollment.
If the employer pays the premium and does not include it in the employee’s taxable income, the benefit is taxable when it is paid. A policy replacing sixty percent of income then delivers something closer to forty-five percent after tax, at a moment when the household needs every dollar. If the employee pays the premium with post-tax money, the benefit arrives tax-free, and that same sixty percent is a genuine sixty percent.
Neither arrangement is automatically right. An employer-paid plan gets everyone covered, which matters most in a workforce where voluntary take-up would be low. An employee-paid plan delivers far more when it is actually needed. There is also a middle route in which the employer pays the premium but reports it as income, so the employee bears a small tax now and receives the benefit tax-free later, which is usually the best value of the three and is offered least often. The decision should be made deliberately rather than inherited from whatever the first policy happened to do.
The Medical Plan Carries the Same Risk
A physically worked body shows up on the health plan long before it shows up on a disability claim, and the line items that matter are ones employers rarely look at when comparing quotes.
Physical therapy is the clearest. Many plans cap it at a set number of visits per year, and the cap is often lower than a course of treatment for a back or a shoulder actually requires. An employee who runs out of covered visits in week six either pays out of pocket or stops, and stopping is how a treatable injury becomes a surgical one. Imaging is the second. Plans differ considerably in whether advanced imaging sits under the deductible, carries a separate copay, or requires prior authorization that adds a fortnight before anyone knows what is wrong.
Occupational therapy, chiropractic coverage and the plan’s treatment of spine procedures all belong in the same review. None of these change the headline rate much. All of them determine whether the plan is useful to the people actually enrolled in it, which in Garden City means people whose work is physical and whose median age is on the older side of forty.
A Hospital in Town, Under Different Ownership
Garden City has something most cities its size do not, which is a general hospital inside its own boundaries. Garden City Hospital has been owned since 2014 by Prime Healthcare, a for-profit system based in California for which this was its first Michigan acquisition.
Ownership is not a quality judgment and should not be read as one. It is a network question. Independent and for-profit hospitals sit outside the big regional systems that dominate southeast Michigan, and their participation in any given carrier’s network, and the tier they land in, is negotiated separately and can change. A plan that covers the two large systems generously may or may not treat the hospital nine minutes from an employee’s house the same way.
For an employer here that is worth confirming rather than assuming, and confirming again when the carrier changes. The rest of the picture is the usual western Wayne County spread, with Trinity Health Livonia, the Corewell facilities in Farmington Hills and Dearborn, and the Henry Ford network all within a reasonable drive. Employees have options. The point is to know which ones the plan actually pays for before somebody finds out at the registration desk.
Where Garden City Residents Go to Work
Garden City Hospital is the anchor — an acute-care hospital owned by Prime Healthcare Services, a California-based for-profit system that bought it in 2014. That ownership matters more than most employers realise: Prime is not Corewell, Trinity or Henry Ford, so it contracts separately and can sit differently in a network than the big three systems do.
Garden City Public Schools (about 3,200 students across eight schools) and the City of Garden City round out the large local employers. Beyond those, this is a small-employer economy — trades, retail, professional practices — and a good number of residents work at Ford’s Michigan Assembly Plant in neighbouring Wayne.
Garden City is a small, ageing, moderate-income inner-ring suburb: about 26,300 residents, median household income $67,294, and 17% of residents aged 65 or older. That last number is the one we plan around, because Medicare coordination comes up here far earlier than it does in a younger workforce.
What Garden City Business Owners Ask
How do we get a second opinion on our Garden City renewal?
Send us the renewal, the current plan summary and a census. We will show what is driving the increase, what the market would offer a group like yours, and whether the plan design and funding arrangement still fit. Sometimes the answer is that the renewal is fair — we will tell you that too.
No coverage for four months without a paycheck? See how switching to CFH works.
Let Us Look at the Income Protection Side
Send the renewal letter, plan summary, contribution by tier and enrollment by tier, plus two more documents at fifty or above, and we will explain the increase and look at your disability coverage. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
