
Reducing Cost and Shifting Cost Are Different Actions
Raising a deductible lowers your premium because the plan expects to pay less, and the difference lands on whichever employees actually use care that year. Total spending across employer and employees barely moves; the split changes. That can be a perfectly reasonable decision, but it should be made knowing it is a redistribution rather than a saving.
Changes that genuinely reduce total cost work differently. They alter where care is delivered, what is paid for it, or whether it happens at all — steering to lower-cost settings, managing the prescription tiers, addressing an identified driver. Those are harder and slower, and they are the ones that still work the following year.
A Rough Guide to Which Is Which
Higher Deductible or Out-Of-Pocket Maximum
shifts cost to the employees who use care
Higher employee contribution — shifts cost to everyone enrolled
and suppresses take-up, which carries a rating penalty of its own
Narrower Network — Genuinely Reduces Cost
at the price of access, so test it against where your people live first
Prescription Tier Management — Frequently a Real Reduction
and the fastest-moving line in most plans
Changing carrier — can be a real reduction below the claims-release threshold
where your rate is drawn from the book rather than from you
The Question to Ask Before Any of It
Points to Confirm Alongside
When COBRA Starts to Apply
Michigan adds no requirement under it.
A High-Deductible Design Paired with A
A high-deductible design paired with a general-purpose flexible account disqualifies health savings contributions entirely
Dental and Vision Priced by Size Band
so those lines move for reasons unconnected to your claims
The Yearly Creditable-Coverage Notice
Employees eligible for Medicare need the creditable-coverage notice each year before mid-October
Cost Questions From Hazel Park Employers
Should we raise the deductible to hold the premium?
Sometimes, and go in knowing it moves cost onto the people who get ill rather than removing it. Pairing it with an employer contribution to a savings account is what makes it defensible.
Will a cheaper plan lower our renewal next year?
Below the claims-release threshold, not really. Your next renewal will still be built from the book rather than from your experience.
From Racetrack to Commerce Center Along I-75
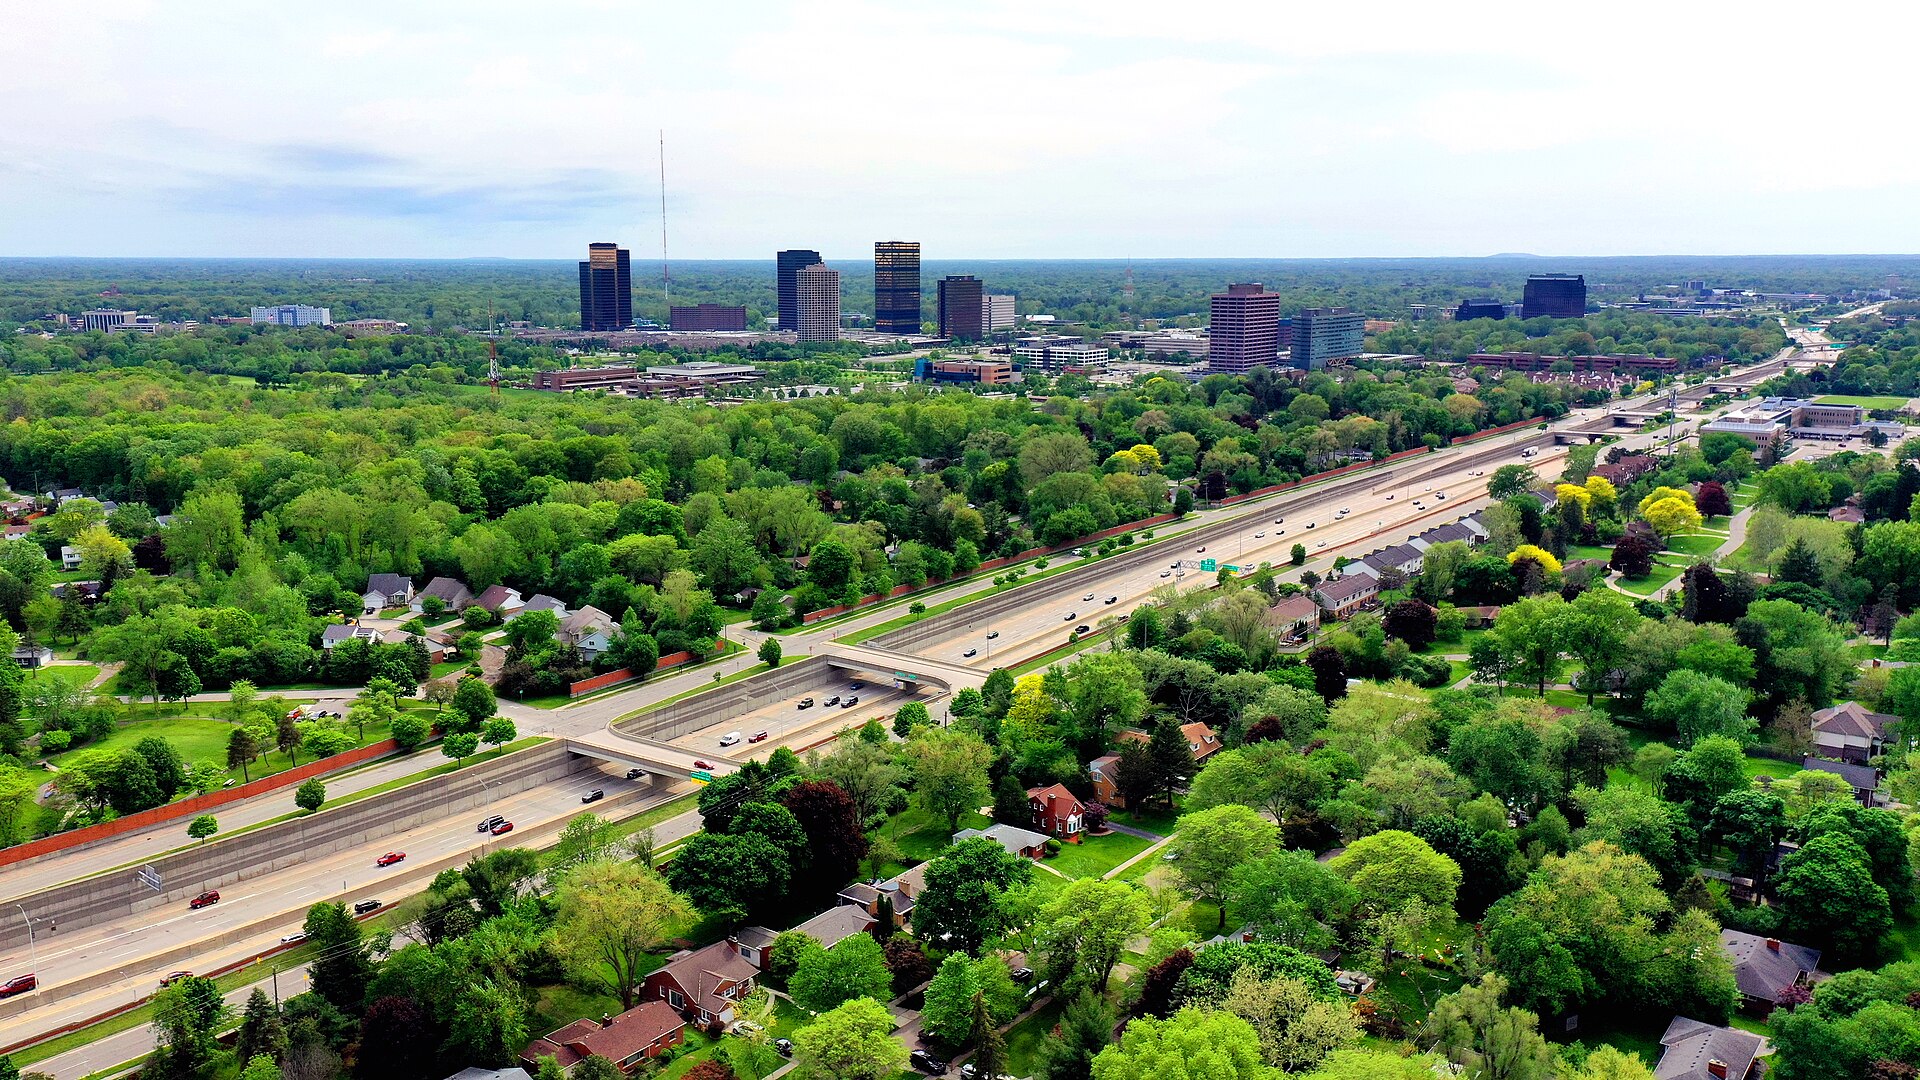
Hazel Park is an Oakland County inner-ring suburb about 10 miles north of downtown Detroit, with 14,983 residents in the 2020 census. For decades the Hazel Park Raceway anchored the local economy, and in the 1950s it supplied almost half of the city’s general fund. The track closed in 2018, and developer Ashley Capital turned the site into the Tri-County Commerce Center, whose tenants have included Amazon, LG Electronics and Bridgewater Auto Interiors. I-75 and I-696 run through or beside the city, so workers move easily in and out of Hazel Park every day. For local employers, a mix of warehouse, auto-supplier and small-business jobs means benefits have to fit shift schedules, hourly pay and a workforce that lives across the region.
Networks That Follow the Commute
Hazel Park workers often live in Macomb, Wayne or other parts of Oakland County. We check that each plan’s network includes the hospitals and primary care offices near where employees actually live, not just near the worksite, so a short I-75 commute does not turn into a long drive for care.
Eligibility Rules for Shift Work
Distribution and light manufacturing jobs often run multiple shifts with variable hours. We explain how waiting periods, measurement periods and full-time definitions work under the ACA so hourly staff are offered coverage on time and the employer avoids penalties when schedules shift from week to week.
Contributions Hourly Staff Can Afford
When wages are hourly, a high employee premium share can push people to waive coverage. We model employer contribution levels against ACA affordability thresholds and compare plan designs, such as a lower-deductible base plan with a buy-up option, so enrollment stays healthy and coverage is actually used.
Disability and Life for Physical Roles
Warehouse and assembly work is physical, and an off-the-job injury can keep someone out for weeks. We compare short-term and long-term disability options and basic group life so employees have income protection, and we explain how those benefits coordinate with any state or statutory programs.
Questions Hazel Park Employers Ask
How do we set benefits for a mix of warehouse and office staff?
We help you define eligibility classes that are consistent and compliant, explain ACA rules for variable-hour and shift workers, and compare plan designs that give full-time staff solid coverage without creating an administrative burden for part-time roles.
Which hospitals should a Hazel Park plan include?
Employees here use several Metro Detroit systems. We confirm the hospitals and physician groups your people rely on are in network before you choose a carrier or a narrower network.
Send Us the Renewal Before You Cut Anything
Send the renewal letter, plan summary, contribution split and enrollment by tier, plus two more documents at fifty or above, and we will show which changes cut cost and which just move it. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Told to raise the deductible and call it savings? See what switching to CFH involves.
See also: Improving Health. Controlling Costs. Delivering Results., our approach for employers who want cost to move between renewals.
