
You Become a Fiduciary by Deciding, Not by Being Appointed
Under federal law, fiduciary status attaches to whoever actually exercises discretion over the plan or its assets. Not to whoever holds the title. If you choose the carrier, set the contribution, decide who is eligible or determine how employee dollars are handled, you are a fiduciary in respect of those decisions whatever your business card says.
That is not a reason for alarm. It is a reason to be able to show how a decision was reached, because the standard applied is about process rather than outcome. A choice that turned out badly but was made carefully is defensible. A good outcome reached by never looking is not.
What a Defensible Process Looks Like at This Size
A Record of What Was Compared at Renewal
including the options you rejected and why
Documented Reasoning on Contribution Levels and Eligibility Rules
rather than an inherited arrangement nobody can explain
Evidence That Employee Contributions Were Forwarded Promptly
which is where the sharpest exposure sits
A Periodic Review of What The
A periodic review of what the plan costs to run and what is received for it
The Money Question Underneath It
Obligations That Sit Alongside It
An Annual Return for the Plan
due the last day of the seventh month after the plan year closes, with an extension available if requested before the original date
A Readable Plan Summary Handed to Every Participant
A plain-language summary distributed to participants nine months after the year ends
Continuation Coverage for Twenty or More
with no Michigan rule beneath that threshold
The Part D Notice Due Before Mid-October
whatever your size
Fiduciary Questions From Hillsdale County
Our office manager runs the plan. Is she personally exposed?
Potentially, in respect of the decisions she actually makes. This is a strong argument for writing down who decides what, and for making sure she is not deciding alone.
Does using a consultant transfer the responsibility?
It does not transfer it, but it does help you meet the process standard, because a documented comparison is exactly the evidence the standard is looking for.
College, Hospital and the Factories Along US-12
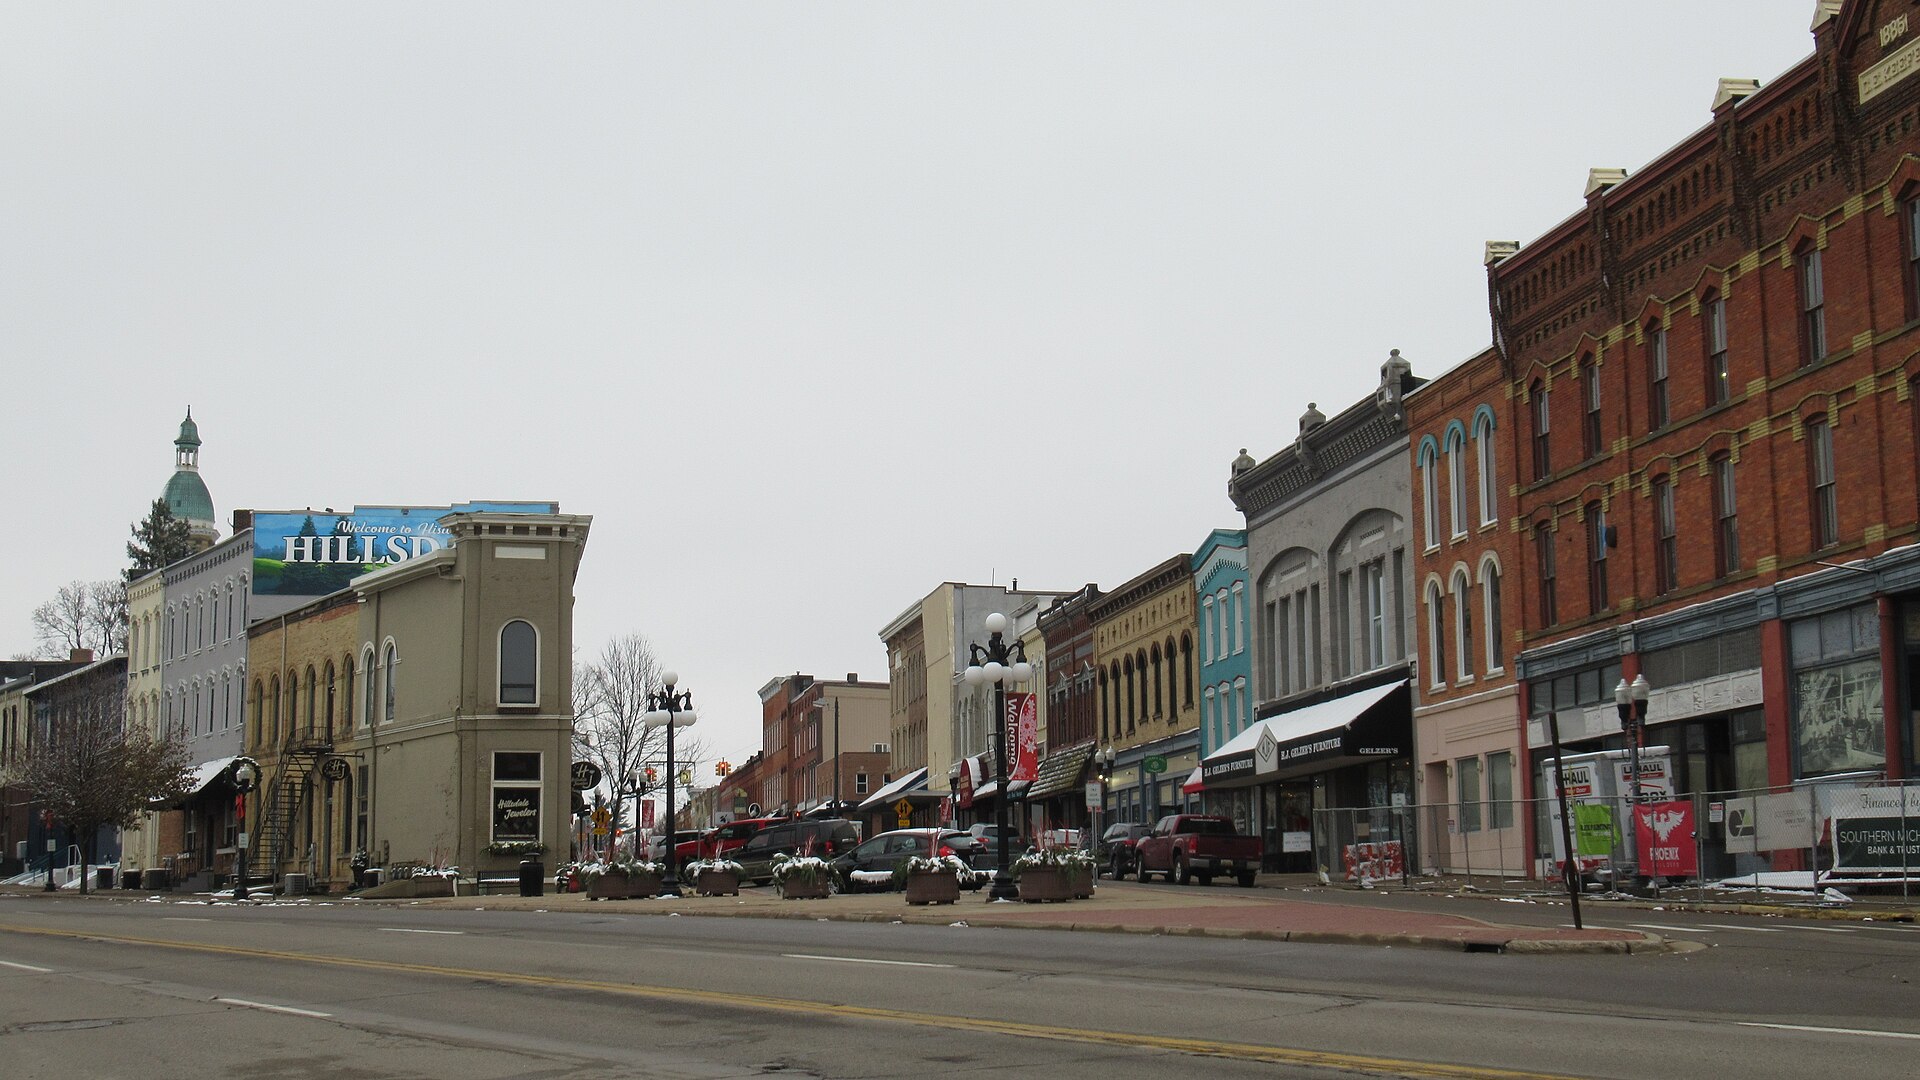
Hillsdale’s largest employers are Hillsdale Hospital, Hillsdale College and automotive parts makers such as Martinrea in nearby Jonesville. The city sits about 100 miles west of Detroit and 70 miles south of Lansing, and household incomes run below the national average, which puts a sharp edge on what employees pay out of pocket for coverage.
Employee Cost Share Matters More Here
Where household incomes are modest, a high deductible can stop people using the plan at all. We look at employee contributions and deductibles together, not just the total premium.
Networks That Reach Beyond the County
Employees expect Hillsdale Hospital in network, and many also use Jackson, Coldwater or Toledo-area providers. We check those before recommending a carrier.
Small Groups, Big Swings
Many Hillsdale County employers are small groups, where one large claim can move a renewal. We explain what drove the number and what options exist, including level-funded plans where they fit.
Plan Questions Hillsdale Employers Raise
Is a high-deductible plan a good fit for a Hillsdale workforce?
It can be, but only with care. Where take-home pay is tight, a large deductible can mean employees skip care they need. If you like the lower premium of an HSA-eligible plan, we usually pair it with an employer HSA deposit or a low-deductible alternative, so people have a real choice at open enrollment.
Do our employees have to use Hillsdale Hospital?
No, but most will want it in network. We check Hillsdale Hospital first, then the Jackson, Coldwater and Toledo-area providers your team already uses. If one carrier leaves out a provider several employees rely on, we show that before you choose, not after the first claim.
We only have a few employees. Can we still offer a group plan?
Yes. Michigan small-group plans are available to employers with as few as one eligible employee besides the owner, subject to carrier participation rules. For very small teams we also compare an ICHRA, which sets a fixed monthly allowance toward individual coverage.
What should we review before a Hillsdale renewal?
Look at more than the headline increase. We break the renewal into its parts, including rate change, age changes and any plan adjustments the carrier made, and compare it with at least one alternative. We also check whether a different contribution split could protect lower-paid employees from most of the increase.
Start With the Renewal and the File
Send the renewal letter, plan summary, contribution split and enrollment by tier, plus two further documents if you are at fifty or more, and we will go through the number and your decision file together. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Your office manager runs the plan and no one checks the process? Find out how switching to CFH works.
Related: how we help employers improve workforce health and control healthcare costs all year, not just at renewal.
