
The Work Happens Before the Number Exists
Rates for a January renewal generally land about sixty days out, which puts them in early November. If that is when the process starts, there is no time to gather documents, no time to test the market properly, no time to challenge anything and no time to communicate a change to employees before enrollment has to close.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
Run backwards from the renewal date instead, and the same work becomes unhurried.
A Working Calendar for a January Renewal
Around One Hundred and Twenty Days Out
in September: assemble the four documents — renewal letter from last year, current plan summary, contribution split by tier, enrolled counts by tier — and at fifty or above, the census and claims experience for the last three renewals
Ninety Days Out
October: decide whether this is a year to test the market, and if so, get the authorization signed so carriers can release information
Sixty Days Out, November: Rates Arrive,
Sixty days out, November: rates arrive, and the analysis begins against something rather than against nothing
Forty-Five Days Out: Decisions Made
alternatives requested in writing, credits asked for
Thirty Days Out
December: employee communication and enrollment, with time to answer questions
Renewal Date: Elections Reconciled Against The
Renewal date: elections reconciled against the carrier record before the first invoice
Two Clocks, and Only One Is Yours
The carrier’s clock is not under your control — rates arrive when they arrive. Your own clock is entirely under your control and starts the day the file is complete. Employers who confuse the two spend years believing the process is slow when what is actually happening is that it starts late.
Points Worth Having Settled in Advance
The Authorization Letter Releases Information Only;
The authorization letter releases information only; it does not change representation or move commission, and it applies at any size
At Fifty Enrolled and Above
carrier questions about claims and prior renewals are routine rather than exceptional
Continuation Coverage at Twenty and Above
with no Michigan requirement below that
The Medicare Prescription Notice Falls in Mid-October
which sits right inside this calendar
Renewal-Timing Questions From Saline Employers
How early is too early to start?
There is no such thing. The document-gathering step costs nothing and removes the only genuine bottleneck in the whole process.
Our rates always arrive late. Can anything be done?
Not about the arrival date. A great deal about what is ready when they do.
A Washtenaw Plant Town Near Ann Arbor
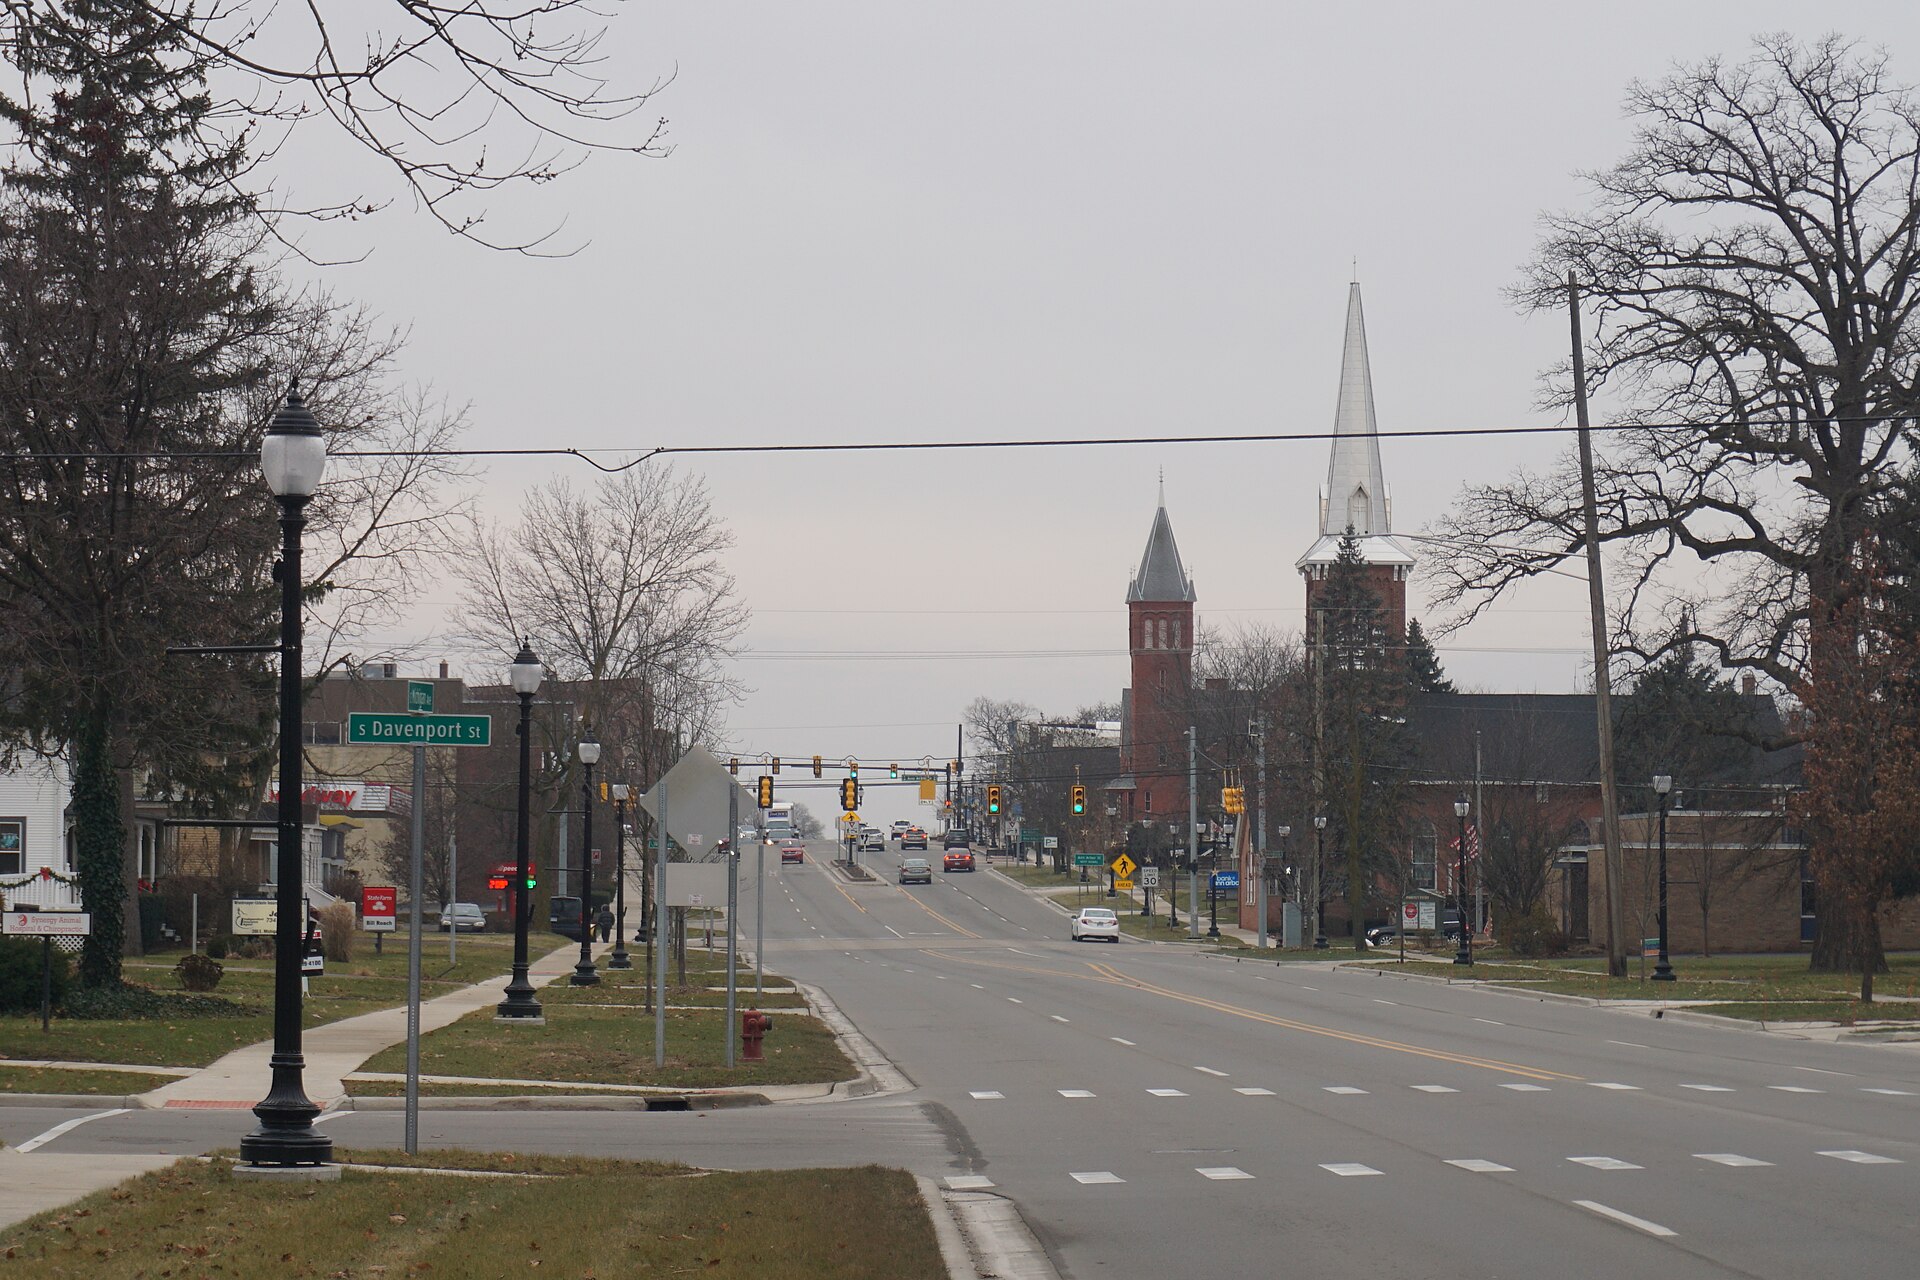
Saline is a Washtenaw County city of 8,948 residents at the 2020 census, set along the Saline River in the same county as Ann Arbor. Its best-known industrial employer is the plant on Maple Road that Ford opened in 1966 and French supplier Faurecia, now part of Forvia, took over in 2012. The plant makes automotive interior parts such as instrument panels, door panels and consoles, and its workers are represented by UAW Local 892. The Ann Arbor Railroad still serves the site with freight. Beyond the plant, Saline’s employers are largely small businesses and services, and many residents work elsewhere in Washtenaw County or the wider Detroit region. That means local employers often compete with large, well-funded benefit plans.
Check Ann Arbor Area Access
Saline employees are likely to use hospitals and specialists in the Ann Arbor area as well as closer clinics. We check that the systems your employees prefer are in-network on the plans you consider and explain any tiered network differences, so choosing a lower premium does not quietly cut off familiar doctors.
Compete With Union-Level Benefits
When a unionized auto plant and large regional employers are nearby, candidates notice benefit gaps. We compare your plan design and employer contribution against what local workers are used to seeing, and show where adding dental, vision or lower deductibles would make the biggest difference to recruiting.
Give Small Employers More Options
Many Saline businesses are small groups facing steep, unpredictable renewals. We explain ICHRA, level-funded plans and traditional small-group coverage in plain terms and compare total cost and employee experience, so you can decide which approach fits your budget, your headcount and the kind of coverage your employees expect.
Support a Commuting Workforce
Employees who live in Saline may work across Washtenaw, Wayne or Lenawee counties, and yours may commute in from those areas too. We look at where your people live and check that the network covers those communities, not just the ZIP code of your office, and flag any gaps before enrollment.
Saline Coverage Questions
Does CFH work with employers in Saline?
Yes. We advise Saline employers on plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers who look at the whole program (cost, plan performance, risk and administration), and our first step is normally your current plan and renewal.
Rates always land in November with no time left to act? See how switching to CFH works.
Start the Calendar Now
Send the renewal letter, plan summary, contribution split and enrollment counts by tier, and two more documents if you have fifty or more, and we will build the calendar backward from your date. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
