
A Young Payroll Uses Coverage Differently
Younger enrolled populations tend to produce low claims in ordinary years and occasional sharp ones — an accident, a pregnancy, a mental health course of treatment. That pattern points toward higher deductibles paired with a savings account rather than toward rich first-dollar coverage nobody draws on.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
It also points toward something employers here often get wrong. A savings account belongs to the employee and leaves with them. In a town where people arrive for a degree or a first job and move on within a few years, that portability is a genuine recruiting argument rather than a technicality.
But the Rate Still Does Not Reward You For It
Here is the part worth internalizing before you shop. Below roughly fifty enrolled subscribers, your medical rate is drawn overwhelmingly from the carrier’s book rather than from your own claims, and that book is built from index, age and geography. A young, low-claiming group does not get priced on its own good behavior at that size, because its own experience barely registers in the calculation.
That cuts both ways and it is worth saying plainly: a bad year cannot punish you either. What moves your number is which carrier you are with and what the state approved for that product, both of which are matters of public record.
Designs That Suit a Transient, Younger Workforce
High-Deductible Coverage Paired with a Savings
High-deductible coverage paired with a savings account the employee keeps when they move on
Health Maintenance Designs at a Low Employee Cost
which get taken up instead of declined
Telemedicine Access
disproportionately useful in a remote county with long drives to specialists
Employee-Paid Supplemental Products
cheap to add and genuinely valued by staff on early-career pay
Administrative Points That Bite in a University Town
Frequent Starts and Departures Mean Eligibility
Frequent starts and departures mean eligibility and continuation clocks running constantly rather than annually
Continuation Coverage Once Twenty Are Employed
Michigan does not add a smaller-group law under it.
Student, Seasonal and Part
time hours aggregate into the full-time-equivalent count that decides whether you owe an offer of coverage
Terminations Processed Late Can Become Permanent Losses
since some carriers refuse billing adjustments past a hundred and twenty days
Houghton Employers Ask About Young, Transient Staff
Our staff are young and healthy. Shouldn’t our rate reflect that?
Below fifty enrolled, no, and any broker suggesting otherwise is selling. Above it, increasingly yes, and that is when the conversation changes entirely.
Is a high-deductible plan fair on early-career wages?
It can be, if the employer funds a meaningful share of the savings account. Without that contribution it simply shifts cost onto the people least able to absorb it.
Michigan Tech and Copper Country Healthcare
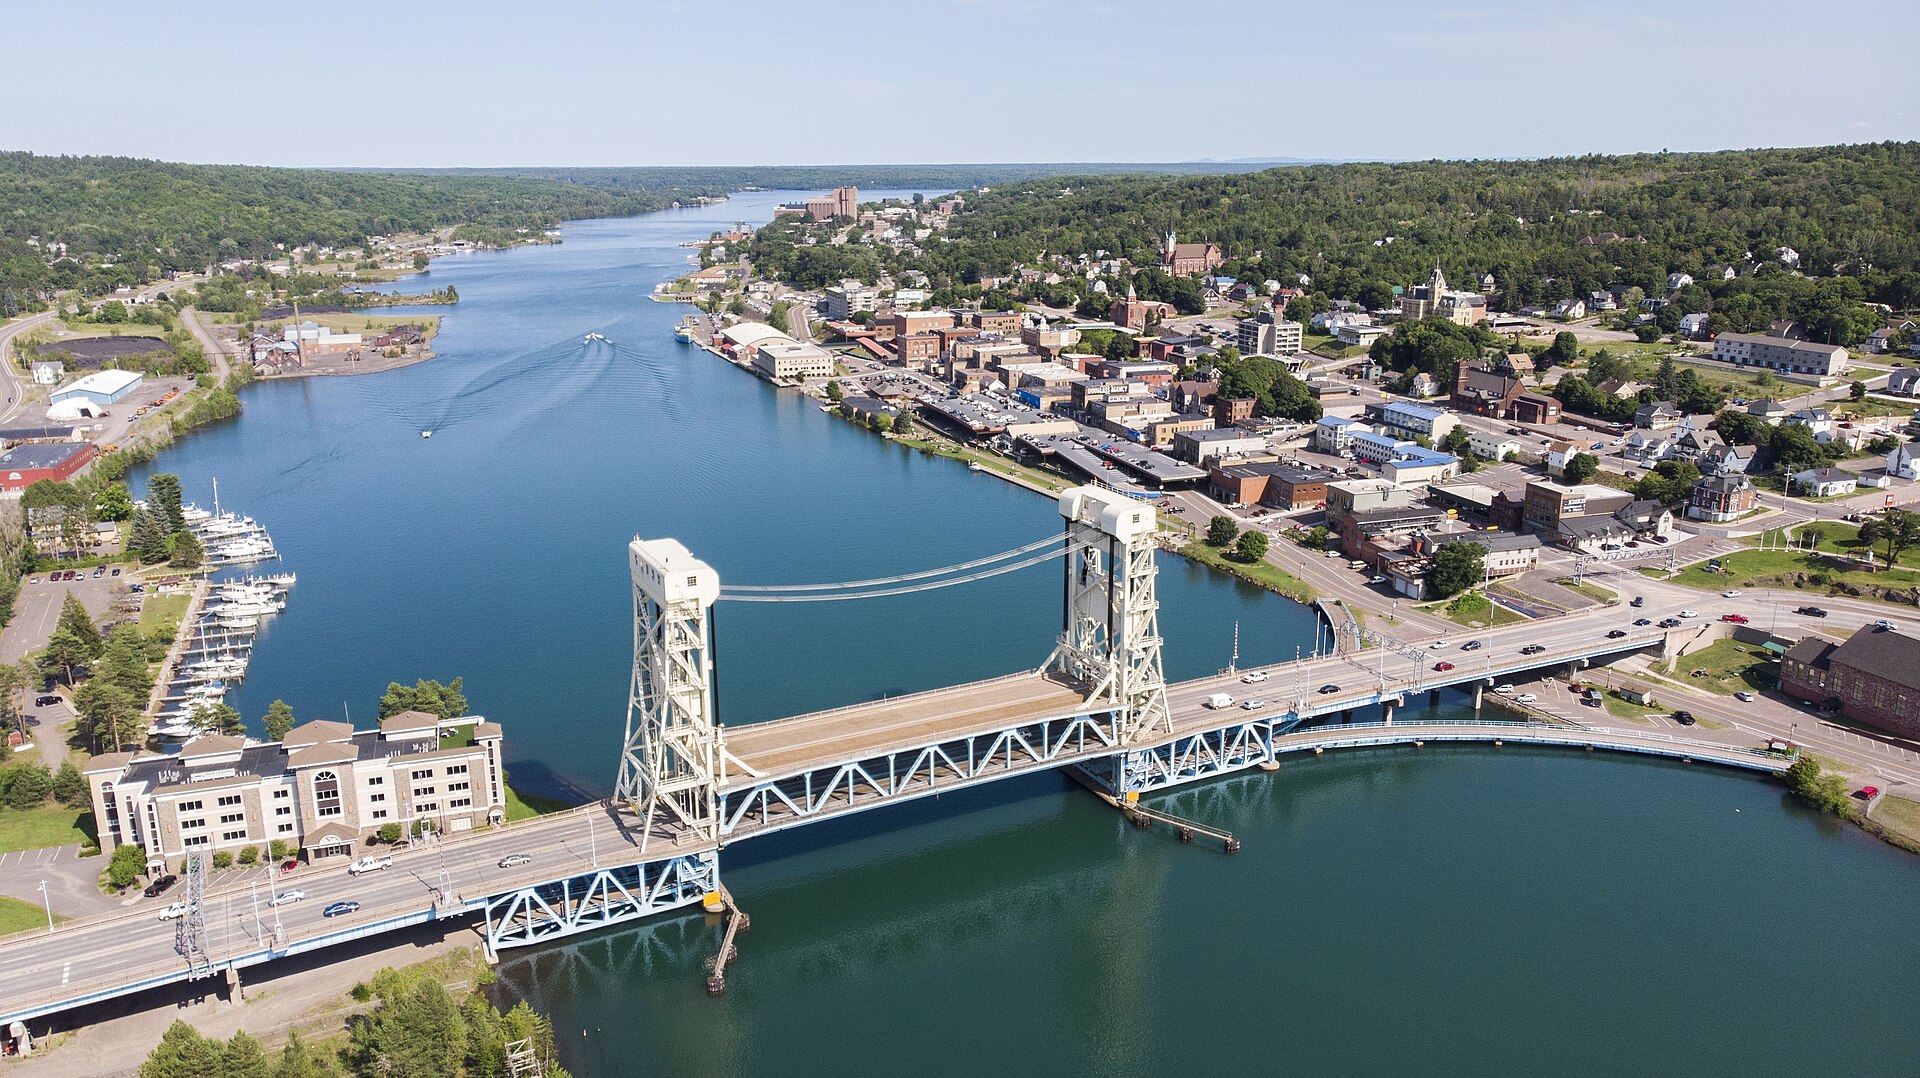
Houghton is the county seat and largest city of Houghton County, with 8,386 residents in the 2020 census, on the Keweenaw Waterway across from Hancock. Michigan Technological University, founded in 1885 as the Michigan College of Mines, has been the primary employer since the local mines closed. A 2016 county profile listed Michigan Tech at 1,630 employees, followed by Portage Health (now UP Health System-Portage in Hancock) and Aspirus Keweenaw, based in Laurium with a clinic in Houghton. Tourism draws summer visitors and winter snowmobilers to a city that averages about 218 inches of snow. Remote geography, limited provider choice and seasonal work shape how benefits should be built here.
Plan for Limited Local Provider Choice
The Keweenaw is served mainly by UP Health System-Portage and Aspirus Keweenaw, and specialty care can mean long drives. We check which local hospitals and clinics each carrier includes, and we look at how plans handle referrals and travel for care outside the region. We also note where a plan’s network thins out.
Handle Seasonal Tourism Staffing
Summer and winter tourism bring seasonal hiring swings. We explain how the ACA treats seasonal employees, how look-back measurement periods work for variable hours, and how to set waiting periods, so year-round staff are covered and short-term hires are handled consistently. Clear written rules help avoid disputes later.
Compete With University Benefits
Michigan Tech’s benefits set the local bar for professional and technical hires. We benchmark your contribution levels, deductibles and ancillary coverage against what candidates expect, and we compare options so a smaller engineering or service firm can make a credible offer. We also look at relocation-friendly features such as dependent coverage.
Use ICHRA for Small Keweenaw Employers
Small shops, outfitters and startups may have too few employees to get strong small group pricing. We compare small group plans with an individual coverage HRA, which gives each employee a fixed allowance toward an individual plan that works where they live. We also explain the notice and setup steps involved.
Frequently Raised by Houghton Owners
Does CFH work with employers in the Copper Country?
Yes. We advise Houghton employers on plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers who weigh the whole program (cost, plan performance, risk and administration), and we normally begin with the plan and renewal you already have.
Staff turn over every few years and your plan never adapts? Learn how a move to CFH works.
Share Your Houghton Renewal
Give us the renewal letter, plan summary, contribution split and enrollment counts by tier, plus two more documents at fifty employees or above, and we will show what the number is made of. Call 248.370.8853 or email info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
