
What You Can Test Before You Sign Anything
Every broker in this market promises service. Not one of those promises is checkable in advance, which is precisely why they are made. Here are questions with answers you can verify against a calendar and a bank statement.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
Who Specifically Is Assigned to Your Account
and who answers when that person is away
What the Stated Turnaround Is on an Enrollment
a termination and an identification card, and what the elapsed times actually were last year
How Many Billing Discrepancies Were Found and Recovered
rather than noticed and paid
Which Administration the Firm Performs Itself
Which administration the firm performs itself and which it merely advises on
Accuracy Has a Deadline Attached, and It Is Shorter Than You Think
Some carriers will not adjust a billing error beyond a hundred and twenty days. Past that point the mistake is no longer a mistake to be corrected, it is money gone. A terminated employee left sitting on the invoice for four months is a real loss with a real figure attached, and that figure is usually larger than whatever premium difference a broker was arguing about.
This is why first-pass accuracy on eligibility transactions is worth more to a small employer than almost anything said about plan design. The clock is already running in your correspondence file; nobody has been reading it.
Where the Actual Savings Live at This Size
The Carrier Chosen
since approved increases differ by several points between them in any given year
Dental and Vision for a Small Range Employer
which are bought against card rates for your size band rather than built from your claims
Employer-Paid Life and Disability for Physical Work
priced on rates and often unchanged for many years
How Many Eligible People Enroll
which shapes pricing more than employers expect
Questions From Marquette County Employers
Is a broker worth anything if the rate is fixed?
The rate is fixed. The administration is not, the ancillary lines are not, and the carrier choice is not. A commission is inside your premium regardless, so the question is what comes back for it.
We have eleven employees. Are we too small to matter?
No. Eleven enrolled subscribers is a group, and the work of running it properly is much the same as running a larger one.
Iron Mining Still Drives the Marquette Range
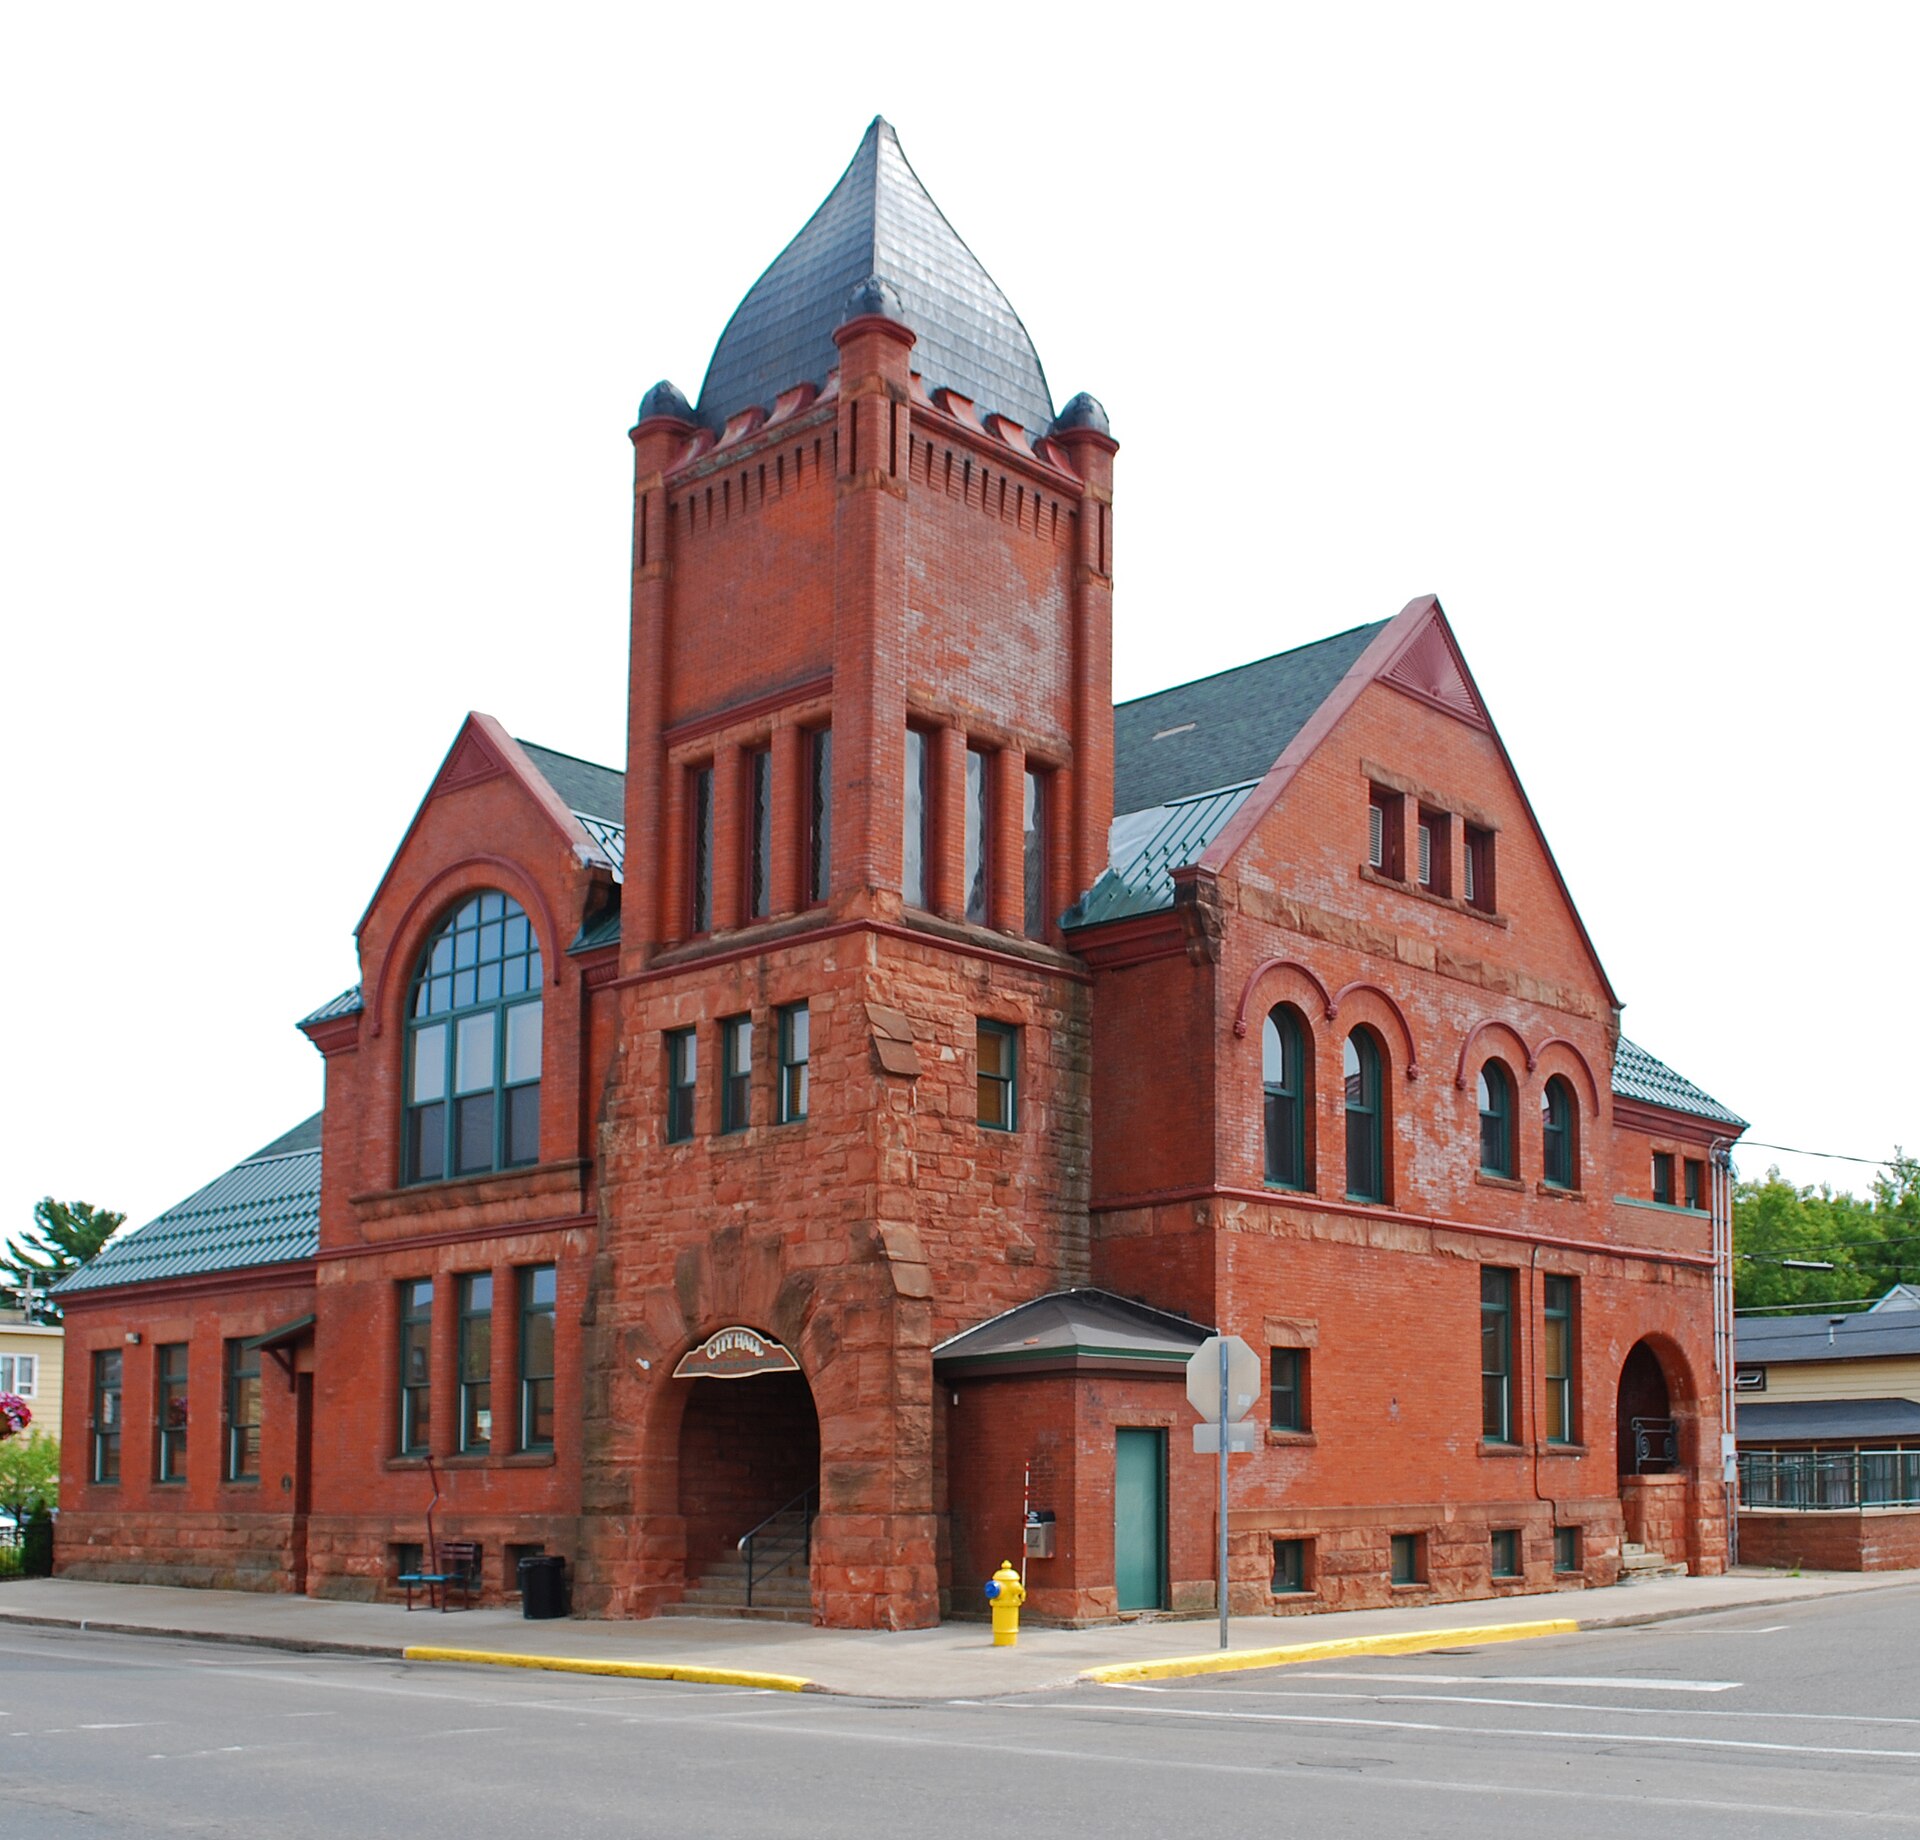
Ishpeming is a Marquette County city in the Upper Peninsula, about 15 miles west of Marquette, with 6,140 residents in the 2020 census. Its economy has centered on iron ore since the Marquette Iron Range was opened. Cleveland-Cliffs’ Tilden Mine, about five miles south of town, employed 990 workers as of 2023, according to The Mining Journal, and ships iron pellets by rail to the port at Marquette. Local hospital care comes from UP Health System – Bell on Lakeshore Drive, with larger services in Marquette. Ishpeming is also home to the U.S. National Ski Hall of Fame. For employers here, a single dominant industry, long distances to specialty care and a small labor market all shape how health, disability and life benefits should be built.
Rural Networks and Travel for Care
Specialty care in the Upper Peninsula can mean long drives. We check that plans include UP Health System – Bell, Marquette hospitals and the specialists employees are referred to, and we explain how out-of-area and travel provisions work when treatment is only available farther away.
Disability and Life for Heavy Work
Mining, rail and trades work is physically demanding. We compare short-term and long-term disability, basic and supplemental life, and accidental death coverage, so employees at suppliers and contractors around the range have income protection that is comparable to what larger employers in the area offer.
Small Employers, Big Competition
Local shops and service businesses compete for workers with a large mining employer that offers strong benefits. We benchmark medical, dental and vision plans and explain options such as level-funded plans or ICHRA that can help a smaller employer offer a credible package. We also compare dental and vision plans that add value at modest cost.
Telehealth Where Distance Matters
When the nearest specialist is an hour away, virtual care fills real gaps. We compare how carriers cover telehealth, virtual behavioral health and remote follow-ups, including cost share, so employees in Ishpeming can use those services without guessing what they will owe. We also check whether visits are free or subject to the deductible.
A Few More Ishpeming Questions
Will CFH work with a small Ishpeming employer?
Yes. We advise Ishpeming employers on plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers who review the entire program, including cost, plan performance, risk and administration, and we usually start with the plan and renewal you have now.
Eleven employees and a broker who treats you as an afterthought? See how switching to CFH works.
Send Us What the Carrier Sent You
Bring the renewal letter, plan summary, contribution by tier and enrollment by tier, plus two more documents at fifty and above, and we will explain what is actually in the number. Call 248.370.8853 or email info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
