
Working Past Sixty-Five Is Not the Simple Case People Assume
Whether your group plan or Medicare pays first depends on the size of the employer. At twenty or more employees the group plan is generally primary and Medicare secondary; below twenty the order reverses, and Medicare generally pays first. That single threshold changes the practical answer completely, and it is the same twenty that governs continuation coverage.
For a manufacturer at this size the important consequence is that an employee under a small group plan who has not enrolled in Medicare at sixty-five may find their claims paid by nobody in the way they expected.
The Enrollment Decisions That Come With It
Whether to Enroll in Part A at Sixty-Five
which is usually premium-free but ends the ability to contribute to a health savings account from that point
Whether to Delay Part B
which is generally sensible while covered by a large employer plan and generally not while covered by a small one
How the Annual Creditable
coverage determination on your drug benefit affects a later Part D penalty, which is permanent once incurred
What happens to a spouse who reaches eligibility on a different timetable
which catches people constantly
The Health Savings Account Point Is the Trap
Enrollment in Medicare, including Part A alone, ends the ability to make health savings contributions. An employee who signs up at sixty-five while still contributing has a problem that has to be unwound, and there is a look-back on Part A enrollment that can reach further than expected. Tell people before they enroll rather than after.
What the Employer Owes Regardless
The creditable-coverage notice before the middle of October each year
to Medicare-eligible employees and spouses, at any size
A Disclosure to the Federal Government
A disclosure to the federal government within sixty days of the plan year starting
Equal treatment of older employees in what is offered
since you cannot push someone off the group plan because they became eligible
Continuation Coverage from Twenty Employees
with nothing in Michigan law beneath it
Questions From Dickinson County Employers
Can we ask an employee to move to Medicare and drop our plan?
No. You cannot induce someone to leave the group plan because they became Medicare-eligible. You can and should make sure they understand their options.
Are we above or below the twenty-employee line?
Worth establishing precisely, because it decides which coverage pays first and that is not a detail your employees can work out for themselves.
Built by Ford, Still Built on Manufacturing
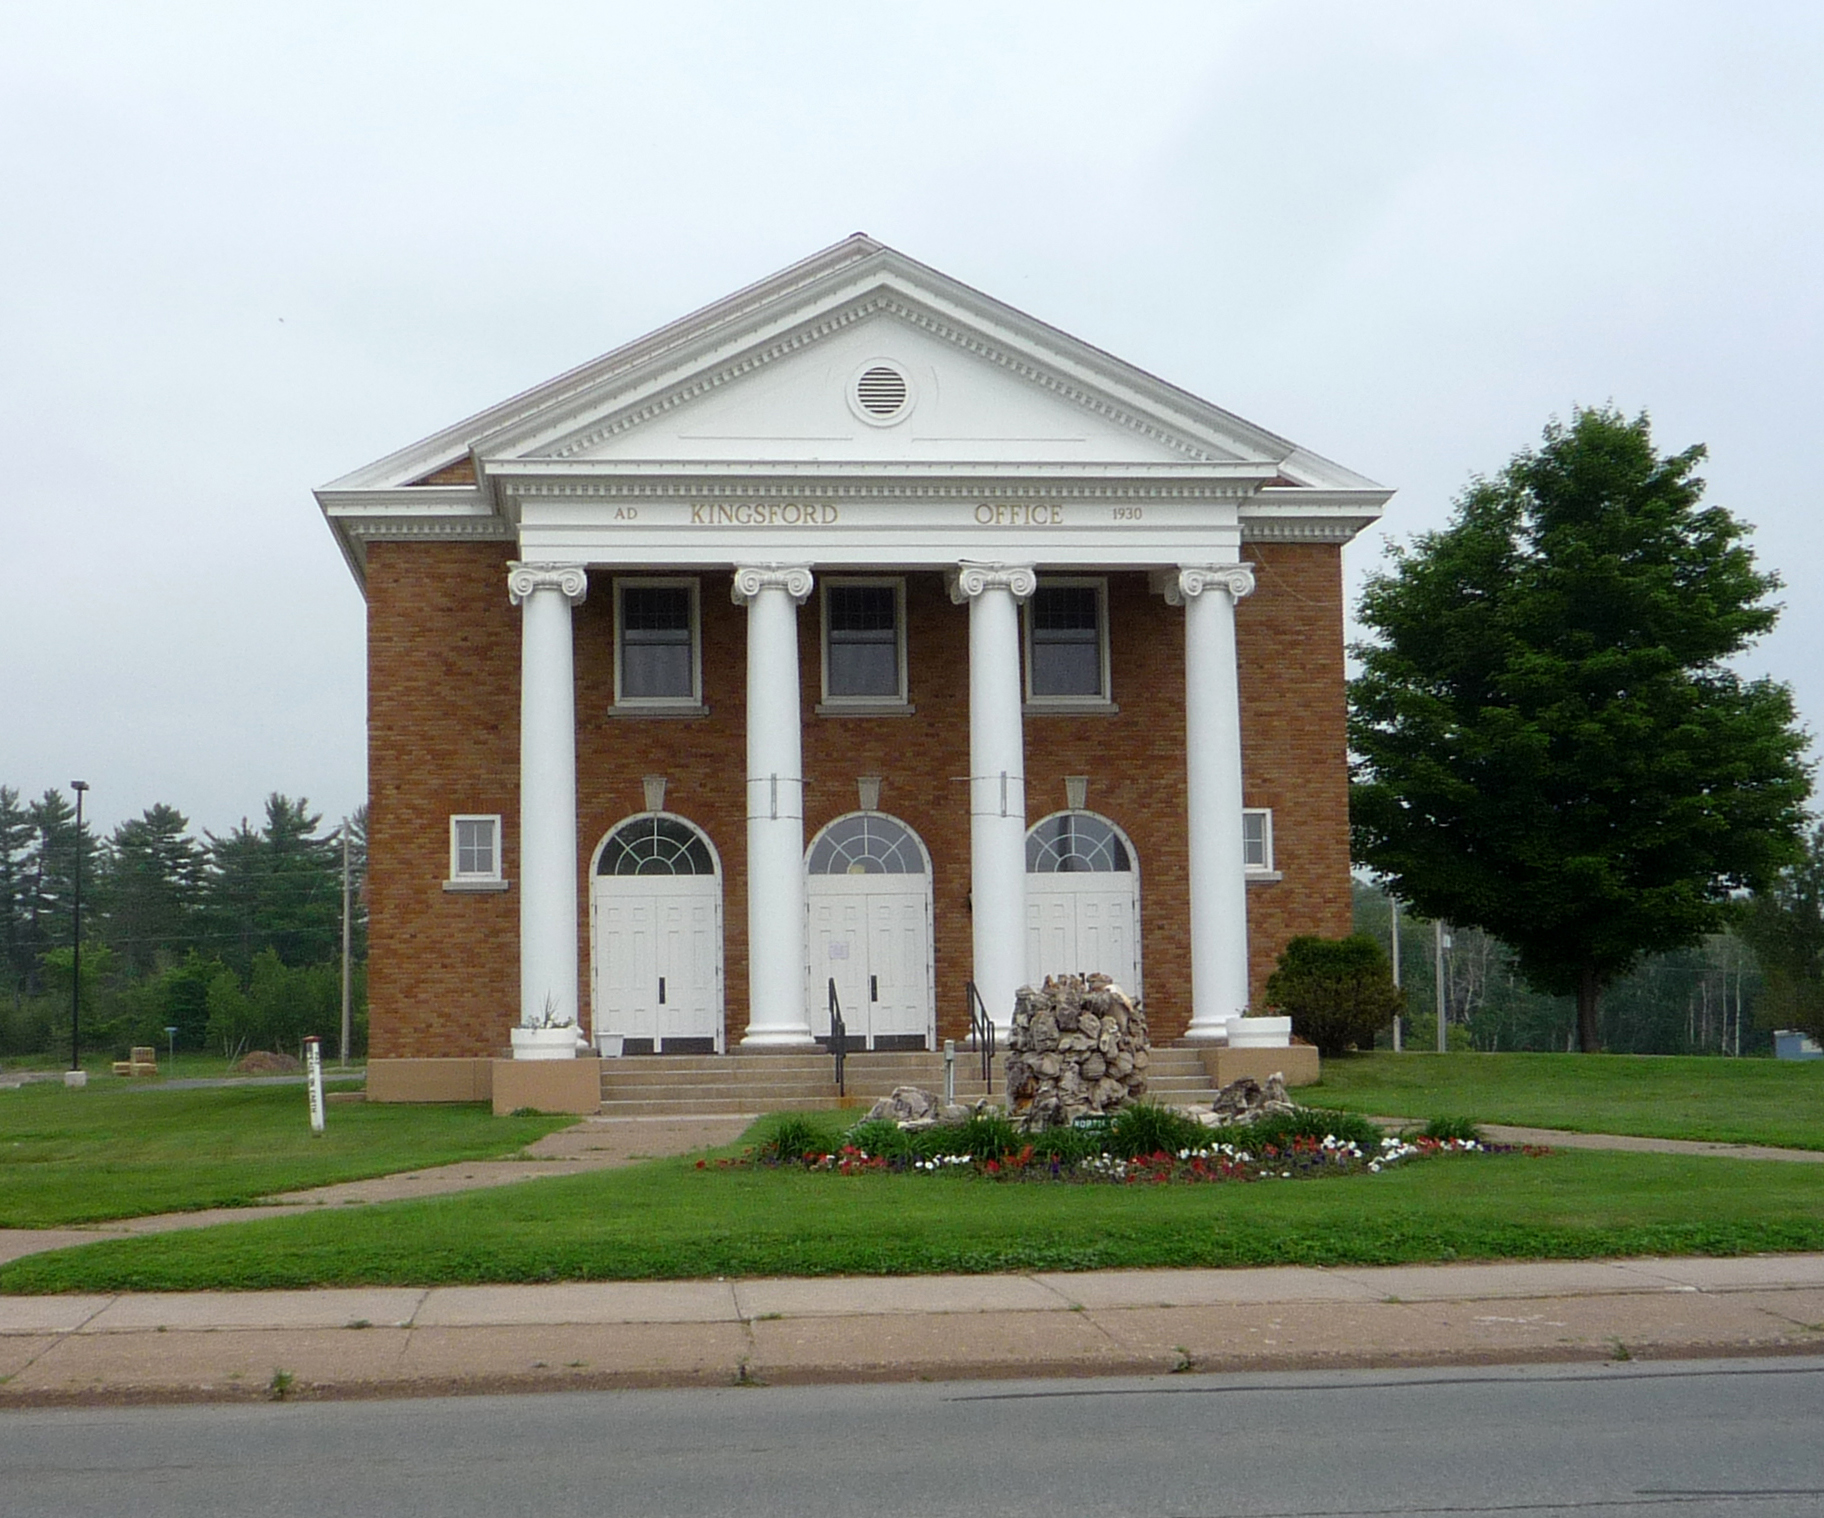
Kingsford grew around a Ford Motor Company plant that built wooden station wagon bodies from 1931, and scrap wood from that plant became the charcoal business that still carries the city’s name. Manufacturing is still central to the Iron Mountain–Kingsford area, where it accounts for about one in five jobs, alongside the Dickinson County hospital system, the Oscar G. Johnson VA Medical Center and the paper mill between Kingsford and Norway. Ford Airport, the area’s commercial airport, is in Kingsford.
Networks That Cross the State Line
Kingsford sits on the Wisconsin border, and many families use providers on both sides. A plan whose network stops at the Michigan line can leave employees paying out of network for care they consider local.
Fewer Carriers, Careful Comparisons
The Upper Peninsula has fewer carrier and network options than lower Michigan. That makes it more important to compare the ones that are available side by side, on cost and on access.
Industrial Workforces
Foundry and mill work carries a higher risk of time off work. Short- and long-term disability and life coverage deserve as much attention as the medical plan.
Send Us the Renewal and the Age Profile
Bring us the renewal letter, the current plan summary, the contribution split by tier and the enrolled counts by tier — two more documents if you are at fifty or above — and we will tell you what the number is actually made of. Call 248.370.8853 or write to info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Questions We Get
The questions employers ask us most are answered in full on our resources page.
