
The Premium Does Not Follow Your Season
Coverage is billed monthly at a level rate. Your income is not level. February costs the same as July and produces a fraction of the revenue, and the shortfall has to be carried somewhere — usually on the owner’s working capital, quietly, every winter.
What Can Actually Be Arranged Around It
Choosing a plan year that starts with your season rather than in January
so the renewal decision and the cash both arrive when you can think clearly
Setting the employer contribution as a fixed dollar amount rather than a percentage
so a rate increase does not compound a cash problem
Being deliberate about which staff are eligible year-round and which are seasonal
using written classes and a measurement period rather than deciding case by case
Understanding, if you are level-funded, exactly when the reconciliation settles
a refund arriving in the wrong month is worth much less than the same money in the right one
And Be Careful With Coverage That Stops and Starts
Dropping seasonal staff off the plan at the end of the season and re-adding them in spring sounds efficient and creates several problems at once: continuation rights triggered each autumn, waiting periods potentially restarting each spring, and a participation percentage that swings across the carrier’s minimum twice a year. A measurement and stability approach handles the same workforce far more cleanly, by classifying someone once and holding it.
Other Rules That Still Apply
Seasonal Hours Aggregate into the Full
time-equivalent count that decides whether the coverage duty applies, averaged across the prior calendar year
A Narrow Exception Exists for Employers
A narrow exception exists for employers exceeding fifty for four months or less where the excess is genuinely seasonal, and it needs checking rather than assuming
Continuation Coverage Once You Reach Twenty
No Michigan statute adds a smaller-group version.
Dental and Vision Rate Against Size Bands
so an enrolled count that swings seasonally can move those lines on its own
Questions From Mason County Employers
Can we change our plan year?
Usually yes, at renewal, and it is worth considering rather than inheriting whatever date was set years ago.
Do we have to cover seasonal staff?
Only if they are classified full-time under your measurement approach. Having one, written down, is what makes the answer defensible either way.
Lakeshore Hospital, Fruit Packing and Factory Floors
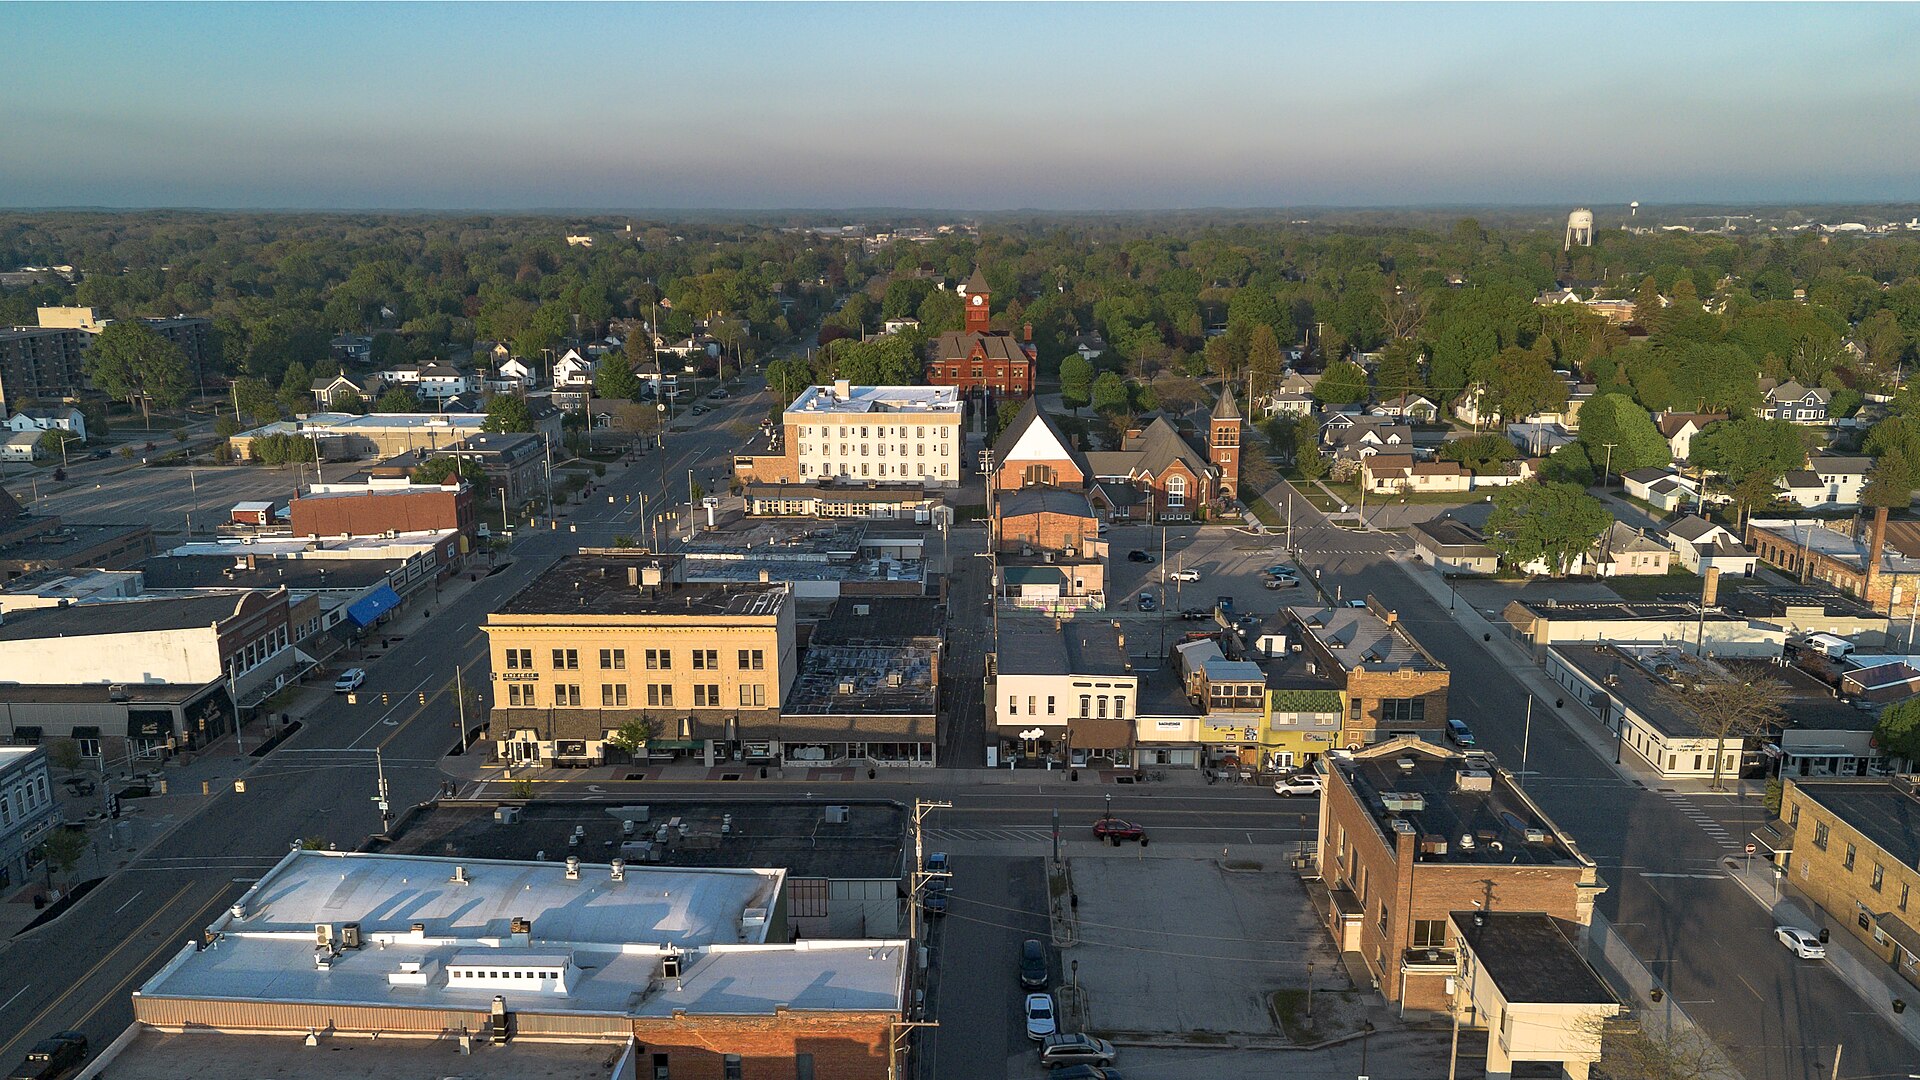
Ludington is the county seat and largest city in Mason County, with 7,655 residents at the 2020 census. It sits where the Pere Marquette River meets Lake Michigan and is the home port of the SS Badger car ferry to Manitowoc, Wisconsin. Corewell Health Ludington Hospital anchors local healthcare with emergency services, a birthing center and surgery. Indian Summer Cooperative, a fruit processor, was listed with 400 employees in a 2020 regional employer survey, and manufacturers such as Whitehall Industries, Great Lakes Castings and Carrom Company also operate here. The county’s main industries are agriculture, manufacturing, healthcare, retail and tourism. That mix of hourly production, clinical and seasonal service work means one benefits design rarely fits every employee group.
Confirm Corewell Ludington Is In-Network
Most Mason County employees will want care at Corewell Health Ludington Hospital, and Trinity Health Michigan also offers primary and urgent care in town. We check that both systems sit in-network on any plan you consider, including the specialists and larger hospitals your employees are referred to for care not offered locally.
Write Clear Rules for Seasonal Staff
Tourism and fruit processing bring hiring peaks every summer and fall. We help you set waiting periods and hours-based eligibility rules that fit ACA measurement requirements, so seasonal and variable-hour workers are treated consistently and full-time staff are not caught in gaps when schedules change between busy and slow months.
Protect Production Workers’ Paychecks
Castings, extrusion and food processing are physical jobs, and a back or shoulder injury off the clock can keep someone out for weeks. We compare short-term disability and voluntary accident coverage options so employees have income support that workers’ compensation does not provide for injuries and illnesses outside of work.
Price Small-Group Renewals Carefully
Many Ludington employers are small groups, where one large claim can move a renewal sharply. We compare fully insured, level-funded and ICHRA options side by side, explain how each handles claim risk, and show what the change would mean for employee contributions before you commit to a new plan year.
Tell Us When Your Season Runs
Send the renewal letter, plan summary, contribution by tier and enrolled counts by tier, and two more documents if you are at fifty or more. We will lay out what the increase is made of and how the timing could line up with your season. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Winter premiums draining summer cash? See how switching to CFH works.
Related: how we help employers improve workforce health and control healthcare costs all year, not just at renewal.
