
The Waiting Period Is Shorter Than Some Plan Documents Think
A group health plan cannot impose a waiting period longer than ninety days. That is a firm ceiling, and a number of older plan documents still carry longer arrangements inherited from before the rule existed. It is worth checking yours rather than assuming, because the document is what governs and nobody reads it until something goes wrong. Tying benefits eligibility to employee onboarding keeps waiting periods and effective dates from slipping.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
A common and permissible structure is first of the month following a shorter period, provided the total does not exceed the ceiling. An orientation period can be used before the waiting period begins, within limits, and it has to be genuine rather than a device.
Why a Candidate Cares More Than You Expect
Someone leaving another employer may face a gap in coverage they have to bridge themselves
at individual-market prices
A candidate with a family or an ongoing condition will weigh that gap heavily
sometimes decisively
Continuation coverage from the previous employer is available but expensive
since they pay the whole premium plus an administrative charge
A shorter waiting period is one of the cheapest competitive improvements available
because it affects only the joiners rather than the whole population
And It Interacts With the Coverage Requirement
For an employer above the threshold, an offer of coverage must be made within a defined period after someone becomes eligible, and a waiting period that is too long can itself create exposure. The administrative point matters just as much: the enrollment has to actually be processed during the window, and on a small team a new starter’s paperwork sitting in a drawer for three weeks is how a compliant policy becomes a non-compliant outcome.
Other Points Worth Confirming
Continuation Coverage Beginning at Twenty
Michigan sets no rule underneath it.
Rehired employees may not need to serve the waiting period again
depending on how long they were gone and what the document says
A New Hire’s Election Has To
A new hire’s election has to be made within the enrollment window or they generally wait for the next annual opportunity
Medicare-Eligible New Hires Need the Creditable-Coverage
Medicare-eligible new hires need the creditable-coverage notice as well
Waiting-Period Questions From Rochester Employers
Can we make people wait six months?
No. Ninety days is the ceiling, and a document saying otherwise needs correcting rather than following.
Should we shorten ours to nothing?
Sometimes worth it in a competitive market, though it raises cost on people who leave quickly. First of the month after thirty days is a common middle position.
A University Town With a Major Hospital
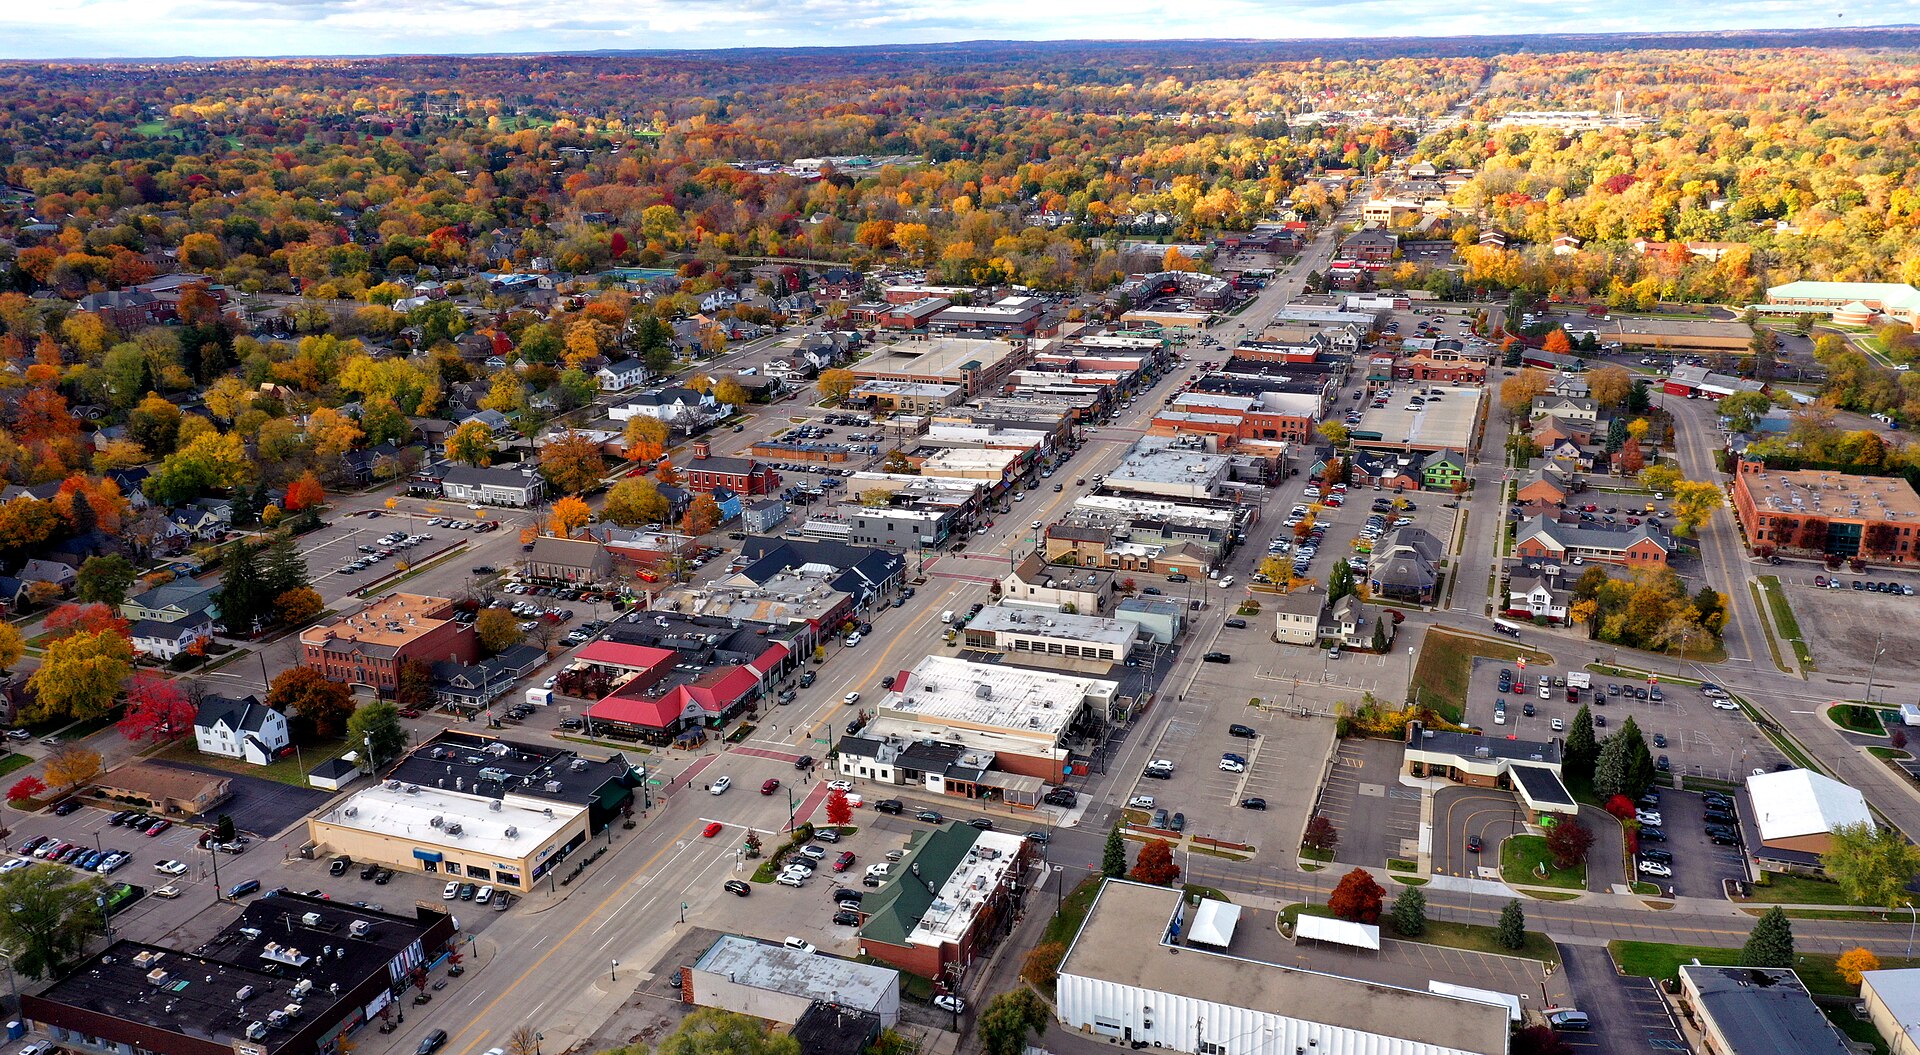
Rochester is an Oakland County city of 13,035 residents (2020 census), about 27 miles north of downtown Detroit and mostly surrounded by Rochester Hills. Oakland University has used a Rochester mailing address since 1958, and Rochester University and Oakland Community College are also nearby. Henry Ford Rochester Hospital, formerly Ascension Providence Rochester, is a 290-bed acute-care hospital on University Drive. The city reports that 52 percent of residents hold a bachelor’s degree or higher, and its walkable downtown is home to restaurants, shops and small professional firms. Employers here compete for educated professionals and health care staff, so benefits are part of the pitch, not an afterthought.
Offer Benefits Professionals Expect
Rochester’s educated workforce often compares offers on the full package. We benchmark medical, dental, vision, life and disability against what similar employers in Oakland County provide, and show where modest changes, like richer dental or an HSA contribution, can improve how your offer compares. We also look at voluntary benefits.
Check Both Major Health Systems
Employees in the Rochester area use Henry Ford Health, Corewell Health and other systems. We check that the hospitals and physician groups your people rely on are in-network, and explain what changes if you choose a narrower network to save on premium. We also compare how each carrier handles referrals.
Help Downtown Businesses Compete
Restaurants, shops and small professional firms downtown often have too few employees for easy group underwriting. We compare small-group, level-funded and ICHRA options, and explain how each works for owners who want to offer something meaningful without a long-term cost commitment. We also explain how the choice affects owners.
Keep Compliance Paperwork Current
Growing firms can miss steps as they add staff. We explain the notices, plan documents and ACA reporting that apply at your size, and help set a calendar so filings like Form 5500 or 1095-C reporting are handled on time when they apply. We also flag thresholds as you grow.
Your Rochester Benefits Questions
Can CFH help a Rochester employer?
Yes. We advise Rochester employers on plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers who look at cost, plan performance, risk and administration together, and we typically start with your current plan and renewal.
Losing candidates to a waiting period nobody has questioned? See how switching to CFH works.
Let Us Check What Your Document Says
Send the renewal letter, plan summary, contribution by tier and enrollment by tier, plus two more documents at fifty or above, and we will check what your document says about waiting periods. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
