
In the competitive landscape of employee benefits insurance, understanding pricing options is crucial for businesses seeking the best value. This article delves into how CFH Insurance Consulting compares to other brokers in Michigan, focusing on various pricing models and their implications for businesses. Readers will learn about the key pricing structures, the unique offerings of CFH, and how these factors influence overall costs. Many businesses struggle with navigating the complexities of insurance pricing, which can lead to overspending or inadequate coverage. By exploring CFH’s pricing strategies, businesses can make informed decisions that align with their financial goals. This article will cover the key pricing models used by CFH and other brokers, a comparison of group health insurance pricing, and insights into dental, vision, disability, and life insurance options. For a broader understanding, businesses can also refer to the Michigan employer health insurance guide.
16 min read
Health Insurance Broker Pricing Models: A Michigan Comparison
Pricing models in the insurance industry can significantly impact the overall cost and value of employee benefits. CFH insurance brokers and other Michigan insurance consultants utilize various pricing structures, including commission-based, flat fee, and percentage of premium models. Understanding these broker pricing models helps businesses choose the most suitable option for their needs. Additionally, businesses interested in affordable employee health insurance options can benefit from comparing these pricing models.
How Do Commission, Flat Fee, and Percentage of Premium Models Differ?
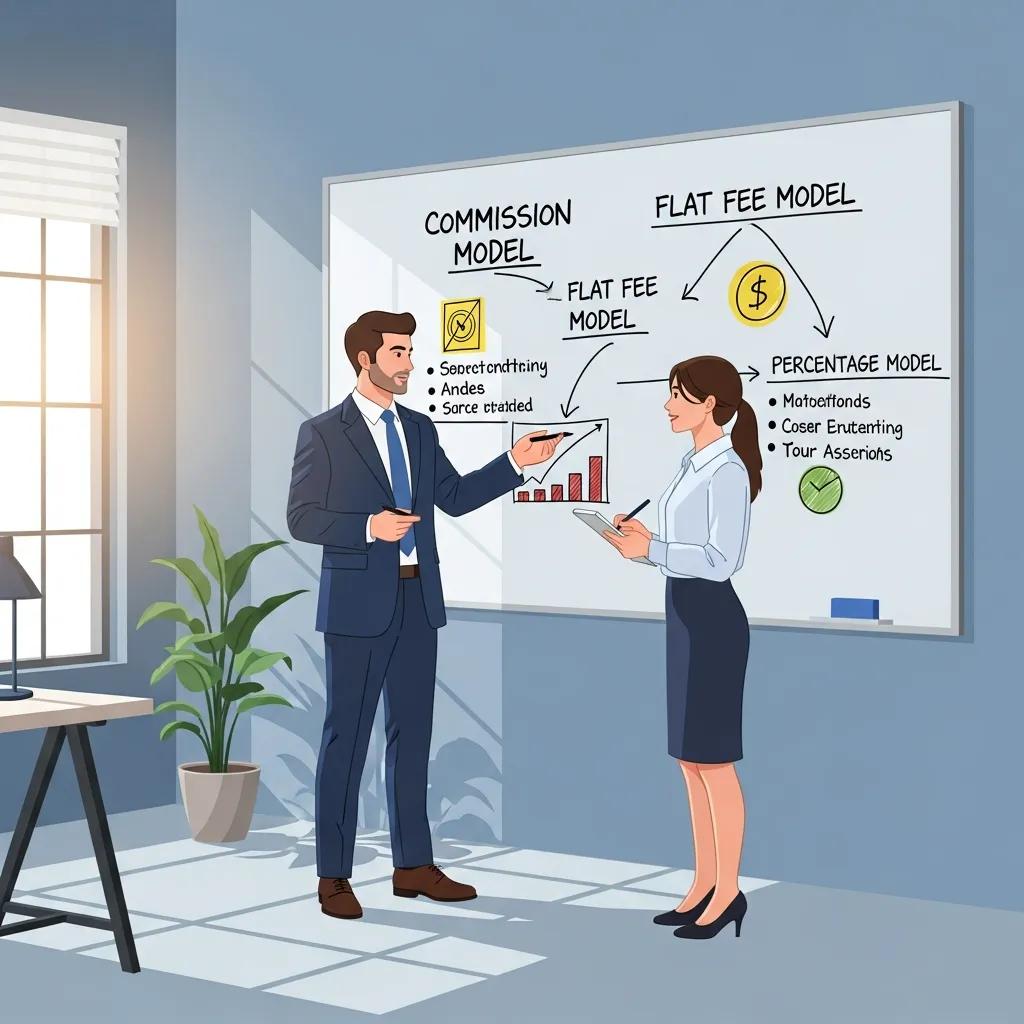
Commission-based models involve brokers earning a percentage of the premiums paid by clients, which can create a conflict of interest if brokers prioritize higher premiums for greater commissions. Flat fee models charge a set amount for services, providing transparency and predictability in costs. Percentage of premium models, while common, can lead to fluctuating costs based on the total premium amount. Each model has its pros and cons, and businesses should evaluate which aligns best with their financial strategies and needs. For more detailed insights, businesses can explore how pricing varies by employee count.
Further research highlights the complexities and potential conflicts of interest inherent in certain brokerage compensation structures.
For businesses seeking comprehensive employee benefits solutions, CFH Insurance offers tailored consulting services.
Detailed Broker Fee Structure Comparison: Commission-Based vs. Fee-Based vs. Hybrid Models
When comparing CFH insurance brokers to other Michigan insurance consultants, understanding the nuances of broker fee structures is essential. Commission-based models typically pay brokers a percentage of the insurance premium, incentivizing higher premiums but potentially leading to conflicts of interest. Fee-based models charge a flat or hourly fee, offering transparency and aligning broker incentives with client cost control. Hybrid models combine both approaches, balancing transparency with broker motivation.
CFH insurance brokers often utilize a hybrid approach, providing clients with clear fee disclosures while maintaining competitive commission arrangements. This approach ensures clients receive value without hidden costs. In contrast, some traditional brokers may rely solely on commissions, which can obscure true costs.
Transparency Analysis: How Different Brokers Disclose Pricing
Transparency in broker pricing is a critical factor for businesses evaluating insurance broker services. CFH insurance brokers prioritize clear communication, providing detailed breakdowns of fees, commissions, and any additional charges. This transparency fosters trust and enables businesses to budget accurately.
Many Michigan insurance consultants, however, may not disclose full fee structures upfront, leading to surprises during renewal or plan changes. CFH’s commitment to transparency is a key differentiator, supported by client testimonials praising their openness and straightforward communication.
Value-Added Services Comparison: Technology Platforms, Compliance Support, HR Consulting
Beyond pricing, value-added services significantly impact the overall benefits experience. CFH insurance brokers offer advanced technology platforms that streamline enrollment, benefits administration, and employee communication. Their compliance support ensures businesses stay current with evolving regulations, reducing risk and administrative burden.
Additionally, CFH provides HR consulting services, helping businesses design benefits packages that align with workforce needs and company culture. Many other brokers offer limited technology or compliance support, focusing primarily on plan placement rather than ongoing service.
Client Service Model Differences: Dedicated Account Manager vs. Team Approach
CFH insurance brokers typically assign a dedicated account manager to each client, ensuring personalized service, quick response times, and deep understanding of the client’s business. This contrasts with some brokers who use a team approach, where clients may interact with multiple representatives, potentially leading to inconsistent service.
Clients of CFH report higher satisfaction due to this personalized model, which facilitates proactive communication and tailored solutions.
Broker Specialization Analysis: Generalist vs. Michigan Mid-Size Employer Specialist
While many insurance brokers serve a broad market, CFH insurance brokers specialize in Michigan mid-size employers, offering expertise tailored to this segment’s unique challenges and opportunities. This specialization enables CFH to provide more relevant plan options, pricing strategies, and compliance guidance compared to generalist brokers.
Claims Advocacy and Support Comparison
Effective claims advocacy can save businesses time and money. CFH insurance brokers provide robust claims support, assisting clients in resolving disputes, expediting approvals, and managing complex cases. This hands-on approach contrasts with some brokers who offer minimal claims assistance, leaving clients to navigate issues independently.
Renewal Process and Ongoing Optimization Differences
CFH insurance brokers emphasize proactive renewal management and ongoing plan optimization. They conduct thorough annual reviews, analyze utilization data, and recommend adjustments to maintain cost-effectiveness and employee satisfaction. Other brokers may take a more reactive approach, limiting opportunities for cost savings and plan improvements.
CFH Insurance Consultants vs. Traditional Brokers: 2026 Comparison
Source: CFH Insurance Consultants competitive analysis, 2026
What a Broker Change Typically Surfaces
Employers who move from one broker to another tend to find the same handful of things. They are worth naming because each one is checkable against your own file rather than against someone else’s story.
The first is how much of the market was actually tested. If your renewal has arrived with the same two or three quotes year after year, that is a narrower test than most group sizes support. The second is network fit — whether the carrier’s network covers where your employees actually live, which is straightforward to check against your census and is a common source of avoidable disruption. The third is whether plan design has kept pace: an unchanged structure across several renewals usually means newer deductible and HSA options were never put in front of you.
The fourth is compensation. Whether a broker is paid by commission, by fee, or by some combination of the two shapes what a recommendation is worth, and it is a fair question to ask directly of anyone you work with, including us.
How CFH Insurance Brokers Compare to Traditional Consultants
CFH insurance brokers distinguish themselves from traditional Michigan insurance consultants through their comprehensive service model, transparent broker pricing models, and client-centric approach. Their integration of technology, compliance expertise, and personalized service creates a superior client experience.
What Are Typical Broker Fees for Group Health Insurance Plans?
Typical broker fees for group health insurance plans can vary widely. CFH insurance brokers aim to provide transparent pricing, ensuring that clients understand the costs associated with their plans. This transparency can lead to better budgeting and financial planning for businesses. It also makes the conversation about what you are paying for a straightforward one rather than something you have to reconstruct from a rate sheet.
How Do CFH’s Flexible Pricing Options Benefit Michigan Businesses?
CFH insurance brokers’ flexible pricing options allow businesses to customize their plans according to their specific needs. This flexibility can include varying levels of coverage, which can help businesses manage costs while still providing comprehensive benefits to employees. By offering tailored solutions, CFH supports Michigan businesses in achieving their employee benefits goals without overspending. Learn more about how CFH customizes health insurance plans to fit unique business needs.
What Are the Differences Between QSEHRA and ICHRA Pricing Options Offered by CFH and Others?
CFH insurance brokers provide both Qualified Small Employer Health Reimbursement Arrangements (QSEHRA) and Individual Coverage Health Reimbursement Arrangements (ICHRA). The primary difference lies in eligibility and contribution limits. QSEHRA is designed for small employers, allowing them to reimburse employees for individual health insurance premiums, while ICHRA offers more flexibility in terms of employee eligibility and contribution amounts. Understanding these differences is crucial for businesses looking to optimize their employee benefits strategy.
The strategic implementation of HRAs like QSEHRA and ICHRA can significantly impact how small businesses manage their employee benefits.
How Do QSEHRA and ICHRA Impact Employee Benefits Costs?
Both QSEHRA and ICHRA can significantly impact employee benefits costs. QSEHRA allows small businesses to offer health benefits without the burden of traditional group insurance premiums, while ICHRA provides a more customizable approach that can lead to cost savings for both employers and employees. By leveraging these options, businesses can enhance their benefits offerings while managing expenses effectively.
For businesses interested in exploring these options, CFH Insurance offers expert consulting services to navigate the complexities of QSEHRA and ICHRA plans.
Why Choose CFH’s Consulting Services for QSEHRA and ICHRA Plans?
Choosing CFH insurance brokers for QSEHRA and ICHRA plans means gaining access to expert guidance and tailored solutions. CFH’s team understands the complexities of these arrangements and can help businesses navigate the regulatory landscape, ensuring compliance while maximizing benefits for employees. This level of support can be invaluable for businesses looking to implement these innovative health reimbursement strategies.
Evaluating Michigan Insurance Consultants: What Sets CFH Apart
CFH insurance brokers stand out among Michigan insurance consultants due to their commitment to transparency, client service, and specialized expertise. Their use of advanced technology platforms, dedicated account managers, and comprehensive compliance support creates a superior client experience.
How Does CFH Manage Cost and Plan Customization for Disability and Life Insurance?
CFH insurance brokers emphasize cost management and plan customization for disability and life insurance. By working closely with clients, CFH can tailor plans that meet specific needs while keeping costs manageable. This approach not only enhances employee satisfaction but also helps businesses maintain financial stability.
To learn more about disability and life insurance options, businesses can contact CFH insurance brokers for personalized consultations.
How Do Dental, Vision, Disability, and Life Insurance Pricing Options at CFH Compare to Other Brokers?
CFH insurance brokers also offer a range of pricing options for dental and vision, disability, and life insurance, which are essential components of a comprehensive employee benefits package. Understanding how these options compare to other brokers can help businesses make informed decisions.
What Are Common Pricing Structures for Dental and Vision Insurance Brokers?
Common pricing structures for dental and vision insurance typically include monthly premiums, deductibles, and co-pays. CFH insurance brokers strive to provide competitive rates while ensuring that clients receive quality coverage. By comparing these structures with other brokers, businesses can identify the best value for their employees’ needs.
Typical Broker Fee Structures in Michigan and How CFH Aligns
Understanding typical broker fee structures in Michigan is essential for businesses looking to optimize their insurance costs. CFH insurance brokers align their fees with industry standards while providing transparency and value to clients.
How Do Broker Fees Vary by Plan Size and Complexity?
Broker fees can vary significantly based on the size and complexity of the insurance plan. Larger plans may incur higher fees due to the increased administrative burden, while smaller plans may benefit from lower fees. CFH insurance brokers offer competitive pricing structures that reflect the specific needs of each client, ensuring that businesses receive fair value for their investment.
How Transparent Are CFH’s Fees Compared to Local Competitors?
CFH insurance brokers pride themselves on transparency regarding fees, which can be a significant differentiator in the market. By clearly outlining costs and services, CFH helps clients understand what they are paying for, fostering trust and long-term relationships. This level of transparency is often lacking in the industry, making CFH a preferred choice for many businesses. To avoid pitfalls, businesses should also be aware of common mistakes when selecting a broker.
Have a Renewal Coming Up?
Send us your renewal and we will tell you whether the increase is competitive. We review it at no cost, and you only need four documents.
Send Us Your RenewalWhy Broker Independence Matters for Michigan Mid-Market Employers
The difference between independent brokers like CFH Insurance Consultants and captive agents or national chains isn’t just philosophical—it has measurable financial and operational impact:
- Carrier Access = Negotiating Power: Independent brokers access many carriers (CFH works with 93), creating genuine competition for your business. Captive agents represent one carrier. National chains often have “preferred partnerships” that limit true independence. CFH’s 30+ year Michigan relationships mean carriers compete aggressively for our clients.
- Unbiased Recommendations: Captive agents earn commissions only from their carrier—creating inherent bias. Some national brokers receive “override bonuses” for hitting volume targets with specific carriers. CFH’s compensation is transparent and consistent across all carriers, ensuring recommendations are based solely on client fit, not commission structure.
- Michigan Market Expertise: National brokers serve all 50 states—Michigan is just one market among many. Michigan is the home market for CFH and where most of our work is done. We know which carriers have the best networks in Grand Rapids vs. Detroit vs. Lansing. We understand Michigan-specific regulations (PA 350, DIFS requirements). We have relationships with regional carriers that national brokers overlook.
- Mid-Market Specialization: Generalist brokers serve 5-employee small businesses and 5,000-employee enterprises. CFH serves only 50-500 employee companies. This means our benchmarking data, best practices, carrier relationships, and service model are perfectly calibrated to your group size. You’re not a small fish in a big pond—you’re our ideal client.
- Long-Term Partnership vs. Transactional Service: Online marketplaces and some brokers focus on the initial sale, then provide minimal ongoing support. CFH provides quarterly business reviews, proactive compliance updates, continuous cost optimization, and strategic planning. Clients stay with us because we keep delivering value between renewals, not only at them.
How Can Small Businesses Benefit from CFH’s Employee Benefits Insurance Pricing?
Small businesses can derive significant advantages from CFH insurance brokers’ employee benefits pricing. By leveraging tailored solutions and flexible pricing models, these businesses can enhance their benefits offerings while managing costs effectively.
What Cost Management Strategies Does CFH Offer for Small Employers?
CFH insurance brokers provide several cost management strategies for small employers, including wellness programs, customized benefits packages, and negotiation support for insurance rates. These strategies not only help control costs but also improve employee satisfaction and retention.
Effective cost control strategies are vital for employers aiming to provide comprehensive yet affordable benefits packages.
How Should You Compare Brokers on Price?
Comparing brokers on price is harder than it sounds, because for the same group and the same carrier the premium is largely the same regardless of who places it. In the small-group market especially, rates come from the carrier’s filed tables, so a broker cannot negotiate your rate down the way the pitch sometimes implies.
What does differ between brokers is worth asking about directly:
- How much of the market they actually check, and whether they present alternative funding structures priced on your census or only your incumbent’s renewal.
- What their compensation is and where it comes from. Commission built into your premium is still money you pay. Ask for it in writing — the Consolidated Appropriations Act requires disclosure for brokers expecting $1,000 or more from a group health plan.
- What compliance work is included rather than billed separately: plan documents, summary plan description, Form 5500, non-discrimination testing, the gag clause attestation.
- Who handles a denied claim or a billing error, and how quickly.
We do not claim a pricing advantage over other brokers on identical coverage, because on identical coverage there generally is not one. The difference shows up in what gets checked, what gets included and who does the work.
Frequently Asked Questions About Choosing a Health Insurance Broker
How do health insurance brokers get paid?
Health insurance brokers typically get paid through commissions from insurance carriers, flat fees charged to clients, or a combination of both (hybrid models). CFH uses a transparent hybrid model, so what we are paid is stated rather than buried in the rate. Whether that costs you more or less than a commission-only arrangement depends on the size of the group and the work involved, and we would rather show you the arithmetic than claim a percentage.
What is the difference between a broker and an agent?
A broker represents the interests of the client and can offer plans from multiple insurance carriers, while an agent typically represents one insurance company and sells only that company’s products. CFH’s independent broker model ensures unbiased plan recommendations tailored to Michigan mid-market employers.
Does using a broker cost me more for health insurance?
Using a broker does not necessarily cost more. Brokers like CFH provide transparent pricing and can often negotiate better rates or find plans that fit your budget, potentially saving money overall. What that is worth depends on where your current plan sits against the market, which a market test answers and a renewal letter does not.
How does CFH’s pricing compare to other Michigan brokers?
CFH insurance brokers offer competitive and transparent pricing models, often combining commission and fee-based structures to align with client interests. Their flexible pricing and value-added services differentiate them from many traditional brokers, so the fee arrangement is visible and can be compared against what you are getting for it.
What should I look for when comparing health insurance brokers?
Key factors include pricing transparency, range of insurance broker services, client service model, broker specialization, technology platforms, compliance support, and claims advocacy. CFH excels in all these areas, providing dedicated account managers and proactive compliance support.
Can I switch brokers if I’m unhappy with my current one?
Yes, businesses can switch brokers if they are dissatisfied. It’s important to review contract terms and ensure a smooth transition to avoid coverage gaps. CFH offers seamless onboarding and transition support to minimize disruption.
Do all brokers offer the same health insurance plans?
No, brokers have access to different carriers and plan options. Specialized brokers like CFH insurance brokers may offer plans tailored to Michigan mid-size employers that generalist brokers do not, including regional carriers and customized plan designs.
What value-added services should a broker provide?
Value-added services include technology platforms for benefits administration, compliance support, HR consulting, claims advocacy, and ongoing plan optimization. CFH provides all these services, backed by client testimonials praising their responsiveness and expertise.
How do I know if a broker is reputable?
What is the typical broker commission on health insurance?
Broker commissions vary based on plan size, complexity, and broker pricing models. CFH combines commissions with flat fees for transparency and alignment with client goals.
Side-By-Side Broker Comparison Table
Pricing Transparency Scorecard
Service Offering Checklist
Decision Matrix for Choosing a Broker
Strengthening Credibility: CFH’s Unique Differentiators
CFH’s technology platforms handle the administrative side of benefits — eligibility, enrollment and carrier reconciliation — so that the work does not fall back on HR. Claims advocacy means a person at CFH takes a disputed or stalled claim and works it with the carrier directly, rather than leaving an employee to do it.
These measurable outcomes, combined with transparent broker pricing models and specialized expertise, position CFH insurance brokers as a top choice for Michigan businesses seeking employee benefits insurance solutions.
For further inquiries or to request a consultation, please contact CFH Insurance directly.
Unhappy with your current broker? Switch to CFH. Your employees won’t notice. You will.
Related Guides
Small Group Health Insurance Guide for Michigan Employers (2 to 50 Employees)
How small group health insurance works in Michigan and how to compare your options.
Fully Insured, Level-Funded and Self-Funded Plans Compared
The trade-offs between fully insured, level-funded and self-funded health plans.
Employer Benefits Guides: Eligibility, Plan Design, Life Events and Rules
Our library of plain-English guides on eligibility, plan design and compliance.
What Does an Employee Benefits Consultant Do? Broker vs Consultant Explained
A benefits broker places your group coverage; a consultant advises on funding, design and compliance. How each is paid, what each does and how to…
