
By CFH Insurance Consultants
Navigating the landscape of employee benefits can be particularly challenging for small employers in Michigan, especially those with fewer than 50 employees. Understanding the various health insurance options and compliance requirements is crucial for these businesses to ensure they provide adequate support for their employees while adhering to state and federal regulations. This article will explore the benefits continuation laws specific to small employers in Michigan, the types of health insurance options available, and strategies to enhance employee benefits. By addressing these key areas, small business owners can make informed decisions that not only comply with legal requirements but also foster a supportive work environment.
See also: Improving Health. Controlling Costs. Delivering Results., our approach for employers who want cost to move between renewals.
Continuation Coverage
Continuation coverage refers to the ability of employees to maintain their health insurance benefits after leaving employment or experiencing a reduction in hours. In Michigan, small employers must be aware of the federal COBRA regulations, which apply to businesses with 20 or more employees, as well as state-specific laws that may offer additional protections. Understanding the eligibility criteria for continuation coverage and the duration of such coverage is essential for compliance and employee support. COBRA administration covers the election notices, deadlines and premium collection that come with every departure.
Overview of COBRA and Mini-COBRA
COBRA (Consolidated Omnibus Budget Reconciliation Act) allows employees to continue their health insurance coverage for a limited time after leaving their job. However, for small employers in Michigan, the state does not have a Mini-COBRA law that extends similar benefits to those with fewer than 20 employees. Instead, these employers must navigate the federal guidelines and ensure they provide the necessary information to employees regarding their rights under COBRA.
Eligibility Criteria for Mini-COBRA
While Michigan does not have a Mini-COBRA law, it is important for small employers to understand the eligibility criteria under federal COBRA. Employees who have lost their job or experienced a reduction in hours are typically eligible for continuation coverage. Employers must notify employees of their rights to COBRA coverage within a specific timeframe, ensuring compliance with federal regulations.
Duration of Coverage
Under COBRA, employees can maintain their health insurance coverage for up to 18 months after leaving their job or experiencing a reduction in hours. However, this duration may vary based on specific circumstances, such as disability or other qualifying events. Small employers should be aware of these timelines to provide accurate information to their employees.
Compliance Requirements
Compliance with health insurance regulations is critical for small employers in Michigan. Understanding the various mandates and reporting requirements can help businesses avoid penalties and ensure they are providing the necessary benefits to their employees.
Overview of ACA Mandates
The Affordable Care Act (ACA) imposes several mandates on employers regarding health insurance coverage. Small employers must be aware of these requirements, including the obligation to provide coverage that meets minimum essential coverage standards if they have 50 or more full-time equivalent employees. Failure to comply with ACA mandates can result in significant penalties, making it essential for small businesses to stay informed.
IRS Reporting Requirements
In addition to ACA mandates, small employers must also adhere to IRS reporting requirements. This includes filing forms that demonstrate compliance with health insurance coverage mandates. Employers should ensure they are familiar with these requirements to avoid potential fines and maintain compliance.
State-Specific Mandates
Michigan has specific mandates that small employers must follow, including regulations related to the provision of mental health and substance use disorder benefits. Understanding these state-specific requirements is crucial for small employers to ensure they are providing comprehensive coverage to their employees.
Research highlights the significant impact these state-level mandates can have on small businesses’ decisions to offer health benefits.
Health Insurance Options
Small employers in Michigan have several health insurance options available to them, each with its own benefits and considerations. Understanding these options can help employers make informed decisions that best suit their workforce.
Types of Group Health Insurance Plans
Group health insurance plans are a popular option for small employers, allowing them to provide coverage to their employees at a lower cost than individual plans. These plans can include various coverage options, such as HMO, PPO, and EPO plans, each offering different levels of flexibility and cost-sharing.
Benefits of Offering Health Insurance
Providing health insurance benefits can enhance employee satisfaction and retention. Employers who offer health insurance are often viewed as more attractive to potential employees, which can help small businesses compete in a tight labor market. Additionally, offering health insurance can lead to healthier employees, reducing absenteeism and increasing productivity.
Considerations for Selecting Plans
When selecting health insurance plans, small employers should consider factors such as cost, coverage options, and employee needs. Consulting with insurance experts can help employers navigate the complexities of health insurance and choose the best options for their workforce.
Strategies for Small Businesses
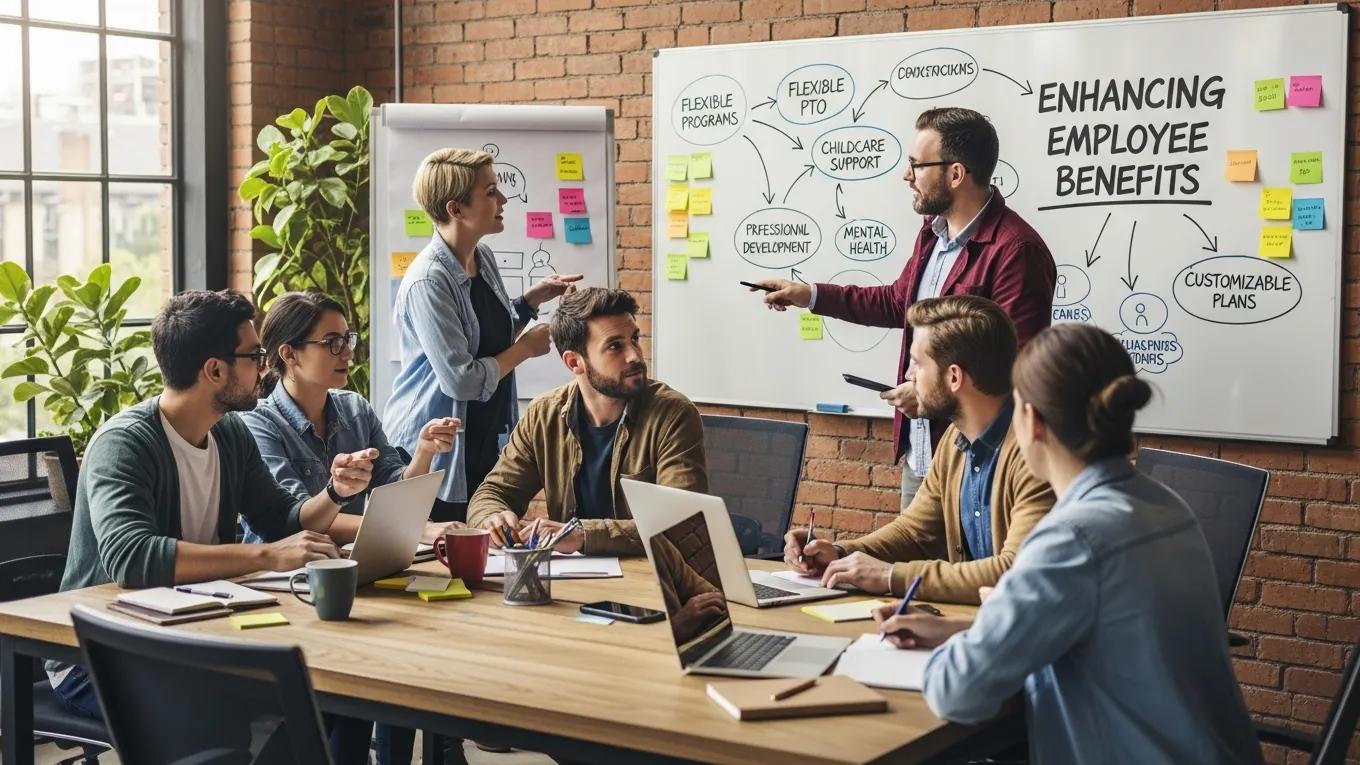
To enhance employee benefits, small businesses can implement several strategies that align with their goals and workforce needs.
Tailoring Benefits Packages
Customizing benefits packages to meet the specific needs of employees can significantly improve job satisfaction. Employers should consider conducting surveys to understand what benefits are most valued by their employees, allowing them to tailor their offerings accordingly.
Consulting with Insurance Experts
Engaging with insurance consultants can provide small employers with valuable insights into the best health insurance options available. These experts can help businesses navigate the complexities of health insurance regulations and find plans that meet both compliance requirements and employee needs.
What Are Michigan Benefits Continuation Laws for Small Employers Under 20 Employees?
In Michigan, small employers with fewer than 20 employees are not subject to the same continuation coverage requirements as larger employers. However, they must still comply with federal COBRA regulations, which provide certain rights to employees regarding the continuation of their health insurance benefits.
Eligibility Criteria for Mini-COBRA
As previously mentioned, Michigan does not have a state-level Mini-COBRA law. Therefore, small employers must rely on federal COBRA guidelines to determine eligibility for continuation coverage. Employees who lose their job or experience a reduction in hours are typically eligible for COBRA coverage.
Coverage Requirements
While small employers are not required to offer continuation coverage under state law, they must provide employees with information about their rights under federal COBRA. This includes notifying employees of their eligibility for continuation coverage and the duration of such coverage.
Does Michigan Have a Mini-COBRA Law?
Michigan does not have a state-level Mini-COBRA law that extends continuation coverage to small employers with fewer than 20 employees. Instead, these employers must adhere to federal COBRA regulations, which provide certain rights to employees regarding the continuation of their health insurance benefits.
Comparison of Mini-COBRA and Federal COBRA
The primary difference between Mini-COBRA and federal COBRA is the size of the employer. Federal COBRA applies to employers with 20 or more employees, while Mini-COBRA laws typically apply to smaller employers. In Michigan, small employers must follow federal guidelines, which can create challenges for both employers and employees.
Implications for Small Employers
The absence of a state-level Mini-COBRA law means that small employers must navigate federal regulations without additional state protections. This can create confusion for both employers and employees regarding their rights and responsibilities under the law.
Michigan Does NOT Have a State-Level Mini-COBRA Law — Here Is What Small Employers Must Know Instead.
Small employers in Michigan must understand the implications of not having a state-level Mini-COBRA law. This lack of additional protections can limit the options available to employees who lose their health insurance coverage.
Limited Continuation Options for Employees
Without a state-level Mini-COBRA law, employees of small employers may have fewer options for maintaining their health insurance coverage after leaving their job. This can create challenges for employees who rely on these benefits for their health and well-being.
Compliance Requirements for Small Employers
Small employers must ensure they are compliant with federal COBRA regulations, including providing employees with the necessary information regarding their rights to continuation coverage. Failure to comply with these regulations can result in significant penalties.
Potential Employee Impact
The absence of a state-level Mini-COBRA law can have a significant impact on employees, particularly those who may struggle to afford health insurance coverage after losing their job. Small employers should be aware of these challenges and consider how they can support their employees during these transitions.
To further support your employees, consider offering comprehensive employee benefits packages.
For small businesses looking to navigate the complexities of health insurance, consulting with insurance experts can provide invaluable guidance.
One option to explore is group health insurance, which can provide coverage to employees at a lower cost than individual plans.
Small businesses might also consider dental and vision plans to enhance their benefits offerings.
Another avenue to explore is QSEHRA and ICHRA, which can provide tax advantages for both employers and employees.
Additionally, offering disability life insurance can provide financial security for employees and their families.
Questions We Get
The questions employers ask us most are answered in full on our resources page.
Unhappy with your current broker? Switch to CFH. Your employees won’t notice. You will.
