
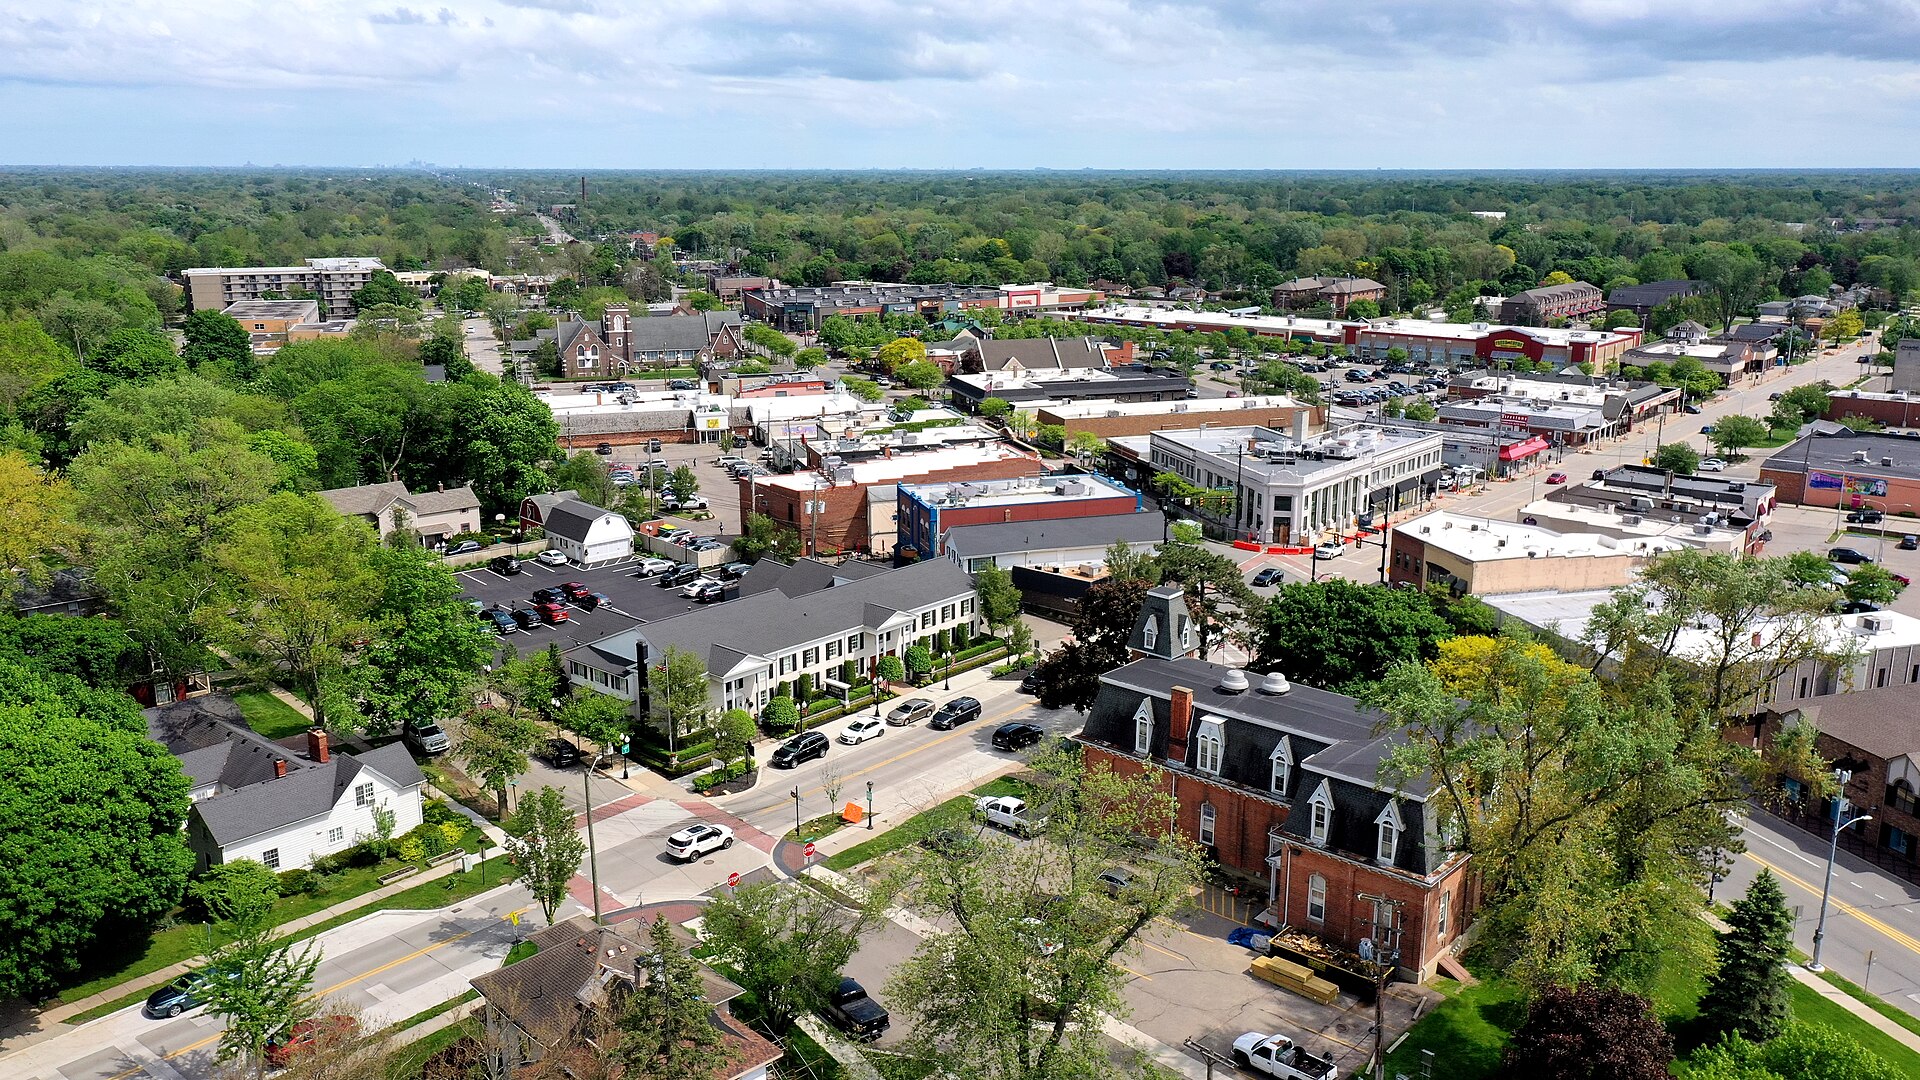
Downtown Businesses Have a Deduction Problem
Restaurants, retailers and service businesses on Grand River deal with variable hours, real turnover and a wage level where the payroll deduction decides whether anyone enrolls at all. Plan richness is rarely the constraint; affordability and eligibility are. When enrollment and payroll are connected through payroll integration, deduction mismatches largely disappear.
A genuinely low-deduction option alongside a richer plan converts waivers into enrollment without costing the employer more, and it makes the group look better to underwriters. A workforce that declines coverage is not a saving; it is an unspent contribution.
Two Farmingtons, One Labor Market
The City of Farmington and Farmington Hills are separate municipalities, and nearly every large local institution — the hospital, the school district administration, the office corridor — is in the Hills rather than the city. For benefits purposes it is one labor market, but getting the distinction right matters when you describe your own location to a carrier or a candidate.
Related: how we help employers improve workforce health and control healthcare costs all year, not just at renewal.
It matters practically too. Corewell Health Farmington Hills Hospital is the nearest acute-care facility, and it has been renamed twice: Botsford until 2014, then Beaumont Farmington Hills, and Corewell Health since 2022. Materials carrying either older name mislead employees.
Plan Structures for Small Farmington Groups
Community-Rated Plans for Small Payrolls
Community rating means a small group is not sunk by one expensive year. Below roughly twenty-five lives it is frequently the best choice, and we will tell you when.
Level Funding for Healthier Small Groups
If a small group is healthier than its pool, level funding stops the subsidy at a fixed monthly cost and can return a surplus. Underwriting is required.
A Low-Deduction Plan Next to a Richer One
A richer plan alongside a genuinely low-deduction plan. In a wage-sensitive downtown workforce this lifts participation more than any contribution increase.
A Fixed Allowance Toward Individual Plans
For a very small employer, a set monthly amount toward coverage each employee chooses can be a legitimate structure. It is not for everyone, and we will say when it is not.
Compliance for Downtown Employers
The Hours Threshold in Writing
Write the hours threshold down and apply it evenly. Inconsistent eligibility is the most common error we find in small groups.
A Cafeteria Plan for Pre-Tax Deductions
Pre-tax premium deductions need a written cafeteria plan document, yet plenty of small employers deduct pre-tax without one.
Counting Across Your Locations
The employer mandate adds up full-time equivalents across commonly owned businesses, so two locations with one owner count as one.
Written Waiting Periods
Put the waiting period and entry date in writing and apply them the same way within each class, and most eligibility disputes never happen.
Common Questions for Farmington Businesses
We have six people. Do we have real options?
More than most expect. Fully insured, level-funded and defined-contribution structures are all available at that size, and the right one depends on your claims history and your staff’s wage range rather than headcount alone.
Half our staff waive coverage. Is that a problem?
Usually it signals the deduction is wrong for the wage. A lower-cost second option often converts waivers into enrollment and improves how carriers see your group.
A Two-Square-Mile Downtown Inside a Larger Suburb
Farmington had 11,597 residents at the 2020 census across about two square miles, entirely surrounded by Farmington Hills. The city government, which includes Farmington Public Safety — a combined police and fire department — is the principal employer inside the city limits, along with the Farmington Community Library’s downtown branch, the city-owned Farmington Civic Theater and the Governor Warner Mansion. Farmington Public Schools serves the city but its administrative offices are on Freedom Road in Farmington Hills. The economy is downtown storefronts, restaurants, a farmers market and the Sundquist Pavilion on Grand River. Corewell Health Farmington Hills Hospital, a 330-bed Level II trauma center and teaching hospital, is in Farmington Hills; it was Botsford Hospital until 2014 and Beaumont Farmington Hills until 2022.
The Big Institutions Are in the Hills
The hospital, the school district offices and the office corridor are all in Farmington Hills. Benchmark against that labor market, but describe your own location accurately.
Botsford, Beaumont, Now Corewell
Three names for one hospital in a decade. Federal provider data still prints the Beaumont name, so old references persist even in official sources.
Downtown Small Businesses
No large private employer sits inside the city. That makes small-group design and documentation the whole of the benefits question here.
Farmington Hills and Oakland County Neighbors
- Employee benefits in Novi
- Employee benefits in Livonia
- Employee benefits in Southfield
- Employee benefits in West Bloomfield
- Employee benefits in Westland
- Employee benefits in Farmington Hills
- Employee benefits in Northville
All Detroit metro cities we serve · Every Michigan city we serve
Plain Answers for Farmington Employers
Can CFH help Farmington employers?
Yes. Farmington restaurants, shops and service businesses use CFH for plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers, and for proper coverage of an account we work in teams of five. A review of your current plan and renewal is the usual first step.
Which hospital is closest to Farmington?
Corewell Health Farmington Hills Hospital, a 330-bed Level II trauma center, is the nearest acute-care facility. It sits in Farmington Hills rather than in the City of Farmington. The hospital was Botsford until 2014 and Beaumont Farmington Hills until 2022, and some official provider records still carry the Beaumont name.
Can you review the renewal if we keep our broker?
Yes. The review costs nothing and changes nothing on its own. We will show what the increase is made of and whether the market has a better answer; if your program is priced correctly, we will say so.
Half your staff waiving coverage every year? See what switching to CFH involves.
Quick Answers for Farmington Employers
Does a Farmington employer have to offer health insurance?
Federal law requires coverage only from applicable large employers, which average 50 or more full-time-equivalent employees. Michigan has no separate state employer mandate, so a Farmington business under that size decides for itself whether to offer a plan. Crossing 50 changes the rules, and our guide to crossing fifty employees walks through what changes.
What counts as affordable coverage for Farmington employees?
For an applicable large employer, the lowest-cost self-only plan generally has to cost an employee no more than 9.96 percent of household income in 2026, rising to 10.22 percent in 2027. Employers usually test this with an IRS safe harbor, and our affordability calculator runs your own wage data against them.
Guides for Farmington Employers
Michigan Health Insurance Broker
How an employee benefits broker works with your Farmington team, from census and market review through renewal.
Companies With 2 to 50 Employees
Plan design, participation rules and cost levers for the smallest Farmington groups.
Companies With 51 to 249 Employees
Funding choices and compliance duties as a Farmington employer grows past 50.
The Renewal Decoder
Read a Farmington renewal line by line before you accept the increase.
Choosing a Benefits Consulting Firm
What to ask any consultant or broker before you sign, with questions Farmington HR teams use.
Self-Funded vs Fully Funded
How the two funding models compare, and which size of Farmington employer should consider each.
All Detroit Metro cities we serve · Every Michigan city we serve
Next Step for Farmington Employers
Send the renewal letter, plan summary, contribution split and enrollment counts by tier, and two more documents at fifty or above, and we will explain what the increase is made of. Call 248.370.8853 or write to info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
