
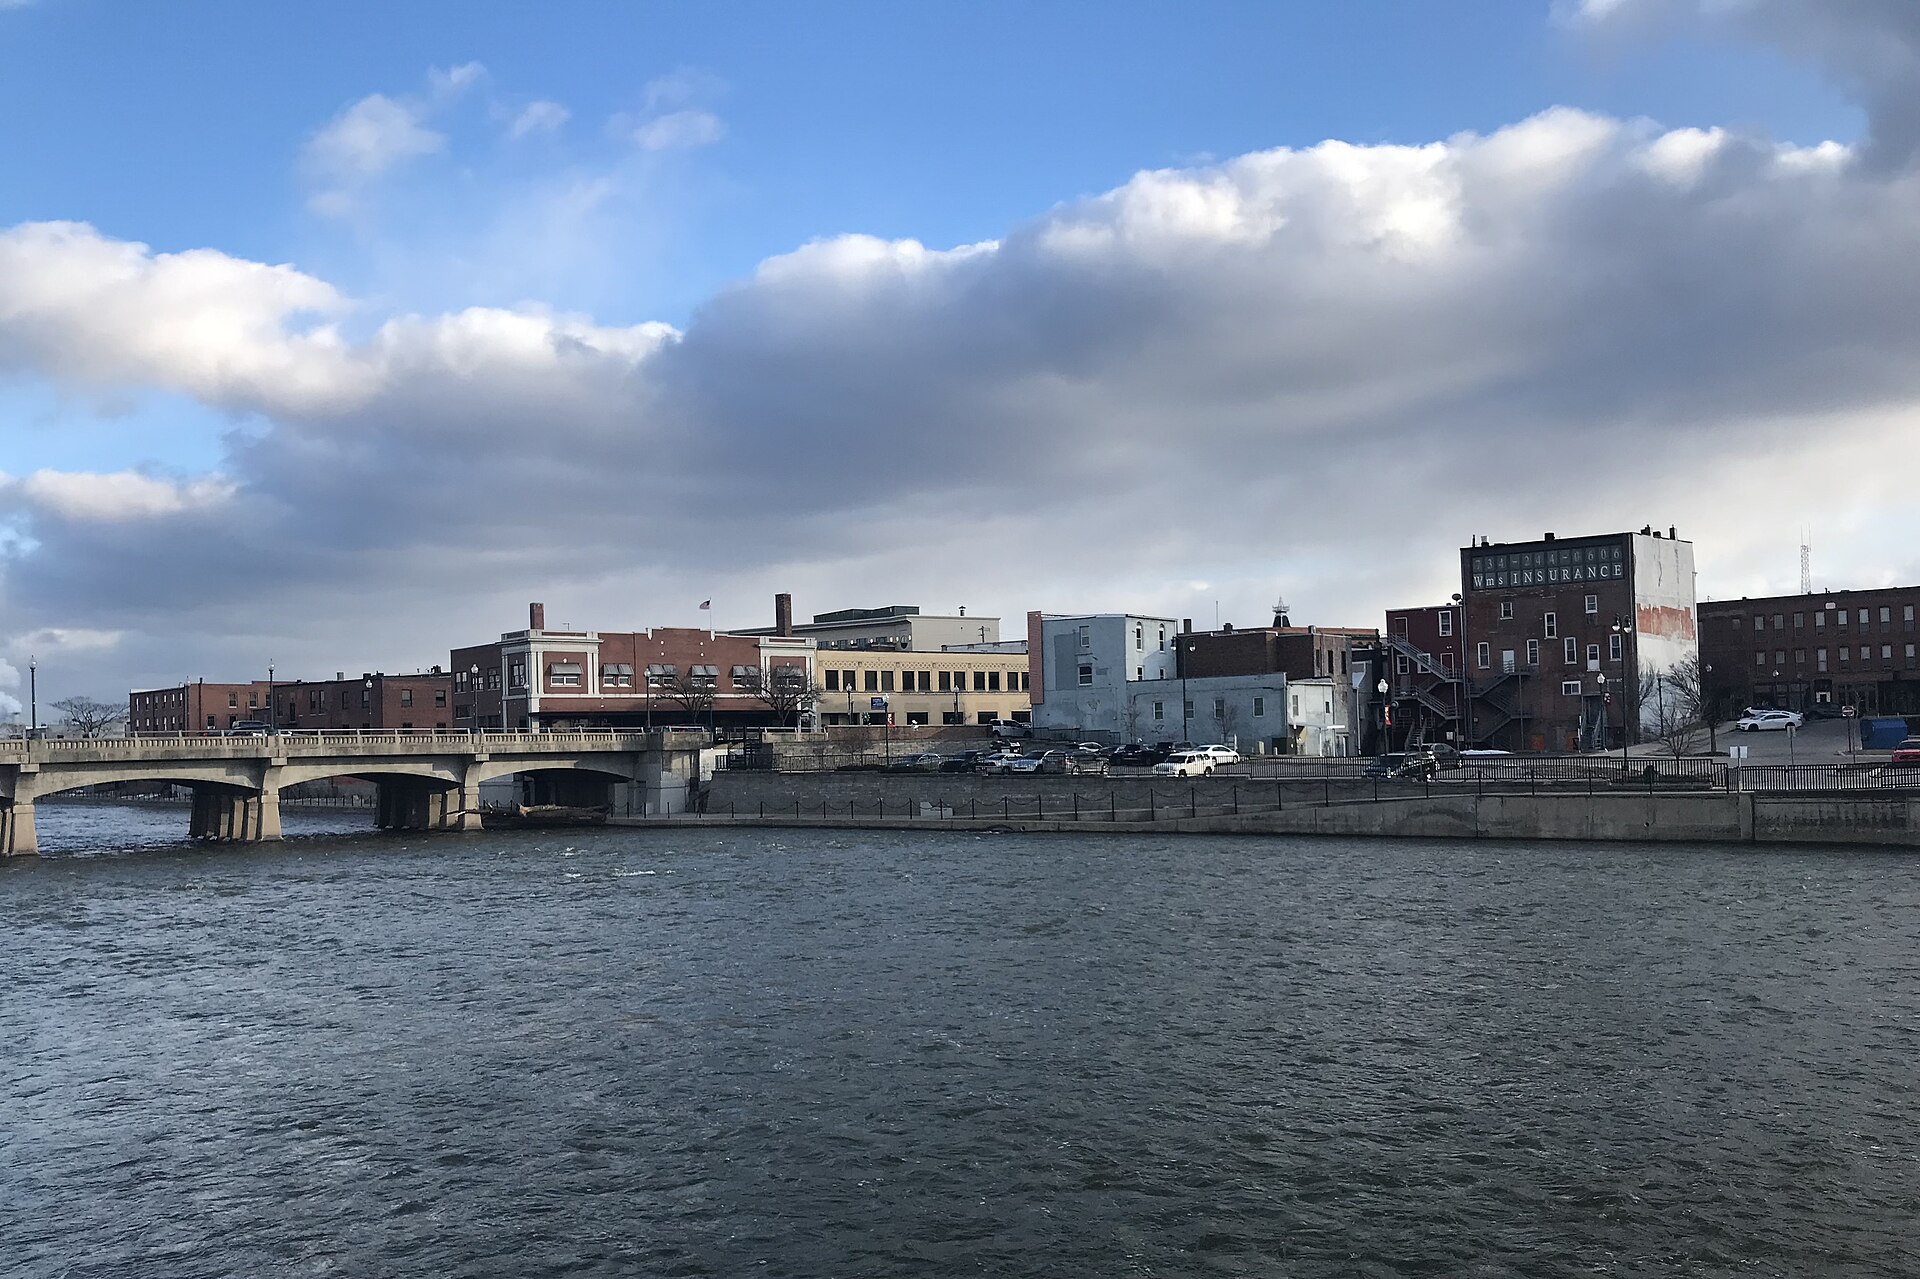
A Workforce That Crosses a State Line
Monroe employers draw from northern Ohio as readily as from Wayne County, and that has a direct benefits consequence: a network built for southeast Michigan may not cover the Toledo hospitals a meaningful share of your employees already use. Coverage follows the employee, not the office.
This is checkable in advance. Pull the home ZIP codes on your census, look at what is in network on the Ohio side, and you will know before enrollment whether you have a problem. Employers usually find out afterwards instead.
Scheduled Change at the Big Employers
DTE has a published plan to close the Monroe coal plant by 2032. ProMedica dropped a planned new hospital in favor of a replacement bed tower and renovation on the existing campus. Neither is an emergency, but both are the kind of long-dated change that reshapes a local supplier base and a local labor market over several renewal cycles.
If rising premiums are the concern, our health and cost strategy shows where cost can move between renewals.
For an employer, the practical response is not to guess at the timeline. It is to make sure eligibility rules, continuation procedures and plan documents are in a state where a headcount change is an administrative event rather than a compliance one.
Funding Options for Monroe Companies
Fixed-Rate Fully Insured Plans
Fixed rate, no claims exposure. Sensible where headcount is uncertain or the claims history is thin, and we will tell you when it is the right call.
Level-Funding With Stable Claims
A fixed monthly cost with claims run through a defined account and a possible surplus return. Suits a healthy group that has been subsidizing worse risks in a pooled rate.
Self-Funding for Larger Employers
Viable from about a hundred lives with a steady record. For a Monroe employer, the attachment points and how a known large claimant is handled matter more than the admin fee.
Multi-State Network
Where a real share of employees live in Ohio, a national network on a level-funded or self-funded chassis usually solves access more cleanly than a regional fully insured plan.
Compliance Points for Monroe Businesses
The Fifty Count Across Your Companies
Full-time equivalents in every commonly owned business decide the mandate, not the staff at one Monroe site.
Affordability for Front-Line Staff
The lowest-cost self-only option has to stay under the annual percentage of the lowest-paid full-time employee’s wage, not the average wage.
Employees Living in Ohio
An employee living in Ohio needs in-network access where they live. Rating and network adequacy both follow the residence.
Form 5500 and Written Plan Documents
A plan with a hundred participants must file a Form 5500 with Schedule A, and needs a wrap document and summary plan description first.
Monroe Employee Benefits FAQs
Half our people live in Ohio. Is that a problem?
Only if the network ignores it. It is a solvable design question — and it is much cheaper to solve before enrollment than after an employee finds their hospital is out of network.
Should we be worried about the plant closure?
Not as a benefits matter, not yet. What is worth doing now is making sure your eligibility rules and continuation procedures would hold up under a significant headcount change, whenever one comes.
A County Seat With a Headquarters and a Power Plant
Monroe had 20,462 residents at the 2020 census and is the seat of Monroe County. ProMedica Monroe Regional Hospital, a 217-bed facility on North Macomb Street, is the area’s largest single employer at roughly sixteen hundred people. La-Z-Boy Incorporated has its world headquarters in the city. DTE Energy’s Monroe generating station is one of the largest coal-fired plants in the country, and the Fermi 2 nuclear station sits nearby in Newport. Gerdau Macsteel produces specialty steel here, Monroe Public Schools employs around a thousand, and the Port of Monroe is Michigan’s only Lake Erie port. County government adds the usual county-seat layer of courts and administration.
Check the Toledo Networks
Monroe sits between two metro areas. A meaningful share of any local census lives closer to Toledo hospitals than to Detroit ones. Home ZIP codes tell you this before enrollment does.
One Hospital in the City
ProMedica Monroe Regional, at 217 beds, is the acute-care facility here. A network that treats it poorly is not a saving for a Monroe workforce.
Long-Dated Change at the Anchors
DTE plans to close the Monroe coal plant by 2032 and ProMedica is rebuilding on its existing campus rather than building new. Both reshape the supplier base slowly rather than suddenly.
Plain Answers for Monroe Owners
Does CFH serve Monroe businesses?
Yes. Monroe manufacturers, energy suppliers, health care employers and service businesses use us for plan design, funding and carrier comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers, and for proper coverage of an account we work in teams of five. We start by reviewing your current plan and renewal.
We have employees living in Ohio. Does that change the plan?
It changes which plans work rather than whether you can cover them. Network access follows where an employee lives, so a Monroe employer with a real share of Ohio residents usually needs a network that covers the Toledo systems properly. We check home ZIP codes against network footprints before comparing prices.
Can CFH review our Monroe plan if we keep our broker?
Yes, free and with no obligation. We will explain the increase and whether your network covers the Toledo hospitals your staff use. If the program is priced right, we will say so.
Half your staff in Ohio and a Michigan-only network? Find out about switching to CFH.
Forward the Monroe Renewal Notice
Send the Monroe renewal letter, plan summary, contribution and enrollment by tier, and two more documents at fifty or above, with a list of employee home ZIP codes. We will check Toledo network access before your next enrollment. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Related Guides
Service Areas
Employee benefits guidance for employers in every region of Michigan we serve.
Small Group Health Insurance Guide for Michigan Employers (2 to 50 Employees)
How small group health insurance works in Michigan and how to compare your options.
Employer Benefits Guides: Eligibility, Plan Design, Life Events and Rules
Our library of plain-English guides on eligibility, plan design and compliance.
