
Benchmarking Answers a Question You Cannot Answer Alone
What Is Worth Comparing
The Employer Share of the Employee-Only Premium
which is the figure candidates weigh first
The Employer Share at Family Tier
where the real money sits and where employers vary most
Deductible and Out-Of-Pocket Maximum
since two plans at the same premium can feel entirely different in use
Whether a Savings Account Is Funded
Whether a savings account is funded by the employer and at what level
Which Lines Are Provided Beyond Medical
and whether the employee pays for them
Waiting Periods for New Hires
which are invisible until a candidate is comparing start dates
What Benchmarking Cannot Do
It cannot tell you what to do. A comparison showing you sit below the median is information, not an instruction — the right response might be to increase the contribution, or to reallocate what you already spend, or to change nothing and explain the position better. Treating a benchmark as a target is how employers end up spending more without improving anything anyone noticed.
Rules In the Background
Above Fifty Full-Time Equivalents
an offer of coverage must also be affordable measured against a federal standard, which is a floor rather than a competitive position
Continuation Coverage for Twenty or More Employees
Michigan law is silent below it.
Waiting Periods for New Hires Are Capped
and the cap is shorter than some older plan documents assume
The Part D Notice for Staff Near Medicare
Staff eligible for Medicare need the creditable-coverage notice by mid-October
Where the Money Actually Goes in a Small-Group Renewal
When a renewal arrives with a double-digit increase, the number is rarely one thing. It is usually three: the carrier’s trend assumption for the coming year, your own claims experience to the extent the carrier gives it weight, and any change in who is enrolled. Separating those three is the difference between negotiating and accepting.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
Trend is the carrier’s view of medical and pharmacy inflation, and it applies whether your group had a quiet year or not. Experience is your actual claims, and how heavily it counts depends on your size — a small group’s claims are statistically noisy, so carriers blend them with pooled data. Enrollment change is the quiet one: a few family-tier additions or an older hire can move a renewal without anyone being sick.
Ask the carrier to show which of the three is driving the increase. A renewal built mostly on trend is a market conversation, and worth shopping. One built on your own claims is a plan-design and pharmacy conversation.
The Questions Worth Asking Before You Change Carriers
Moving carriers to chase a lower rate can work, and it can also cost more than it saves. Before deciding, confirm the things that are expensive to discover later: whether the physicians and hospitals your employees use are in the new network, how prescriptions currently being filled sit on the new formulary, whether anyone mid-treatment will face a break in authorization, and what the new plan’s deductible credit rules are if you switch mid-year.
Also ask what the quoted rate is contingent on. A quote assuming a participation level you will not hit, or a contribution percentage you do not currently pay, is not the rate you will get.
Benchmarking Questions From Berkley Employers
How do we know what other employers actually pay?
Through survey data matched to your size, sector and region rather than through anecdote. The anecdote is usually wrong in both directions.
We are below the median. Should we increase our contribution?
Only if that is where the money does the most good. Sometimes funding a savings account or fixing the family tier achieves more than moving the headline figure.
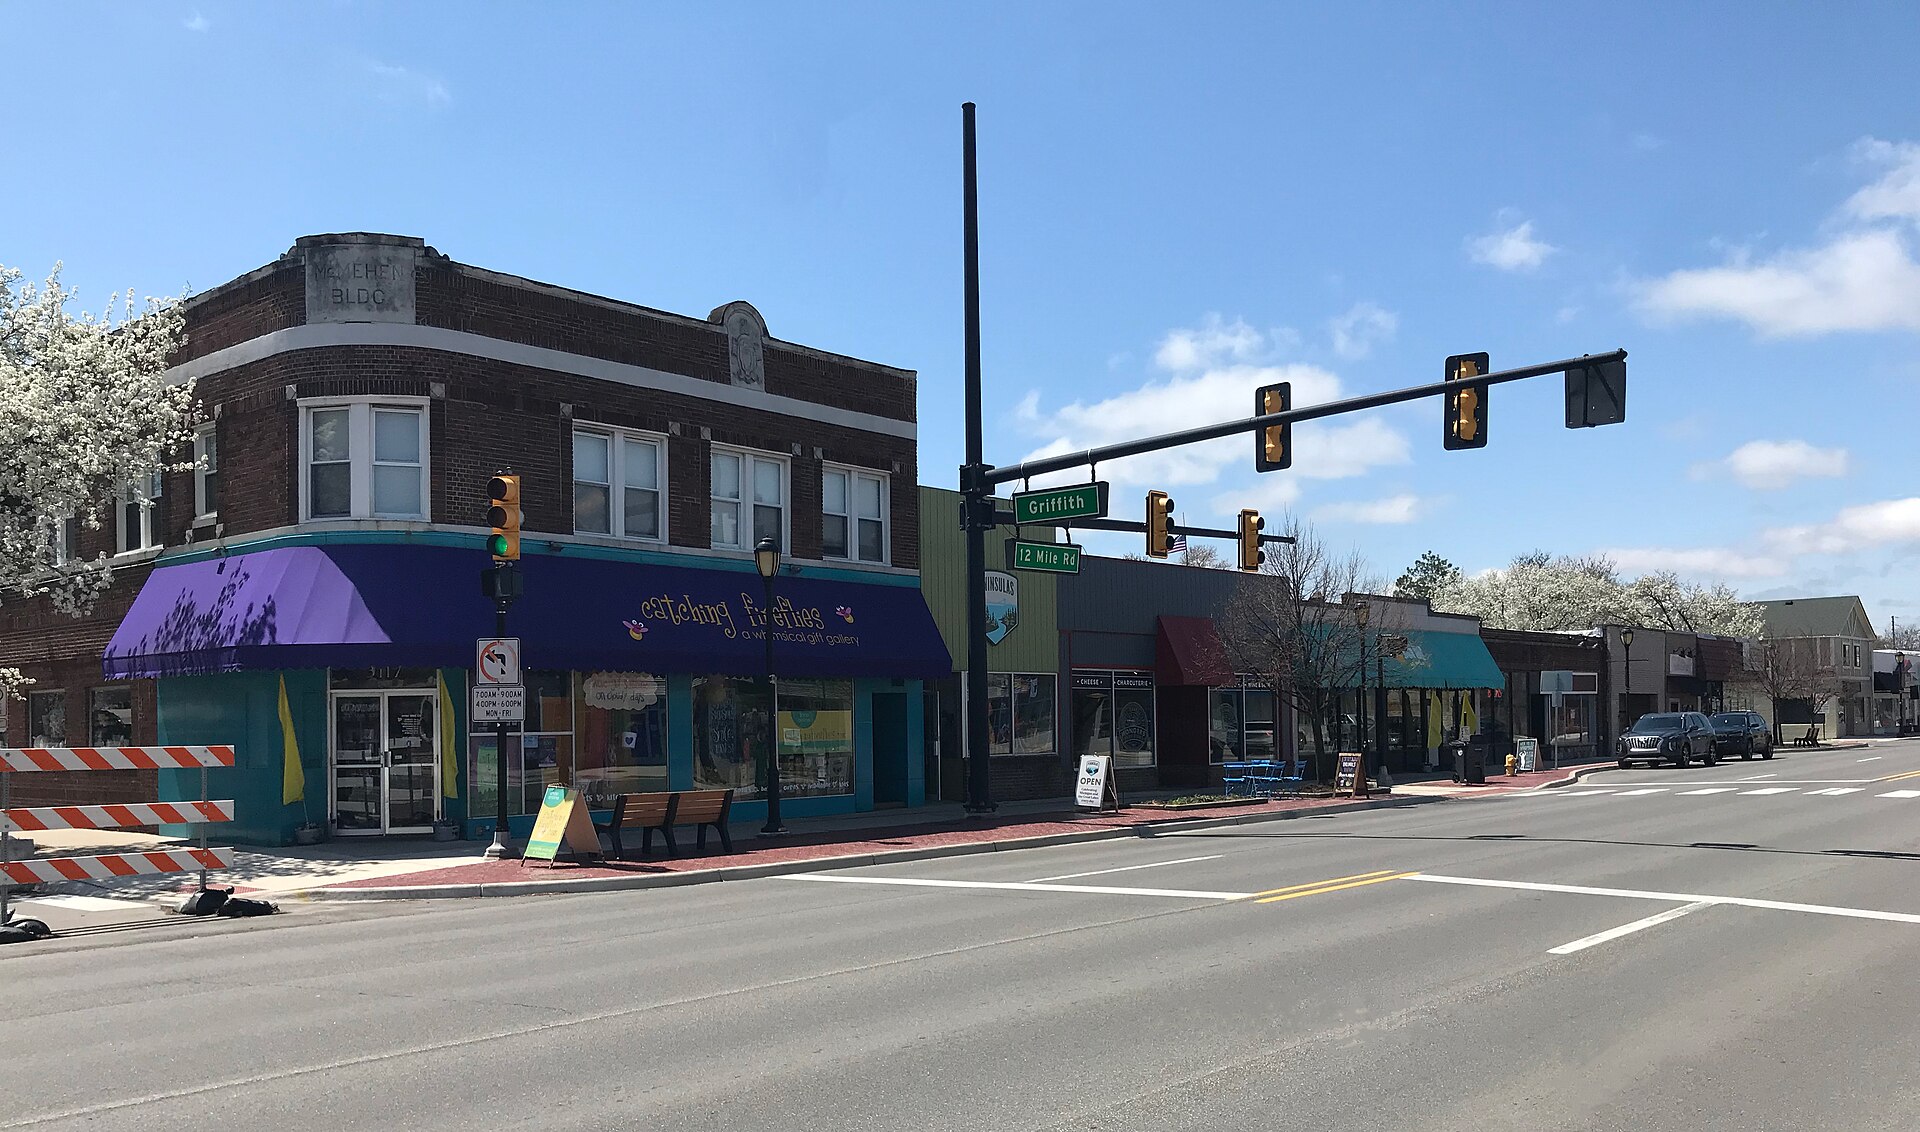
Main Street Businesses Along Twelve Mile
Berkley is an Oakland County city of 15,194 residents (2020 census) on 2.61 square miles, about 14 miles northwest of downtown Detroit. Woodward Avenue forms its eastern edge, with I-75 and I-696 nearby, and it borders Royal Oak, Southfield, Oak Park and Huntington Woods. Berkley School District is the city’s principal employer, with 718 employees as of 2021. Downtown runs along Twelve Mile Road and Coolidge Highway with restaurants, boutiques and retail shops, and the city hosts CruiseFest the day before the Woodward Dream Cruise. Corewell Health William Beaumont University Hospital is close by in Royal Oak. With mostly small local businesses and commuting residents, benefits here hinge on small-group pricing and Oakland County networks.
Confirm Royal Oak Hospital Coverage
Corewell Health William Beaumont University Hospital in Royal Oak is the nearby hospital for many Berkley families. We check that it and the Corewell Health primary care doctors your staff use are in network, and we compare how plans treat other Oakland County systems. We also flag any gaps before renewal.
Price Benefits for Restaurants and Retail
Downtown restaurants and shops often run on thin margins with part-time and variable-hour staff. We explain eligibility rules, look-back measurement for variable hours and affordability testing, and we model contribution levels so full-time employees get a plan they can afford. We also explain how waiting periods apply to new hires and seasonal staff. Most enrollment errors start at hiring, which is why onboarding and benefits eligibility should run from the same record.
Consider ICHRA for Small Storefronts
A boutique or salon with a few employees may not meet group participation rules. We compare a small group plan with an individual coverage HRA, which lets each employee choose an individual plan while the owner sets a fixed monthly allowance and knows the cost.
Compete With School District Benefits
The school district’s benefits set expectations for local job seekers. We benchmark your deductibles, contributions and dental, vision, life and disability options, and we explain practical ways a small Berkley employer can offer a competitive package without taking on unpredictable costs. We also show where voluntary coverage fits.
Answers for Berkley HR Managers
Does CFH advise small businesses in Berkley?
Yes. We advise Berkley employers on plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. As licensed insurance brokers we review cost, plan performance, risk and administration together, usually starting with your current plan and renewal.
No idea whether your package is competitive or just expensive? See how switching to CFH works.
Let Us Benchmark What You Have
Send the renewal letter, plan summary, contribution by tier and enrollment by tier, plus two more documents at fifty or more, and we will benchmark what you offer. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
