
A Long-Tenured Workforce Reads a Plan Change Differently
Someone three years into a job evaluates a new plan on its merits. Someone twenty years in evaluates it against every previous change and against what they believe they were promised. If a deductible rises, the question in the room is not what the deductible is; it is whether the business is in trouble, or whether this is the first of several.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
That reaction is reasonable and it is manageable, but only if the change is explained by someone willing to say what is actually driving it.
What Makes a Plan Change Land
Explain the Cause Honestly — a Claims Year
a market trend, a carrier withdrawal — because a change presented without a reason invites people to invent a worse one
Show the comparison in whole dollars per pay period at each tier
not as percentages, since percentages read as evasion
Name What Is Not Changing
which is usually most of it and is what people actually want to hear
Say What Was Considered and Rejected
which demonstrates the decision was made rather than accepted
Give People Somewhere to Ask Afterward
since the questions arrive two days later rather than in the meeting
And Do Not Let the First They Hear Be the Deduction
The single most damaging way to change a plan is to let an employee discover it in a payslip. It converts a defensible business decision into something that feels concealed, and the goodwill lost is out of all proportion to the money involved.
Rules That Travel With a Plan Change
Anyone on continuation coverage moves with the plan when it changes
and should be told on the same schedule as active employees
A plan change is not itself a qualifying event permitting other election changes
which is worth stating clearly in advance
Continuation Coverage Kicks In at Twenty
Michigan adds no smaller-group rule beneath it.
The Creditable-Coverage Notice Is Due Before Mid-October
and a drug benefit change is precisely what that notice is about
What Manistee County Employers Ask About Plan Changes
How far ahead should we tell people?
Before enrollment opens rather than as part of it, so the news and the decision are separate events. Two to four weeks of daylight is usually enough.
Should we explain the cost pressure honestly?
Yes. In our experience employees handle a real reason considerably better than they handle silence.
Salt, Paper and Lakefront Tourism in Manistee
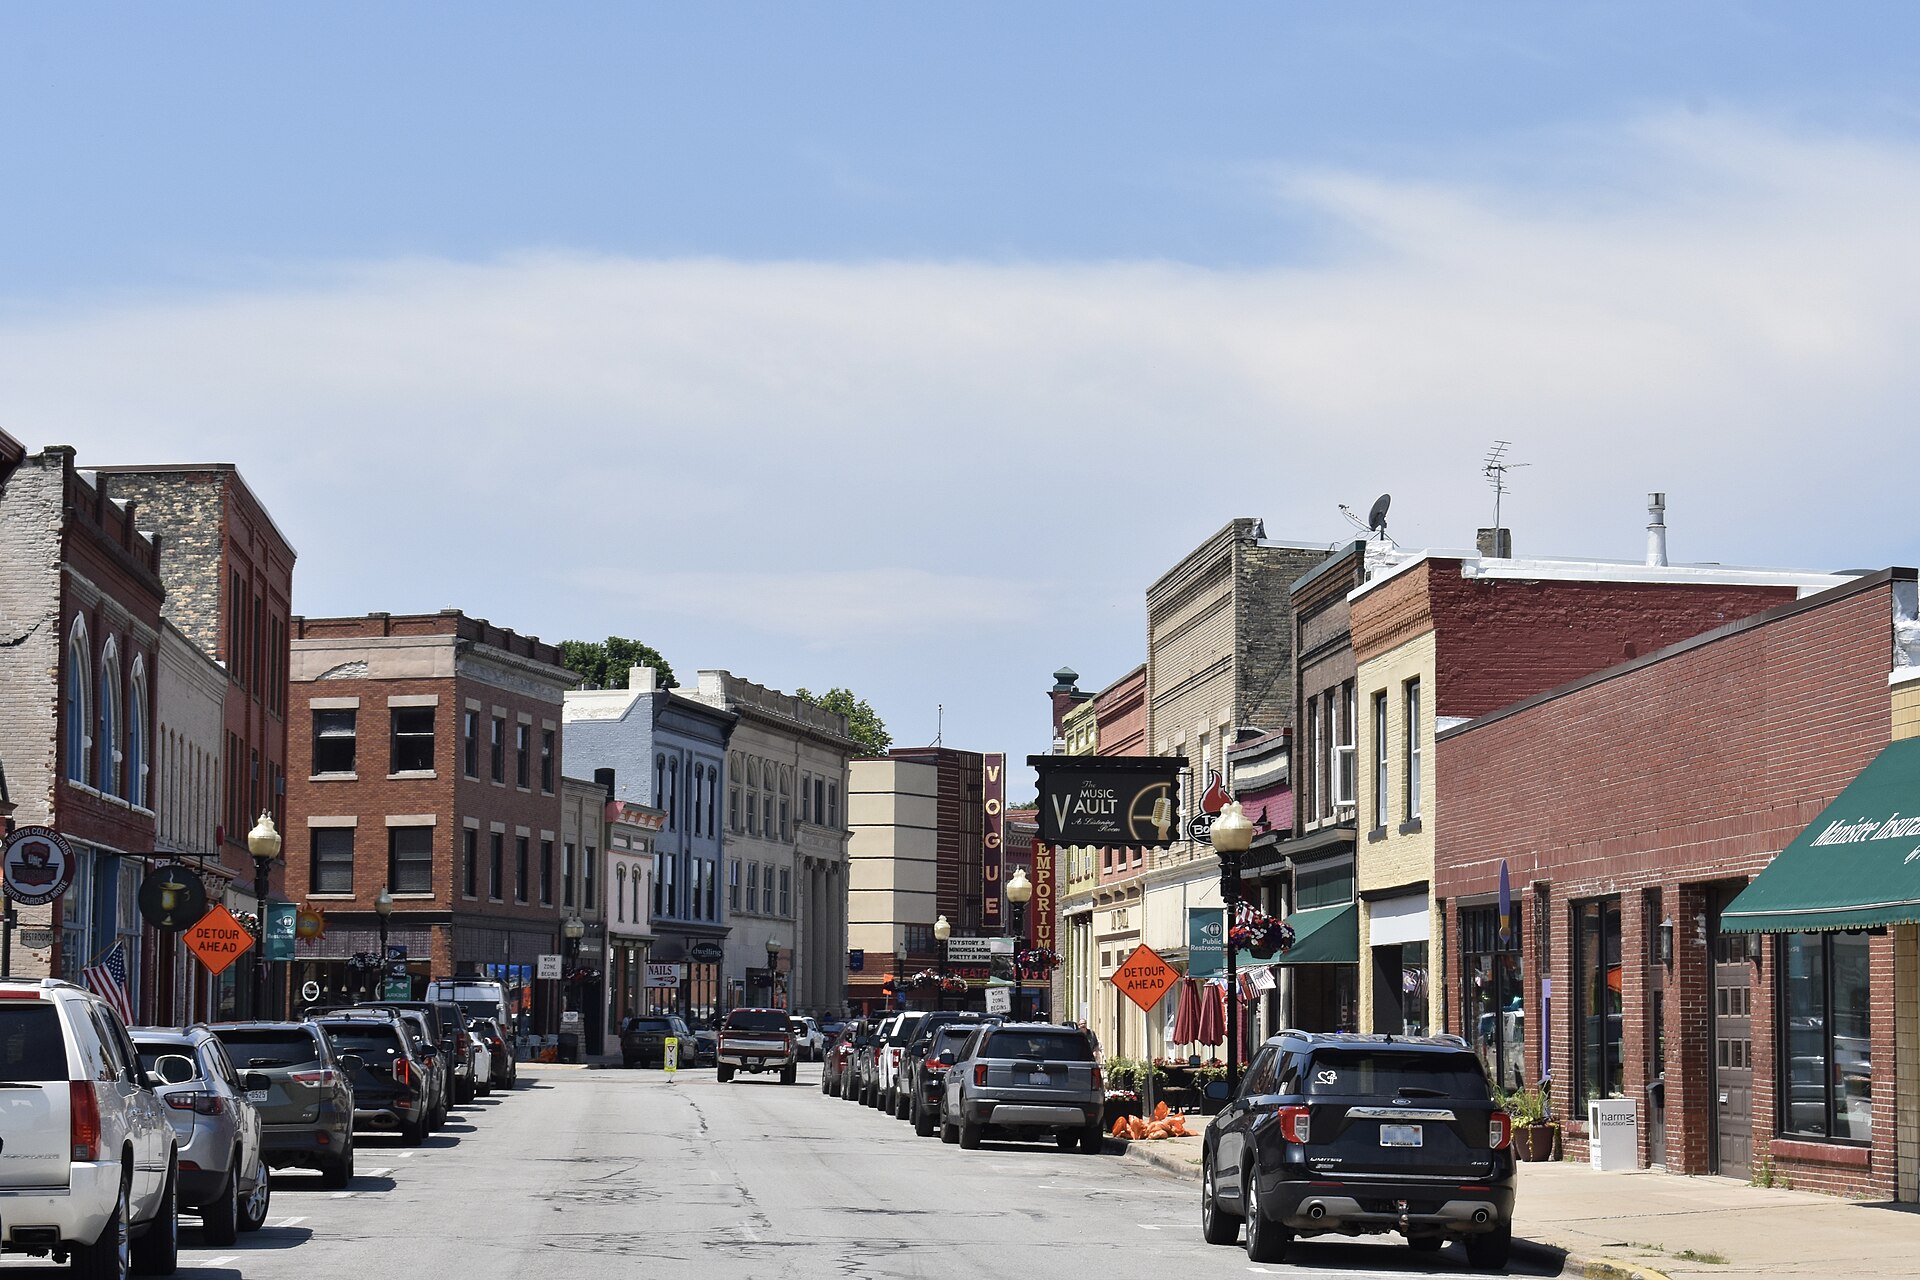
Manistee is the county seat of Manistee County, with 6,259 residents at the 2020 census. The city sits on an isthmus between Manistee Lake and Lake Michigan, with the Manistee River running through it. Nicknamed the Salt City, it is home to Morton Salt, Packaging Corporation of America and Martin Marietta, and the Little River Casino Resort is about five miles northeast. Tourism and fishing also support the local economy. Munson Healthcare Manistee Hospital provides emergency care, cancer and infusion services, surgery, orthopedics and women’s health, and belongs to Munson Healthcare’s eight-hospital system. Industrial plants, hospitality and healthcare each bring different schedules and pay levels, which shapes how Manistee employers should set up their benefits.
Use the Munson Network Well
Manistee Hospital is part of Munson Healthcare, whose larger hospitals handle more complex care. We check that Manistee Hospital and the Munson facilities employees are referred to are in-network, so a referral for specialty care does not become an unexpected out-of-network bill. We also explain how referrals and prior authorizations work on each plan.
Set Rules for Seasonal Hospitality
Tourism and casino hospitality bring seasonal and variable-hour staff. We help you write eligibility and waiting-period rules that follow ACA measurement requirements, so part-time and seasonal employees are handled consistently and full-time staff keep coverage through the slower months. Clear written rules also make hiring conversations easier each spring.
Protect Industrial and Physical Jobs
Salt production, paper packaging and aggregate operations involve demanding physical work. We compare short-term disability, long-term disability and group life coverage so employees have income support for off-the-job injuries and illnesses, which workers’ compensation does not cover. We explain the waiting periods and benefit levels in plain terms for employees.
Give Small Employers Real Options
Many Manistee businesses are small groups with limited budgets. We explain ICHRA, level-funded plans and traditional small-group coverage in plain terms and compare them side by side, so you can offer meaningful health benefits without taking on more risk than you can manage or more administration than your office can handle.
Other Manistee Questions
Do you work with employers as far north as Manistee?
Yes. For Manistee employers we cover plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers who look at the whole benefits program, from cost and plan performance to risk and administration, and we usually start with your current plan and renewal.
Twenty-year employees and a plan change nobody explained? See how switching to CFH works.
Let Us Help You Present It
Hand us the renewal letter, plan summary, contribution split and enrollment by tier, and two more documents if you have fifty or more on staff, and we will tell you what the increase really contains. Call 248.370.8853 or email info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
