
More Residents Over Sixty-Five Than Under Eighteen
Wyandotte is older than the communities around it, and the census says so plainly. Just over eighteen percent of residents are sixty-five or older while a little over nineteen percent are under eighteen, which is close to parity and unusual for this region. The average household holds 2.27 people. Nearly three-quarters own their home. Median household income runs near seventy-two thousand dollars, the highest in this group of Downriver cities, and only about five percent of residents under sixty-five lack coverage.
Employers looking beyond the next quote can start with our health and cost strategy for fully insured plans.
What that profile describes is a settled, long-tenured workforce. People here tend to stay in a job and stay in the city, and an employer’s payroll skews toward employees in their forties, fifties and sixties rather than toward new entrants.
Medical plan design for an older group is well-trodden ground. What tends to go unexamined is everything else in the package, and specifically the line that matters most to a fifty-eight-year-old with a mortgage and a spouse: life insurance.
Group Life Is the Benefit Nobody Reads Until It Matters
Almost every group benefits package includes some employer-paid group term life, usually a flat amount or a multiple of salary, and almost nobody looks at it after the first enrollment. It is cheap, it is uncontroversial, and it is the one benefit whose value is only ever tested when the employee is no longer there to ask questions about it. Pay and benefits compete for the same budget, which is why a total rewards strategy looks at them together.
The common design is one times salary, which sounds reasonable and is generally inadequate. For a household carrying a mortgage on a home valued near a hundred and sixty-seven thousand dollars, a single year of income does not retire the debt or bridge the survivor to anything. Two or three times salary costs meaningfully less than the difference suggests, because group term life is priced on the whole group rather than individually and the incremental cost of a larger multiple is small.
The other half of the question is whether employees can buy more on their own. Voluntary or supplemental life offered through the group, with a guaranteed issue amount that requires no medical questions at initial eligibility, lets an employee cover their actual situation at group rates. That guaranteed issue window is genuinely valuable and it generally does not come back. An employee who declines at first eligibility and wants coverage three years later will usually have to answer health questions, and in a workforce this age that is not a formality.
The Fifty Thousand Dollar Line and the Tax Nobody Expects
Employer-paid group term life is tax free to the employee up to fifty thousand dollars of coverage. Above that line the value of the excess coverage becomes imputed income, taxable to the employee and reportable on their W-2, calculated from a federal rate table rather than from what the employer actually pays.
The detail that catches employers is that the table is age-banded and the rates climb steeply with age. The same coverage that generates a trivial amount of imputed income for a thirty-year-old generates many times that for someone in their sixties. On a payroll weighted the way Wyandotte’s is, a generous life benefit can quietly put a noticeable taxable amount on the W-2 of exactly the long-serving employees the employer most wants to look after, and the first anyone hears about it is a question in January.
None of this is a reason to keep the benefit small. It is a reason to tell people. An employee who understands that a line on their W-2 reflects valuable coverage their employer is paying for reads it as a benefit. An employee who discovers an unexplained amount on their tax form reads it as a payroll error, and the goodwill the benefit was meant to buy is spent arguing about it. The same rule reaches employer-paid coverage on a spouse or dependent above a much lower threshold, which is the version employers miss most often.
Age Reductions, Conversion and Portability
Three provisions in a group life contract decide what the benefit is actually worth to an older workforce, and all three sit in the part of the certificate nobody reads.
The first is the age reduction schedule. Most group life policies reduce the benefit at a stated age, commonly a cut at sixty-five and a further cut at seventy. An employee who believes they hold two times salary may hold appreciably less than that by the time it is claimed, and the reduction is rarely mentioned again after the day the plan was installed.
The second and third are what happens when employment ends. Conversion rights let a departing employee convert group coverage to an individual policy without medical questions, usually within a short window measured in days rather than months. Portability, where it is offered, lets them keep term coverage at group-like rates instead. These matter enormously in a city where people retire out of long-tenured jobs, and the window is easy to miss precisely because it opens at a moment when everybody is thinking about other things. An employer who mentions conversion and portability in the exit conversation, rather than burying it in a packet, is doing something genuinely useful at no cost whatsoever.
A City That Owns Its Own Utility
Wyandotte runs its own electric and water utility through Wyandotte Municipal Services, which is an unusual arrangement in Michigan and makes the city itself a substantial local employer with a public-sector benefits package attached.
That matters to a private employer here for a reason that has nothing to do with electricity. When a skilled tradesperson in this city weighs an offer, the comparison in their head is frequently a municipal one, and municipal packages are traditionally strong on exactly the things private small-group plans treat as afterthoughts: defined benefits that do not change with the market, life cover that is not the minimum, and a deductible that has not moved in years.
A private employer cannot always match that and does not need to. What they need is to know that is the comparison being made, and to be deliberate about which parts of their package are competing. Losing a candidate on the medical deductible is one problem. Losing them because nobody mentioned that the life benefit is three times salary and portable is a different and much more fixable one.
The Hospital Is the Neighbor
Henry Ford Wyandotte Hospital sits on Biddle Avenue inside the city, which puts Wyandotte in a position most Downriver communities do not share. It is the anchor facility for this stretch of the river and it is where a large share of local employees are actually treated, often without giving the choice much thought.
The convenience is real and it carries one risk worth naming. When almost everybody uses the same facility, a plan change that moves that facility to a worse tier does not inconvenience a few people, it lands on the entire payroll in the same month. Network disruption that would be absorbed quietly in a city with four competing systems becomes a single, highly visible event here. Before any carrier change, the first thing to confirm is how the new network treats the hospital at the end of the street, and the second is what it does to the physician groups practicing there, which do not always follow the building.
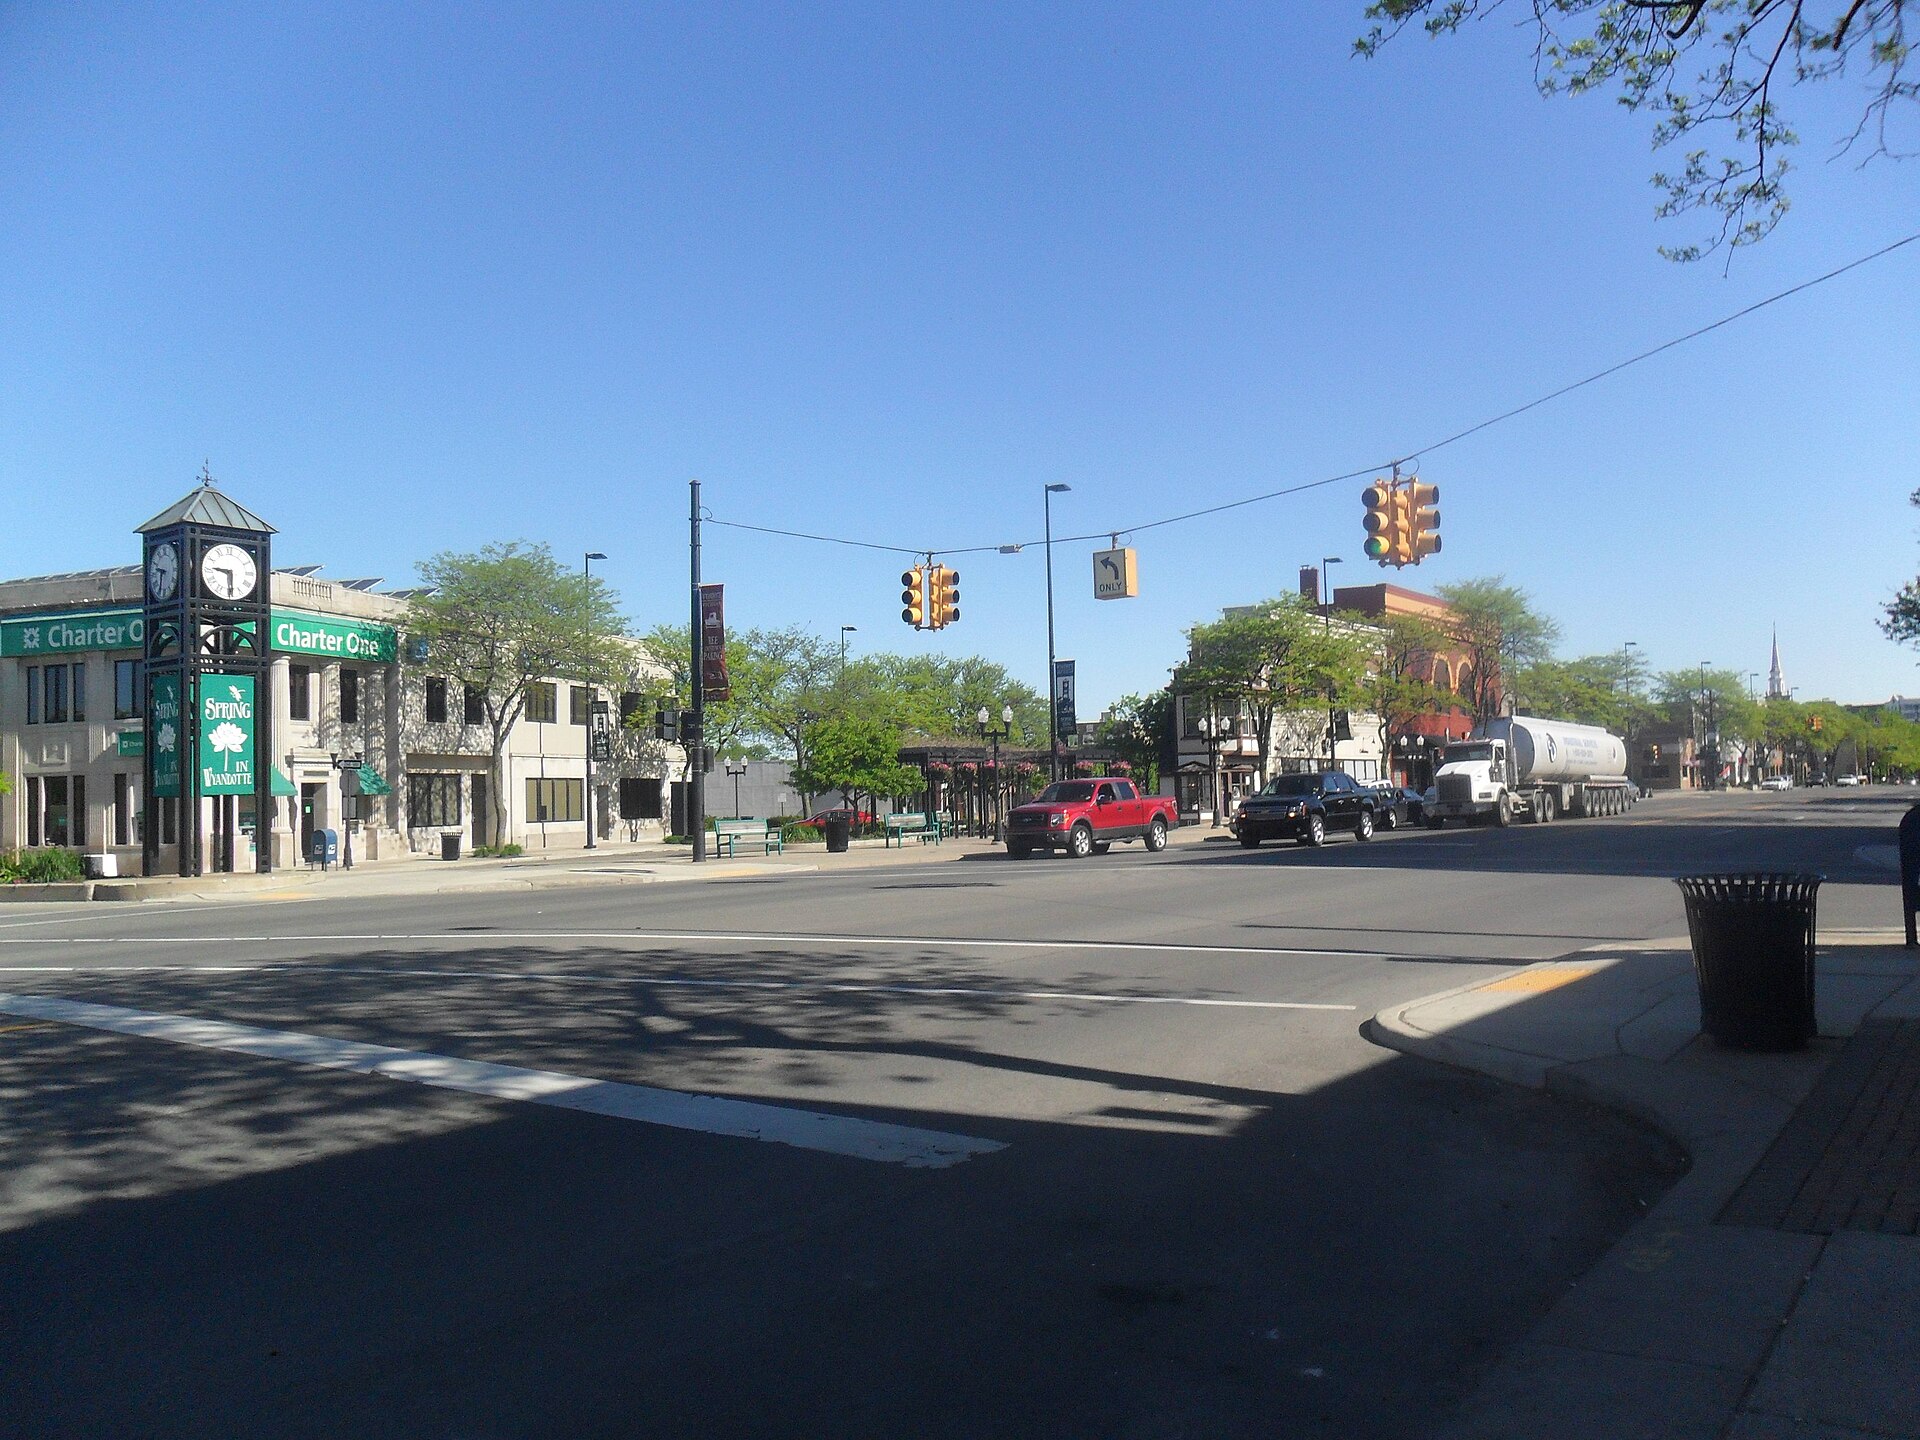
The rest of Wyandotte’s profile is what its history suggests: a riverfront industrial base, a walkable downtown grid, a twenty-four minute average commute and a workforce that mostly stays put. For an employer, a payroll that does not turn over is the easiest kind to plan benefits for and the most expensive kind to lose people from, which is the argument for spending the modest amounts that the non-medical lines actually cost.
Wyandotte’s Industrial and Public Employers
Wyandotte is the exception Downriver: a city of about 24,000 with two genuinely large employers inside it. Henry Ford Wyandotte Hospital is a 360-bed acute care hospital with more than 2,300 employees — the health system itself calls it one of the biggest employers in the city. BASF runs five production facilities here, with 1,114 employees plus 34 contractors as of year-end 2025.
Add Wyandotte Public Schools (about 797 staff across nine schools) and Wyandotte Municipal Services, and the picture is unusual. Wyandotte owns and operates its own electric utility, water treatment plant and cable headend — the only community in Michigan that does all three — including a 70 MW city-owned power plant.
What that means in practice: this is real large-group and collectively-bargained benefits territory, not the small-employer market most of Downriver represents. Median household income is $71,987, the highest of the Downriver cities we serve. If you are a supplier or contractor competing for staff against a 2,300-person hospital and an 1,100-person chemical plant, your benefits package is being compared against theirs.
What Wyandotte Companies Want to Know
Does CFH advise employers based in Wyandotte?
Yes. We advise Wyandotte employers on plan design, carrier and funding comparisons, renewal negotiation, compliance and enrollment. We are licensed insurance brokers who review cost, plan performance, risk and administration as a whole, and we often start with your current plan and renewal.
Group life nobody has read since it was set up? See how a switch to CFH works.
Let Us Review the Whole Package, Not Just the Medical
Send the renewal letter, plan summary, contribution by tier and enrollment by tier, plus two more documents at fifty or above, and your life schedule, and we will review the whole package. 248.370.8853 or info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
