
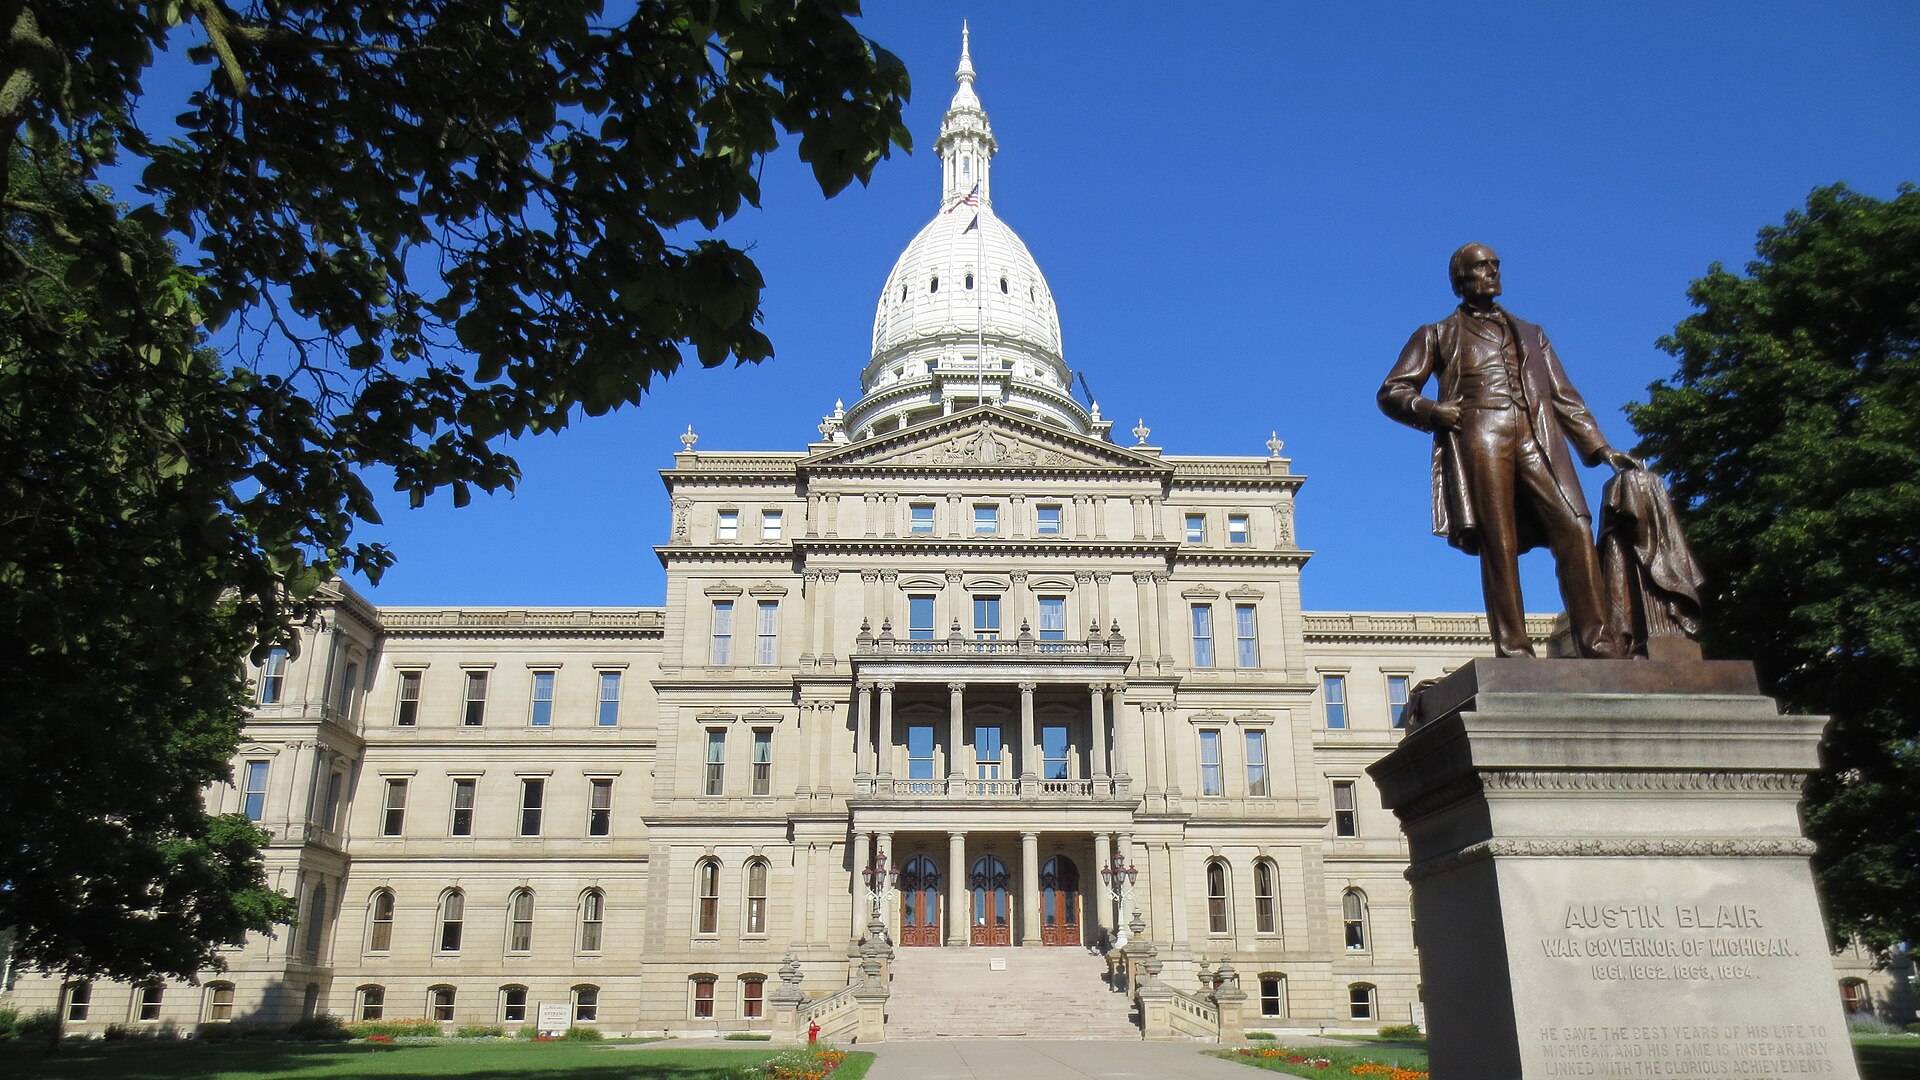
Written for Lansing-area employers by CFH Insurance Consultants
This guide covers what a Capital Region employer should compare before a renewal: plan types and funding, how Michigan-based and national carriers differ, where QSEHRA and ICHRA fit, the compliance items that come with each, and which supplemental benefits earn their cost. For a closer look at where premium goes, see our piece on group health insurance costs, or the full list of employee benefits we advise on.
Plan Types Open to Lansing Employers
Most Lansing groups choose among four designs: HMO, PPO, EPO and a high-deductible plan paired with a health savings account. The choice decides how employees reach specialists, what they pay at the counter and which Ingham, Eaton and Clinton County providers they can use without a penalty. Our notes on group health insurance costs compare them in more detail.
How the Four Designs Differ
An HMO routes specialist care through a primary care referral and keeps members in network, which holds premium down. A PPO pays something out of network and charges for that freedom. An EPO drops the referral but keeps the network rule. A high-deductible plan with an HSA lowers premium and gives employees a pre-tax account; whether it helps them depends on how much the employer puts in the account.
What to Line Up Side by Side
Compare premium, deductible, copays, coinsurance, the drug formulary, wellness incentives and whether the Lansing hospitals your staff use are in network. Your own enrollment and claims data will show which of those matters most for your group; a generic ranking will not.
Why Small Capital Region Employers Still Buy Group Coverage
For a Lansing business with a few dozen people, a group plan spreads risk across the whole group, opens broader networks than most individual policies and signals stability to candidates comparing you with public employers. More on how we approach employee health benefits for small groups.
Keeping Cost and Satisfaction in Balance
Small groups rarely win on premium alone. The better lever is design: where the deductibles sit, how much the employer pays toward dependents, and whether the network covers the providers employees already use. A benefits consultant should price those choices against your census before recommending one.
Tax Treatment of Employer Premium
Employer premium contributions are generally deductible as a business expense, and employee contributions can come out of pay pre-tax under a written Section 125 plan. HSAs and FSAs attached to the plan add their own tax advantages for employees.
Who Quotes Lansing, and What Changed in 2026
Blue Cross Blue Shield of Michigan, Priority Health and the national carriers all quote Lansing groups. Which network fits depends on where your people receive care: University of Michigan Health-Sparrow, McLaren Greater Lansing, or the practices around them.
The Local Plan That Closed
Physicians Health Plan, the Lansing-area insurer later renamed U-M Health Plan, ended coverage at the end of 2025 after covering roughly one in six area residents. Employers that were on it have had to move carriers for 2026, and many are still finding out what the move did to their doctors and their rates. The time to check is before the next renewal, not at it.
What a National Carrier Offers
National carriers bring multi-state networks, which helps if you have remote staff or employees who travel. They may be less flexible on local contracting, so which one fits depends on where your people actually live and receive care.
QSEHRA and ICHRA for Lansing Businesses
A QSEHRA or an ICHRA lets an employer reimburse individual premiums and qualified expenses tax-free instead of sponsoring a group plan. For some Lansing employers with scattered or part-time staff, that is the cleaner answer. The rules are strict, and our employer healthcare compliance services cover them.
Employees Choose Their Own Plan
With a QSEHRA or ICHRA, each employee picks an individual plan, so a single parent and a young single employee can each buy what suits them.
A Fixed Budget for the Employer
The employer sets the allowance, so there is no renewal increase to absorb. A QSEHRA is limited to employers under fifty full-time employees with no group plan; an ICHRA works at any size and allows different allowances by employee class. Both have to be set up to meet federal health mandates.
Compliance Items for a QSEHRA or ICHRA
Reimbursement arrangements keep their tax treatment only if the eligibility, documentation and notice rules are followed. Lansing employers who set one up casually tend to discover this at audit.
Who Qualifies and What to Keep on File
Confirm you meet the size and no-group-plan tests for a QSEHRA before offering it. Keep the plan document, proof that each employee has qualifying coverage, and a record of every reimbursement.
The Written Notice to Employees
Each eligible employee must get a written notice before the plan year, or before they become eligible, stating the allowance, the terms and how to claim. Late or missing notices are a common failure.
QSEHRA or ICHRA: Choosing for a Capital Region Firm
The right arrangement turns on headcount, how varied the workforce is and how much administration you can take on.
Headcount and Workforce Mix
A small Lansing firm with a similar group of employees often does well with a QSEHRA. A larger or more varied employer, for example one with salaried and hourly staff, usually needs an ICHRA’s classes to set different allowances.
What Your Employees Want
A short survey or a look at how employees use the current plan shows whether they would value choosing their own coverage or would rather keep a group plan with a familiar network.
Supplemental Benefits Worth Adding in Lansing
Dental, vision, life and disability cover gaps a medical plan leaves. See our overview of dental and vision insurance and other ancillary lines.
Why Supplemental Lines Earn Their Cost
Supplemental lines cover preventive dental and eye care, orthodontics and income if an employee cannot work. For a modest cost they make the whole package look more complete next to a public-sector offer.
Recruiting Against Public Employers
State and university jobs come with full benefit menus. A private Lansing employer that offers dental, vision and disability alongside medical removes an easy reason for a candidate to choose the public job.
Michigan Market Trends That Affect Lansing Plans
Carrier pricing, hospital consolidation and state rules all shift from year to year, and a Lansing plan that was right three renewals ago may not be right now.
Cost Containment in Practice
Employers are using level funding, telehealth, steering to lower-cost sites of care and closer review of pharmacy terms to slow cost growth without cutting coverage.
None of these is a one-time fix; each needs checking at every renewal.
The Move to Level Funding
Level-funded plans charge a fixed monthly amount and may return a surplus after a good claims year. They are increasingly common among mid-Michigan groups of twenty-five or more with stable claims.
State Rules That Touch Lansing Group Plans
Michigan’s Department of Insurance and Financial Services reviews small-group rates and enforces state mandates on insured plans. Changes in either can alter plan design or reporting duties.
Documents and Reporting
Keep plan documents, summaries and employee notices current with each change. Out-of-date documents are one of the most common findings in any benefits review.
Design and Cost-Sharing Rules
Rules on telehealth, mental health parity, drug coverage and out-of-pocket limits all shape what a Lansing plan may include and how it shares cost.
What Lansing Employers Are Changing
Capital Region employers are simplifying enrollment, using more technology and paying closer attention to which local providers their people use.
Online Enrollment and Self-Service
Online enrollment, self-service portals and plan comparison tools cut paperwork and help employees pick the right plan, provided someone still answers questions in person.
Working With Local Providers
Knowing which Lansing health systems and physician groups your staff rely on lets us pick a network that fits. To talk it through, use our contact page.
Other Mid-Michigan Cities We Cover
We also work with employers elsewhere in mid-Michigan. See our pages for East Lansing employers, Flint and Genesee County, Battle Creek along I-94, and Jackson.
How Lansing’s Economy Shapes Benefits Planning
Lansing is the state capital and sits mostly in Ingham County, with parts in Eaton and Clinton. Government, education, health care and auto manufacturing drive employment, and Michigan State University next door in East Lansing supplies a large educated labor pool.
State employees and contractors expect full, stable benefits, and the education sector sets expectations around preventive care and time off. Those are the norms a private employer’s package is measured against.
Health care is one of the largest local employers, and manufacturing companies around Lansing need plans that work for both plant and office staff.
The practical takeaway: a Lansing employer should know which of these sectors it is really competing with for hires, and design the plan to hold up against that one.
Where Capital Region Plans Usually Have Room
Industry matters less than the current plan’s structure. In Capital Region reviews, the useful changes usually come from four places.
- How the plan is funded. Whether a fully insured Lansing group has enough enrolled lives and stable enough claims to be underwritten well for level funding; our guide to self-funded versus fully insured covers the trade-off.
- An HSA option. A higher deductible with an employer HSA deposit lowers premium and gives employees a tax-advantaged account; it only works for them if the employer deposit is meaningful.
- Dependent contributions. How much you pay toward spouse and family tiers, where cost tends to concentrate and where changes can affect ACA affordability.
- Pharmacy contract terms. For level-funded and self-funded plans, how specialty drugs are defined and whether rebates come back to the plan.
The value of each depends on the plan you have today, so we price the alternatives against your census and claims instead of promising a number up front.
Lansing Business Resources and Next Steps
The Lansing Regional Chamber of Commerce and the Michigan Chamber of Commerce, both based in Lansing, run programs and advocacy that touch benefits and employer compliance.
CFH Insurance Consultants offers Lansing employers a no-cost review of the current group plan, a comparison of funding and design options against your census, and help with compliance and employee communication.
Talk to a Lansing Benefits Advisor
If you want a second look at your Capital Region plan, talk with an advisor at CFH Insurance Consultants. We will tell you what we would change and what we would keep.
About CFH Insurance Consultants
CFH Insurance Consultants is an independent employee benefits firm founded in 2007 and based in Bloomfield Hills, Michigan. Our licensed insurance brokers advise Lansing and Capital Region employers on benefits strategy, group health insurance and compliance. Contact us to talk about your plan.
We track Michigan market changes and federal rules so employers can keep their benefits competitive and compliant, and we work with manufacturing, health care, education and professional employers.
We also put time into employer education, explaining plan changes in plain language so Lansing HR teams can answer their own employees’ questions.
Major Employers in the Lansing Region
The State of Michigan leads the regional list at roughly 13,880 employees, followed by Michigan State University (11,118), University of Michigan Health-Sparrow (about 9,000), General Motors (4,183) and McLaren Health (1,401). MSU is in East Lansing and GM’s assembly plant in Delta Township is outside the city; Lansing Grand River Assembly on Townsend Street is inside it.
So Lansing’s base is state government, a university and a health system: stable, largely unionized and setting a public-sector benchmark. A private employer’s offer is judged against that, which is why the aim is to find where those packages are weak rather than to match their budgets.
Plan for one change: in August 2026 GM filed a WARN notice for 350 layoffs effective January 2027 at Lansing Grand River and Lansing Regional Stamping, tied to retooling for the next Cadillac CT5 under a $1.25 billion investment. New production is not expected until late 2028, and GM expects to recall affected workers, who may transfer or receive supplemental pay. Suppliers should check their eligibility and continuation procedures now.
Capital Region Cities Near Lansing
- Employee benefits in East Lansing
- Employee benefits in Okemos
- Employee benefits in Grand Ledge
- Employee benefits in Mason
- Employee benefits in Williamston
- Employee benefits in DeWitt
- Employee benefits in Haslett
- Employee benefits in Holt
- Employee benefits in Dimondale
- Employee benefits in Eaton Rapids
All Greater Lansing cities we serve · Every Michigan city we serve
How CFH Works With Lansing and Capital Region Employers
Most Capital Region groups hear from their broker once a year, at renewal. We work your account all year, as an extension of your HR team. For proper coverage of an account we work in teams of 5: an account executive, an account manager, a plan analyst, customer service and IT.
Funding Compared on Your Own Numbers
We compare fully insured, level-funded and self-funded options side by side using your census and claims, not a generic illustration. Start with our guide to level-funded health plans.
Compliance Handled Through the Year
ACA reporting, ERISA, COBRA, Form 5500 and the Michigan rules that touch your plan are part of the work, not an extra. CPAs and attorneys are available through CFH once you are a client. See Michigan benefits compliance.
Small Employers Are Not an Afterthought
We work with employers from two employees up, not only mid-sized groups, and our funding advice changes with your size.
A Second Opinion Before You Switch
If you already have a broker, send us the renewal. We review it at no cost and with no obligation, and tell you what we would change and what we would keep. Read how a renewal second opinion works, or see what switching to CFH involves.
When Your Broker Changes Hands
Brokerages are bought, merged and reorganized, and your account team can change with them. If your service has slipped since that happened, a review of your current plan and renewal is a low-risk way to see what a dedicated team would do differently. If your broker was acquired, see what to check after a broker acquisition.
A Free Look at Your Lansing Renewal
We will go through a Lansing renewal and say what we would change and what we would keep. It is free and you are not obligated to move.

An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Competing with state and university benefits on a private budget? See how switching to CFH works.
Related Guides
Service Areas
Employee benefits guidance for employers in every region of Michigan we serve.
Small Group Health Insurance Guide for Michigan Employers (2 to 50 Employees)
How small group health insurance works in Michigan and how to compare your options.
Employer Benefits Guides: Eligibility, Plan Design, Life Events and Rules
Our library of plain-English guides on eligibility, plan design and compliance.
