
Funding an Allowance Instead of Choosing a Plan
An individual coverage arrangement lets you commit a defined monthly amount toward coverage that each employee selects for themselves. You control the cost precisely. They choose the network and the deductible that suits their own household rather than accepting the compromise a single group plan always represents.
This matters more in a small professional office than it does anywhere else, because the range inside a twelve-person firm is enormous: a partner in their sixties, an associate in their twenties, someone whose spouse already carries family coverage. One plan cannot serve all three well, and the employer ends up over-paying for the people who did not need it while under-serving the ones who did.
What the Arrangement Actually Requires
A written notice to employees ninety days before the plan year begins
which is a real deadline and not a formality
Employee Classes Defined on Permitted Grounds
applied consistently rather than person by person
A Substantiation Process Confirming Each Participant
A substantiation process confirming each participant actually holds individual coverage
A decision about whether the allowance varies by age and family size
which is permitted within rules
It Moves the Decision, It Does Not Remove It
The honest caveat: handing employees the choice does not mean nobody has to think. Someone still has to explain what the allowance buys locally, which carriers sell in this county and how the arrangement interacts with premium tax credits, because an employee offered an affordable allowance generally cannot claim those credits.
Done without that support, an allowance arrangement is a cost-shift with paperwork. Done properly it is often the better answer for an employer this size.
The Conventional Route, If You Prefer It
Fully Insured Small-Group Coverage
priced from rates filed and approved before the plan year opens
Dental and Vision
rated against card rates for a two-to-nine or ten-to-forty-nine band rather than built for you
Employer-Paid Life and Income Protection
straightforward and free of participation problems
Supplemental Products Employees Buy Themselves
which suit a practice with varied circumstances
Questions From Small Oakland County Practices
We have six employees. Is an allowance arrangement really available to us?
Yes, and there is no minimum size. The constraint is administrative discipline rather than headcount.
Do we still owe anything if we offer no coverage at all?
Under fifty full-time equivalents, there is no requirement to offer coverage. Other obligations, such as the Medicare prescription notice for eligible staff, still apply.
Small Firms in the City of Homes
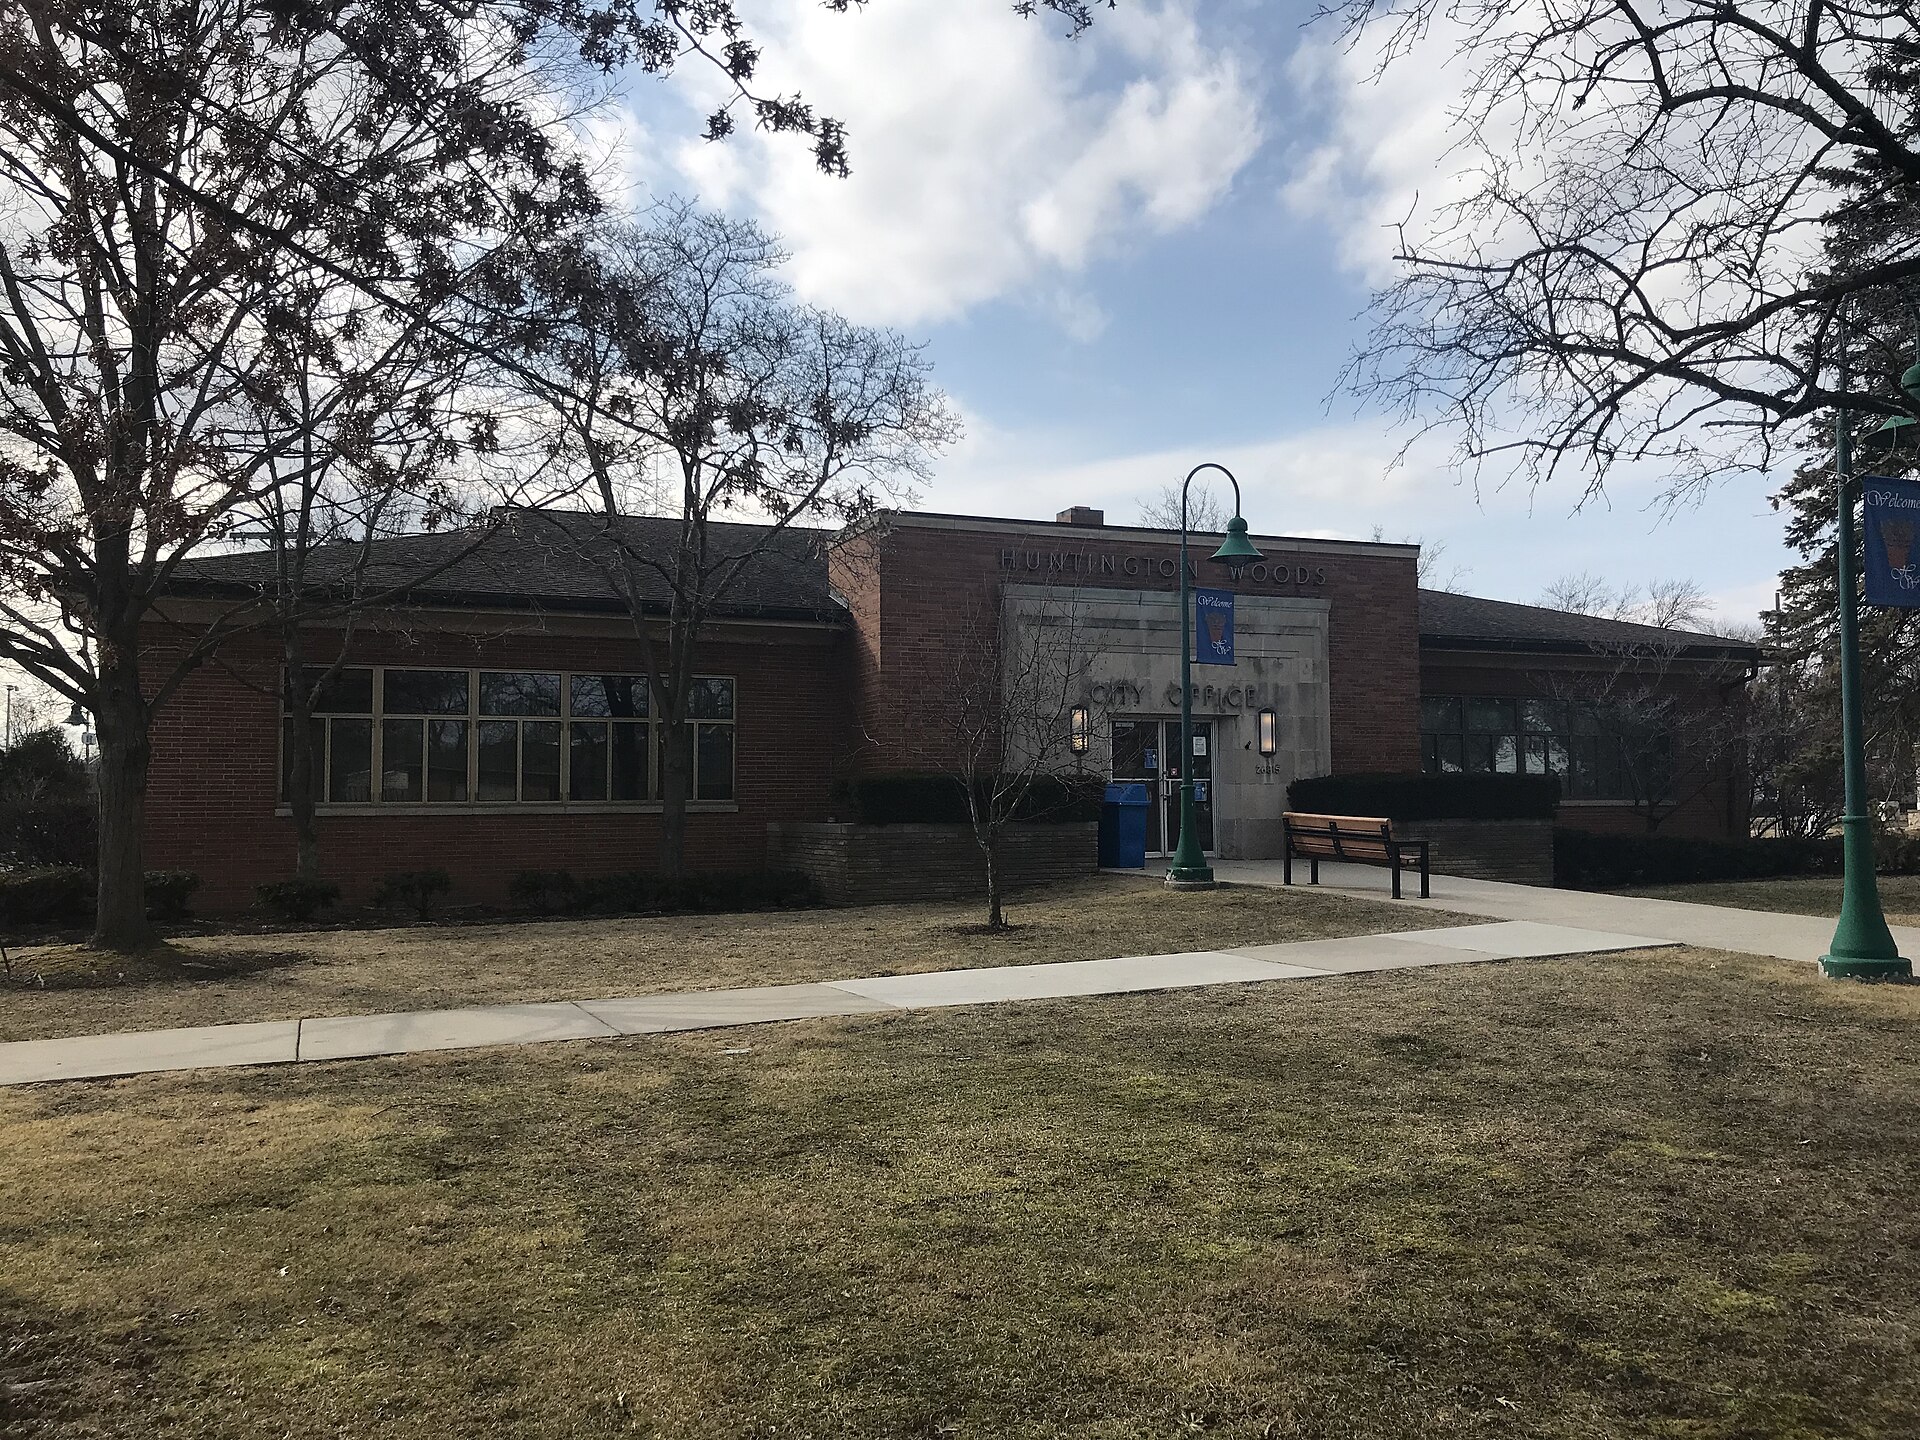
Huntington Woods is a 1.49-square-mile Oakland County city of 6,388 residents (2020 census), known as the City of Homes because it is almost entirely residential. The western portion of the Detroit Zoo sits inside city limits and contributes to its tax base, and all residents are in the Berkley School District. Bordered by I-696 to the south and Woodward Avenue to the east, the city sits between Royal Oak, Berkley, Oak Park and Pleasant Ridge, with Corewell Health William Beaumont University Hospital a short drive up Woodward in Royal Oak. Most local employers are small professional practices, home-based firms and service businesses, and many residents commute across Metro Detroit, so flexible, small-group-friendly benefits make the most sense here.
Plan Around a Major Nearby Hospital
Corewell Health William Beaumont University Hospital in Royal Oak is the natural hospital for many Huntington Woods families. We check whether each plan you consider includes Corewell Health providers, and we compare how networks treat other Oakland County and Detroit systems your employees may already use.
Weigh ICHRA for Very Small Teams
A consulting practice or home-based firm with a few employees may struggle to meet group participation rules. We compare a small group plan with an individual coverage HRA, which lets each person pick an individual plan while the employer sets a fixed monthly allowance and keeps budgeting predictable.
Watch Small-Group Renewals Closely
With only a handful of employees, one large claim or a single new hire’s age can move a renewal noticeably. We review each renewal line by line, compare carriers in the Oakland County market, and explain options before you accept an increase or change plan designs.
Round Out Benefits for Professional Staff
Professionals often value dental, vision, life and disability as much as the medical plan. We compare employer-paid and voluntary options, including long-term disability that protects higher earners’ income, so a small office can offer a competitive package without taking on large fixed costs. We also explain how to structure it clearly.
Let Us Cost Both Routes
Bring us the renewal letter, the current plan summary, the contribution split by tier and the enrolled counts by tier — two more documents if you are at fifty or above — and we will tell you what the number is actually made of. Call 248.370.8853 or write to info@cfhic.com.
Start the Review Email info@cfhic.com Call 248.370.8853
An independent employee benefits consulting firm. We look at the entire benefits program — cost, plan performance, risk and administration.
Bloomfield Hills, MI 48304
248.370.8853
Colorado Springs, CO 80921
719.425.2649
Houston, TX 77084
281.404.5670
Questions We Get
The questions employers ask us most are answered in full on our resources page.
